Earnings · Marico Limited
Marico is listed to report its September-quarter numbers on 2 November 2026. Here are the date check, the strong revenue base and low margin base, what the 5 October update already said, and the lines to read first.
Quick answer
Marico Q2 results are listed for Monday, 2 November 2026 in one weekly list. The base to beat is Rs 3,482 crore revenue and a 16.08% EBITDA margin in Q2 FY26. On 5 October Marico said revenue would grow in double digits and operating profit in the mid-twenties. Q1 FY27 margin was 20.7%.
Latest update (Saturday, 31 October 2026, 7:45 PM IST): The results are not out. Kotak Neo’s weekly list lists Marico for Monday, 2 November; the date rests on that one report and the filing time is not announced. This page becomes the live analysis after the filing.
Earlier entries:
- Friday, 30 October 2026, 6:00 PM IST: Kotak Neo listed Marico among Monday’s results.
- Monday, 5 October 2026: Marico released its Q2 FY27 business update, as carried by Business Today.
Key takeaways
- Date: Monday, 2 November 2026 from one weekly list; confirm on the exchange page.
- Base to beat: Q2 FY26 revenue Rs 3,482 crore (+31%), EBITDA Rs 560 crore at a 16.08% margin.
- Update: double-digit revenue growth and mid-twenties operating profit growth expected.
- Latest quarter: Q1 FY27 revenue Rs 3,957 crore, margin 20.7%, India volume +11%.
- Trap: two profit figures circulate for both quarters. Match the pair.
In plain words: A results preview is a checklist made before the numbers arrive. For Marico it means four marks: revenue, EBITDA margin, India volume and profit on the right basis. Knowing last year’s marks lets you judge the new figures in minutes.
Data note: Figures are as of Saturday, 31 October 2026, 7:45 PM IST. The results date comes from one weekly list; the filing itself was not opened for this page. Base figures are company results as reported by Upstox, Kotak Neo and Business Standard. The 5 October update is as reported by Business Today. Derived numbers are my calculation.
When are the Marico Q2 results?
The Marico Q2 results date is listed as Monday, 2 November 2026. The date rests on one weekly list, so confirm it on the exchange page.
Kotak Neo’s weekly list, posted at 6:00 PM IST on 30 October 2026, names Marico among the prominent companies reporting on Monday, 2 November, and says dates are based on announced board-meeting schedules and may change. A Univest preview updated on 18 September said the date had not been announced and expected results in late October or early November. I found no second report that quotes the intimation, so treat the date as likely but unconfirmed.
Last year Marico reported its Q2 FY26 numbers on Friday, 14 November 2025, so 2 November would be earlier than last year. The filing time is not announced. Do not trust a screenshot that claims a time before the exchange page shows it.
What will Marico publish?
Marico will publish unaudited results for the quarter and half-year ended 30 September 2026, with an investor presentation and, usually, an earnings call. The presentation carries the volume, margin and segment figures that the headline numbers leave out. SEBI’s listing regulations give 45 days after quarter-end, which is 14 November 2026 (my calculation).
Is the date confirmed?
| Fact | Source | Status | What to do |
|---|---|---|---|
| Results on Monday, 2 November 2026 | Kotak Neo weekly list (30 Oct 2026, 6:00 PM IST) | Single report; list is partial and dates may change | Open the BSE or NSE filing to confirm |
| Date not announced as of 18 September | Univest preview | Earlier, now outdated | Check the publication date of any preview |
| Filing time | Not announced | Unknown | Do not act on unconfirmed screenshots |
Cite this table: PositionalCalls, “Marico Q2 FY27 Date Check, as of 30 October 2026”.
Treat any article that gives another date as unreliable until you see the filing. The 5 October update is a business update, not the results, and it carries growth rates rather than profit.
What is the base to beat for the Marico Q2 results?
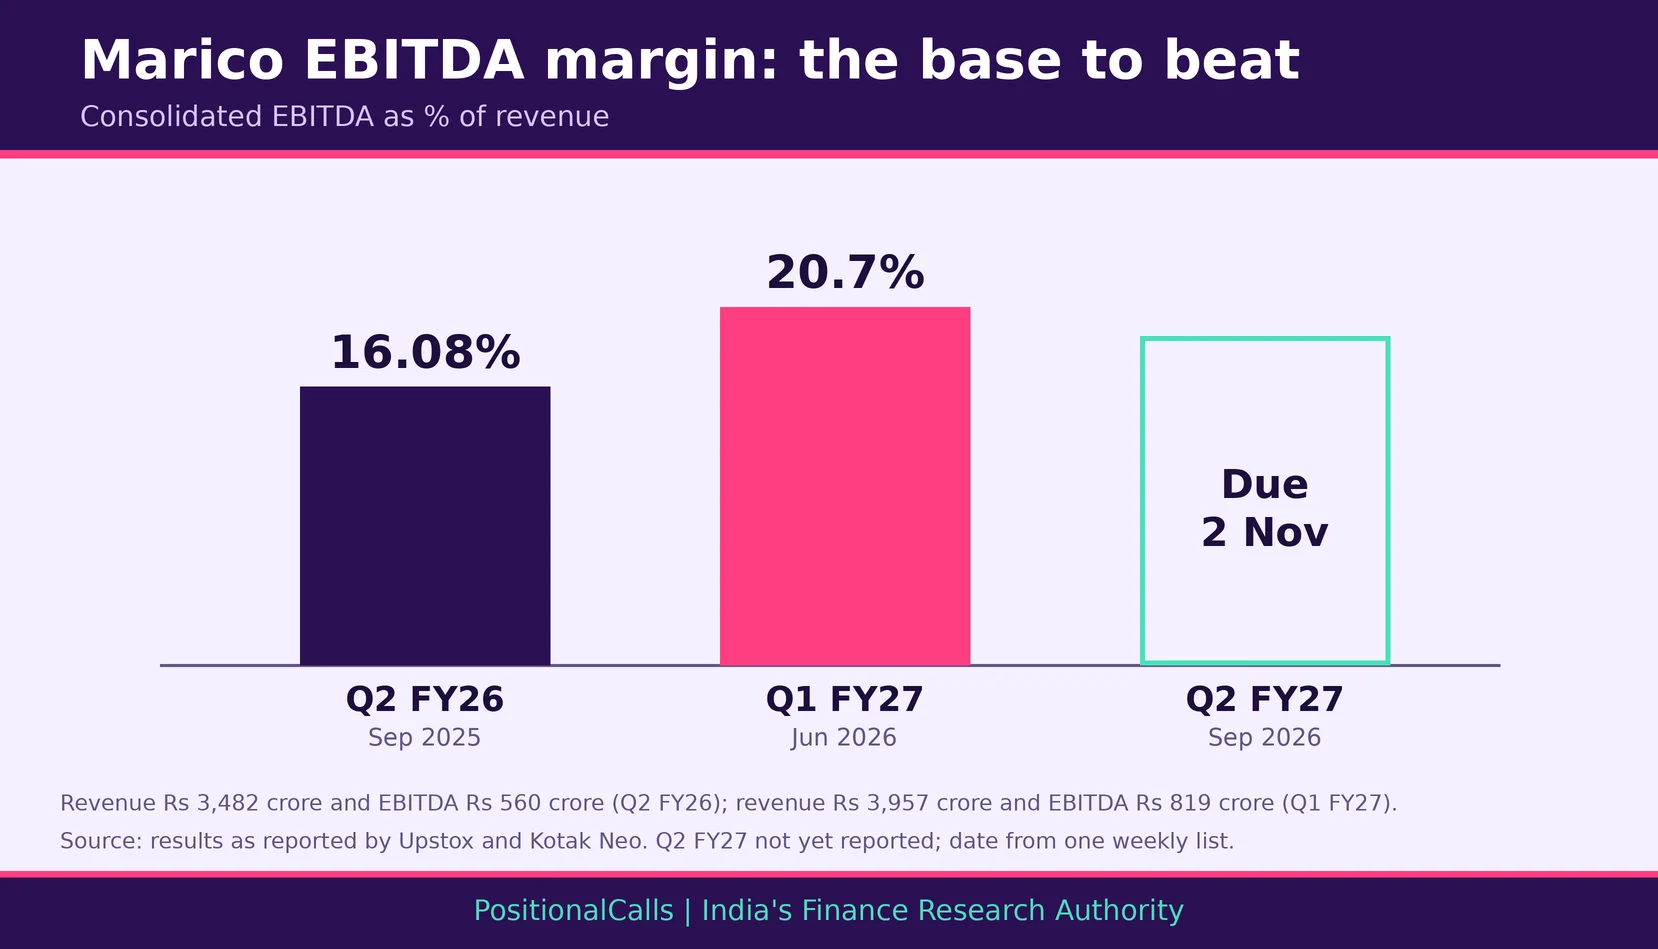
The base to beat is Q2 FY26 revenue of Rs 3,482 crore and EBITDA of Rs 560 crore at a 16.08% margin, against Rs 3,957 crore and Rs 819 crore at 20.7% in Q1 FY27.
| Measure (consolidated) | Q2 FY25 (Sep 2024) | Q2 FY26 (Sep 2025) | Q1 FY27 (Jun 2026) |
|---|---|---|---|
| Revenue from operations, Rs crore | 2,664 | 3,482 (+31%) | 3,957 (+23%) |
| EBITDA, Rs crore | 522 | 560 (+7.3%) | 819 (+25%) |
| EBITDA margin | 19.59% | 16.08% | 20.7% (+40 bps) |
| Net profit, first line, Rs crore | 423 | 420 (-1%) | 630 (+25%) |
| Net profit, second line, Rs crore | Not in sources | 432 (Univest) | 652 (+27%) |
| India volume growth | Not in sources | Not reported in source | 11%, highest in 20 quarters |
Cite this table: PositionalCalls, “Marico Base-to-Beat Table, as of 30 October 2026”.
Here is the first useful sum. Q1 FY27 revenue of Rs 3,957 crore is already +13.6% above Q2 FY26’s Rs 3,482 crore (3,957 divided by 3,482, my calculation), and Q1 EBITDA of Rs 819 crore is +46.2% above Q2 FY26’s Rs 560 crore. A flat Q2 would show growth well above the update’s “double digits” on EBITDA, because last year’s margin was low.
How was the Q2 FY26 base built?
Upstox reported revenue up 31% from Rs 2,664 crore and EBITDA up 7.3% from Rs 522 crore. The gap is the story: revenue grew four times as fast as EBITDA, so the margin fell 351 basis points (19.59% to 16.08%, my calculation). Marico said then that offtake stayed strong and more than 95% of its portfolio gained or held market share.
What does the margin base show?
The Q2 FY26 margin of 16.08% is the lowest of the three periods in the table. Q1 FY27 was 20.7%. If Q2 FY27 revenue grows 15% and EBITDA grows 25%, the margin would be about 17.5% (700 divided by 4,004, my calculation), well above the base but below Q1. That is the range to keep in mind when the filing arrives.
Marico Q2 results preview: what to expect
No consensus estimate was found, but Marico’s own 5 October update gives a range: revenue growth in double digits and operating profit growth in the mid-twenties.
| Item | What was reported | Source and date | Note |
|---|---|---|---|
| Consolidated revenue | Growth in double digits | Marico update via Business Today, 5 Oct 2026 | Not a figure; a range |
| Operating profit | Growth in the mid-twenties; strong gross-margin gain | Same | Not a figure; a range |
| India volume | Underlying growth in double digits; Parachute early-teens | Same | Q1 was 11% |
| Nuvama view | Volumes about +10%, Parachute about +14%, VAHO revenue +23%, international about +15% cc | Nuvama (Buy, target Rs 1,015) via Business Today | One house; in line with the update |
| Consensus profit estimate | None found | Not applicable | Do not read ranges as a profit forecast |
Cite this table: PositionalCalls, “Marico Q2 FY27 Update and Views, as of 30 October 2026”.
Business Today also reported that crude-linked derivative costs rose further, while copra prices stayed about 35% below peak levels. Lower copra helps the margin; higher crude-linked costs hurt it. Marico said Saffola oils grew mid-single digits on price while volumes fell, as it focused on threshold profitability, and that value-added hair oils grew in the twenties for a sixth straight quarter.
Marico EBITDA Q2 FY27: what to expect
A mid-twenties rise on Rs 560 crore is about Rs 700 crore (560 times 1.25, my calculation), which is -14.5% against Q1 FY27’s Rs 819 crore. So the update implies a sequential dip in EBITDA from Q1, even though the year-on-year rise is large. Read the quarter-on-quarter and year-on-year lines separately.
Business Today said Marico shares rose about 3% intraday on 5 October to a high of Rs 800, and closed 1.35% higher at Rs 790.65. That was a reaction to the update, not a forecast of the results, and it says nothing about what the filing will show.
Marico EBITDA and profit Q2 FY27: scenarios
These are arithmetic scenarios, not forecasts. A flat Q1 EBITDA would be +46.2% on Q2 FY26, and a flat Q1 profit would be +50.0% (630 against 420).
Assumptions: consolidated; Q2 FY26 revenue Rs 3,482 crore and EBITDA Rs 560 crore; revenue growth of 10%, 15% and 20% is my illustration around the “double digits” update; EBITDA growth of 23%, 25% and 27% is my reading of “mid-twenties”.
| Revenue growth on Q2 FY26 | EBITDA at +23% | EBITDA at +25% | EBITDA at +27% |
|---|---|---|---|
| +10% (Rs 3,830 crore) | Rs 689 crore; margin 18.0% | Rs 700 crore; margin 18.3% | Rs 711 crore; margin 18.6% |
| +15% (Rs 4,004 crore) | Rs 689 crore; margin 17.2% | Rs 700 crore; margin 17.5% | Rs 711 crore; margin 17.8% |
| +20% (Rs 4,178 crore) | Rs 689 crore; margin 16.5% | Rs 700 crore; margin 16.8% | Rs 711 crore; margin 17.0% |
Cite this table: PositionalCalls, “Marico Q2 FY27 EBITDA and Margin Scenarios, as of 30 October 2026”.
Three worked examples
- Update at face value: revenue +15% is Rs 4,004 crore and EBITDA +25% is Rs 700 crore, a margin of 17.5% against 16.08% a year ago.
- Last year’s profit pattern: Q2 FY26 profit fell 17% on the quarter, per Business Standard. A repeat would put profit near Rs 523 crore (630 times 0.83), which is +24.5% on Rs 420 crore (my calculation).
- Floor of the range: revenue +10% is Rs 3,830 crore, still below Q1 FY27’s Rs 3,957 crore.
The scenarios hold other lines constant. In practice depreciation, interest, tax, other income and international currency moves sit between EBITDA and profit. Marico also raised advertising spend 25% in Q1, and more spend in Q2 would trim margin.
Which Marico profit figure should you compare?
Compare profit with profit on the same line. Marico has two profit figures for each recent quarter, and mixing them misstates growth.
| Figure | Q2 FY26 | Q1 FY27 | The trap |
|---|---|---|---|
| Net profit, first line, Rs crore | 420 (vs 423, -1%) | 630 (+25%) | Upstox and Business Standard; Upstox Q1 article |
| Net profit, second line, Rs crore | 432 (Univest) | 652 (+27%) | Kotak Neo headline; Free Press Journal |
| Gap between lines, Rs crore | About 12 | About 22 | Possibly profit before and after minority share (my inference) |
| Revenue from operations, Rs crore | 3,482 | 3,957 | Same across sources |
| EBITDA, Rs crore | 560 | 819 | Margin 16.08% and 20.7% |
| Q1 FY26 profit, implied, Rs crore | About 506 (420 divided by 0.83) | Not applicable | Business Standard: Q2 FY26 slid 17% on the quarter |
Cite this table: PositionalCalls, “Marico Definition-Trap Table, as of 30 October 2026”.
Kotak Neo’s own article states PAT of Rs 630 crore up 25% in the body and Rs 652 crore up 27% in the headline without reconciling them. On matched bases Q1 FY27 profit is about 504 on a year earlier (630 divided by 1.25) and about 513 (652 divided by 1.27, my calculation), close to the Q1 FY26 level implied by last year’s 17% fall. Quote one pair only.
EBITDA versus profit
EBITDA is earnings before interest, tax, depreciation and amortisation. It leaves out finance cost, depreciation, tax and minority share, so profit can grow at a different rate. In Q2 FY26 EBITDA rose 7.3% while profit fell 1%, so the two lines can diverge.
Marico net profit Q2 FY27: the estimate base trap
The update gives growth rates, not rupee figures. A growth rate applied to Rs 420 crore and to Rs 432 crore gives two different profits. Check the base before you compare any estimate with the table above.
PositionalCalls WhatsApp channel
Get the Marico Q2 numbers on WhatsApp
- The Marico filing time and headline numbers, stamped
- Base-to-beat tables for the next company results
- Links to updated Q2 FY27 pages
What do Marico’s volume and brand lines need to show?
India volume growth of 11% in Q1 FY27, the highest in 20 quarters, is the bar. The update says double digits again.
| Line | Q1 FY27 as reported | Q2 FY27 update or view | Source |
|---|---|---|---|
| India volume growth | 11%, highest in 20 quarters | Double digits (company); about 10% overall (Nuvama) | Kotak Neo; Business Today |
| Parachute coconut oil | Not in sources | Early-teens volume growth; about 14% (Nuvama) | Business Today |
| Value-added hair oils | Not in sources | Growth in the twenties, sixth straight quarter | Business Today |
| Saffola oils | Not in sources | Mid-single-digit value growth; volumes down | Business Today |
| International | 15% in constant currency | About 15% in constant currency (Nuvama) | Kotak Neo; Business Today |
| Gross margin | Up 30 bps on lower copra and mix | Strong year-on-year gain (company) | Kotak Neo; Business Today |
Cite this table: PositionalCalls, “Marico Volume and Brand Marks, as of 30 October 2026”.
Q1 FY27 advertising and promotion spend rose 25%, which Kotak Neo reported alongside a gross margin gain of 30 basis points. Spend that rises faster than revenue can hold back the EBITDA margin even when gross margin improves.
Copra, the raw material for coconut oil, stayed about 35% below its peak, according to the update. Lower copra usually leads to price cuts or promotions later, so watch whether revenue growth and volume growth stay apart.
Which other results land the same week as Marico?
Kotak Neo’s weekly list shows ITC, Petronet LNG and Thomas Cook on Monday, 2 November, with Bajaj Finserv on Tuesday and Dabur on Wednesday.
The list is partial and dates may change. For the format of a results read, see our recent posts on ITC Q2 results, Titan Q2 results and Apollo Hospitals Q2 results. They cover other companies, so only the method carries over. The Q2 results calendar and the earnings calendar list the companies that have reported.
If you hold Marico shares and plan to sell later, our guide to capital gains tax on shares covers how gains are taxed. It is general information, not tax advice.
How to read the Marico Q2 results in 10 minutes
Read seven lines in order: revenue, EBITDA, EBITDA margin, India volume, both profit lines, brand lines and the notes.
| What to read | Mark to compare | Question to ask |
|---|---|---|
| Revenue from operations | Rs 3,482 crore (Q2 FY26); Rs 3,957 crore (Q1 FY27) | Is growth in double digits, as guided? |
| EBITDA | Rs 560 crore; Rs 819 crore | Is growth near the mid-twenties? |
| EBITDA margin | 16.08%; 20.7% | Did the margin recover from 16.08%? |
| India volume | 11% in Q1 | Did growth stay in double digits? |
| Net profit | 420 and 630; or 432 and 652 | Which pair does the filing use? |
| Brand lines | VAHO twenties; Saffola volumes down | Did the mix hold? |
| Notes | Advertising spend, one-offs, currency | Is any line unusual? |
Cite this table: PositionalCalls, “Marico Results-Day Decoder, as of 30 October 2026”.
How to read the Marico filing on NSE or BSE
Open the exchange announcement, find the consolidated statement and compare each line with the base table above, same measure, same basis.
- Open the BSE corporate announcements page or the NSE corporate filings page and search for Marico.
- Choose the financial results announcement for the quarter ended 30 September 2026.
- Find the consolidated statement first.
- Check the unit and whether a column is for the quarter or six months.
- Read revenue, EBITDA, total profit and profit attributable to owners.
- Open the investor presentation for India volume, margin and brand lines.
- Check the notes for exceptional items.
- Compare every figure with the base table.
What it costs: reading a filing is free. If you trade the stock, brokerage, securities transaction tax and other charges apply, so check your broker’s current schedule. Tax angle: dividends and gains follow the current tax rules, so see our guide to capital gains tax on shares or ask a tax adviser. Scam warning: on results day, fake “result alert” groups and sure-shot tips circulate. Nobody can guarantee a gain, and official filings are free.
What is the results-day checklist for Marico?
- Confirm the date on the BSE or NSE announcement page.
- Note the filing time and stamp what you read with it.
- Open the consolidated statement before any headline.
- Compare revenue with Rs 3,482 crore and Rs 3,957 crore.
- Compare EBITDA and margin with 16.08% and 20.7%.
- Check India volume against 11%.
- Check which profit line a headline quotes.
- Check the notes for one-off items.
- Write your own plan before the price moves.
What are the risks around the Marico Q2 results?
How to grade Marico’s September-quarter numbers: a reading guide
Use the table as a reading aid, not a forecast. The cut-offs are my illustration, built from the 5 October update and the Q1 FY27 marks.
Assumptions: Q2 FY26 revenue Rs 3,482 crore and EBITDA Rs 560 crore; “double digits” read as 10% or more; “mid-twenties” read as 23% to 27%.
| Mark | Stronger | In line | Weaker |
|---|---|---|---|
| Revenue growth on Q2 FY26 | Above 20% | 10% to 20% | Below 10% |
| EBITDA growth on Q2 FY26 | Above 27% | 23% to 27% | Below 23% |
| EBITDA margin | 18.0% or higher | 16.5% to 18.0% | Below 16.5% |
| India volume growth | 11% or higher | 9% to 11% | Below 9% |
| Profit growth, matched bases | Above 40% | 25% to 40% | Below 25% |
Cite this table: PositionalCalls, “Marico Q2 FY27 Reading Guide, as of 30 October 2026”.
Worked example: suppose revenue is Rs 4,000 crore, EBITDA Rs 700 crore, India volume 10% and profit Rs 530 crore. Revenue would be up +14.9% (4,000 divided by 3,482), EBITDA up +25.0%, the margin 17.5% and profit up +26.2% on Rs 420 crore (my calculation). Revenue, EBITDA, margin and volume read in line, and profit growth is stronger. Revenue growth is far below last year’s 31%, so the headline would look slower even though the quarter is solid.
A strong reading describes the quarter only. It is not a signal to buy, sell or hold, and a weak one is not a signal either. Prices react to many things, including what the market already expected.
What do most people miss on Marico results day?
- The margin base is low. 16.08% against 19.59% a year earlier sets up fast EBITDA growth.
- Revenue growth will look smaller. The base grew 31%, so double digits is a sharp slowdown.
- The update implies a sequential dip. About Rs 700 crore of EBITDA is below Q1’s Rs 819 crore.
- Two profit lines exist. Rs 630 and 652 crore, and Rs 420 and 432 crore.
- The update is not the result. Ranges can end up at either edge.
- Volume and value can diverge. Saffola value rose while volume fell.
- The date is unconfirmed. Verify before you plan around it.
Analyst’s note: how to think about this quarter
- What stands out (reasoning): a low margin base and a mid-twenties EBITDA guide mean profit growth can look strong even as revenue growth slows.
- Easy to miss: the margin recovery from 16.08% is the cleaner read than revenue growth.
- What would change the view: India volume below 9%, or an EBITDA margin below 16.5%.
- Caution: one quarter does not fix a long-term value. This page gives no target or recommendation.
- Reader action: read the same-basis figures first and match each to the base table.
Bottom line
Known: Marico is listed for 2 November 2026; the base is Rs 3,482 crore revenue and a 16.08% margin, and the 5 October update guided double-digit revenue and mid-twenties operating profit growth.
Not known yet: the confirmed date, the filing time, the actual figures and any consensus estimate.
Your move: use the decoder table and compare same-basis figures.
Next read: the Q2 results calendar, which lists the companies reporting next.
Part of the earnings coverage.
PositionalCalls WhatsApp channel
Results day, in one WhatsApp channel
- Filing alerts for Marico and other large companies
- The profit and EBITDA figures explained
- The next company on the results calendar
Marico Q2 results: frequently asked questions
When are the Marico Q2 results?
The Marico Q2 results are due on Monday, 2 November 2026, according to Kotak Neo’s weekly list posted on 30 October, which says dates are based on announced board-meeting schedules and may change. That is a single, partial-list source, so confirm on the BSE or NSE announcement page. The filing time is not announced.
What was Marico revenue and profit in Q2 FY26?
Upstox reported consolidated revenue from operations of Rs 3,482 crore, up 31%, EBITDA of Rs 560 crore at a 16.08% margin, and net profit of Rs 420 crore, down 1%. A Univest preview gives Rs 432 crore for profit, so check which line is quoted.
What did Marico report in Q1 FY27?
For the June 2026 quarter, Kotak Neo reported revenue of Rs 3,957 crore (up 23%), EBITDA of Rs 819 crore (up 25%) at a 20.7% margin, India volume growth of 11% and international growth of 15% in constant currency. Profit is given as Rs 630 crore or Rs 652 crore.
What did Marico say about Q2 FY27 in its business update?
On 5 October 2026 Marico said it expects consolidated revenue to grow in double digits and operating profit in the mid-twenties, with India underlying volume growth in double digits, as reported by Business Today. The figures are not final results.
What do analysts expect in the Marico Q2 results preview?
No consensus profit estimate was found. Nuvama (Buy, target Rs 1,015) called the update in line and expects overall volumes up about 10%, Parachute up about 14% and international up about 15% in constant currency.
Why is the Marico Q2 FY26 margin base low?
Q2 FY26 EBITDA margin was 16.08% against 19.59% a year earlier, because revenue jumped 31% while EBITDA grew only 7.3%. A low margin base means Q2 FY27 EBITDA can grow faster than revenue, as the update indicates.
Why are there two Marico profit figures?
Sources quote Rs 630 crore (up 25%) and Rs 652 crore (up 27%) for Q1 FY27, and Rs 420 crore and Rs 432 crore for Q2 FY26. Kotak Neo’s own article carries both Q1 figures without reconciling them, so match each pair and confirm in the filing.
What is VAHO and why does Marico mention it?
VAHO means value-added hair oils, a premium segment. Marico said it grew in the twenties for a sixth straight quarter in the Q2 update. Parachute coconut oil is the core brand, and Saffola edible oils are the segment where volumes fell as the company focused on profitability.
Where can I read the Marico Q2 results filing?
Use the BSE corporate announcements page or the NSE corporate filings page and search for Marico. Open the financial results PDF and the investor presentation. Ignore forwarded “result alert” images and any message that promises sure-shot calls.
By when must Marico publish its Q2 results?
SEBI’s listing regulations give listed companies 45 days after quarter-end for quarterly results. For the quarter ended 30 September 2026 that is 14 November 2026 (my calculation). Marico reported Q2 FY26 on 14 November 2025, so a 2 November date would be earlier than last year.
Sources
- BSE corporate announcements: where the Marico filing appears.
- NSE corporate filings: financial results: the same filing on NSE.
- Kotak Neo: Q2 results this week, 30 October 2026.
- Business Today: Marico shares rise after Q2 update, 5 October 2026.
- Kotak Neo: Marico Q1 FY27 results, 4 August 2026.
- Upstox: Marico Q2 FY26 results, 14 November 2025.
- Univest: Marico Q2 results FY27 preview, 18 September 2026.
- Business Standard, 14 November 2025: Q2 FY26 profit down 17% on the quarter.
Disclosure: PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent research and education site founded by Shubham Chaudhary. Nothing here is a recommendation, target or investment advice. How I researched this: I checked the results date in one weekly list, took base figures from company results as reported by Upstox and Kotak Neo, took the update from Business Today, noted where sources differ, and marked every derived number as my calculation. Figures are as of Saturday, 31 October 2026, 7:45 PM IST.
Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive