
Insurance research · Health cover guide
A plain-language guide to the best health insurance plans in India 2026: what IRDAI rules guarantee, how ten widely compared plans differ, what the nil GST on individual premiums means, how Section 126 replaced Section 80D, and what the FY26 data show.
Quick answer
The best health insurance plans in India 2026 are those that fit your age, city and family: compare sum insured, room-rent terms, waiting periods, network hospitals and claim record, not just premium. IRDAI caps pre-existing disease waits at 36 months, and individual premiums carry no GST since 22 September 2025.
Latest update (Tuesday, 17 November 2026, 12:00 PM IST): page rebuilt from the 25 October version. New: FY26 provisional premium data for standalone health insurers, the Section 126 position for FY 2026-27, and a source-conflict box on the claim ratio. Unverified per-plan claim ratios, premiums and hospital counts stay out. I did not open the IRDAI circulars or the annual report myself; the rules and figures come from named secondary summaries.
Key takeaways
- Compare clauses, not rank: room-rent terms, co-pay, sub-limits and waiting periods decide what you receive at claim time.
- Rules help you: a 36-month cap on pre-existing disease waits, a 60-month moratorium, a 1-hour cashless decision and 3-hour discharge approval.
- Cost fell: no GST on individual health premiums from 22 September 2025; group policies still carry 18%.
- Tax: Section 126 (formerly 80D) allows up to Rs 1,00,000, in the old regime only.
- Big bills: a base plan plus a super top-up can cover a large bill at lower cost than one very large base plan.
In plain words: health insurance pays hospital bills up to the sum insured you choose. The plan you pick decides how fast cover starts for old illnesses, which room you can take, and how much you pay from your pocket. The best health insurance plans in India 2026 are simply those with the fairest terms for your case.
Data note: as of Tuesday, 17 November 2026, 12:00 PM IST. Industry numbers for FY 2024-25 come from the IRDAI Annual Report as reported by Outlook Money, Ditto, TaxTMI and Business Standard. FY26 figures are provisional and come from Coverfox, Financial Express as quoted by A2Z TaxCorp, and Business Standard. Rules come from IRDAI and GST summaries. Plan-level premiums and claim ratios are not shown, because sources disagree and they change by age and city.
What are the key numbers behind the best health insurance plans in India 2026?
Health cover is growing fast, yet roughly one health claim in eight was not paid by number in FY 2024-25, so the policy wording matters more than the brand. These are the headline numbers as of Tuesday, 17 November 2026, 12:00 PM IST.
| Number | Value | Why it matters | Source |
|---|---|---|---|
| Health insurance premium, FY 2024-25 | Rs 1,27,417 crore, up 9.19% | The market is large and growing, so product changes are frequent | IRDAI Annual Report 2024-25, as reported by Outlook Money |
| Lives covered, FY 2024-25 | About 580.6 million | Shows how many people already hold some form of cover | IRDAI Annual Report 2024-25, as reported by Ditto |
| Health claims paid ratio (by number) | 85.66% (FY23), 82.46% (FY24), 87.50% (FY25) | Roughly one claim in eight was not paid in FY25, so read exclusions | IRDAI Annual Report 2024-25, extract on TaxTMI |
| Claims processed and paid, FY 2024-25 | About 3.26 crore claims; Rs 94,248 crore paid | Claim volumes are large, so insurer process quality matters | Algates Insurance; Whalesbook, citing IRDAI |
| PED waiting cap and moratorium | 36 months and 60 months | Limits how long old illnesses and disclosure disputes can hold up claims | IRDAI Master Circular, 29 May 2024, as summarised by ICICI Lombard and PolicyX |
Cite this table: PositionalCalls, “Key Health Insurance Numbers, as of 17 November 2026”; Outlook Money, Ditto, TaxTMI, Algates, Whalesbook, ICICI Lombard.
My calculation: 100% minus 87.50% leaves 12.50% of health claims by number that were not paid in FY 2024-25. That figure includes rejections and claims still pending, so treat it as a reason to read the policy, not as a verdict on any one insurer. Outlook Money also puts the overall health incurred claim ratio at 85.34%, with standalone health insurers at 68.06%.
What do the FY26 numbers show for health insurance?
Provisional FY26 data show standalone health insurers growing faster than the market after the GST exemption, with premiums of Rs 45,865 crore against Rs 38,413 crore a year earlier. These figures are unaudited and can be revised when IRDAI publishes its FY26 annual report.
| Item | What the sources say | Source |
|---|---|---|
| Standalone health insurer premium, FY26 | Rs 45,865 crore versus Rs 38,413 crore; reported growth 19.8% | Coverfox, citing IRDAI flash figures (provisional) |
| My calculation of that growth | (45,865 minus 38,413) divided by 38,413 gives 19.4%, not 19.8% | My calculation from the same two figures |
| Health premium, April 2025 to February 2026 | Up 15.32% year on year, per General Insurance Council provisional data | Financial Express, as quoted by A2Z TaxCorp |
| Standalone insurers’ market share, FY26 | 13.6%, up from 12.5% a year earlier | A2Z TaxCorp |
| General insurance industry, FY26 | Grew 9.3% to Rs 3.36 lakh crore gross direct premium; Coverfox gives 9.2% for non-life overall | Insurance Business; Coverfox |
| September 2025 versus November 2025 | Standalone insurers grew 3.09% in September, then 35.8% in November | Business Standard |
Cite this table: PositionalCalls, “FY26 Health Insurance Premium Data, as of 17 November 2026”; provisional and unaudited; Coverfox, A2Z TaxCorp, Insurance Business, Business Standard.
Two cautions apply. First, the growth is partly accounting: Business Standard says the November jump came as retail health became GST-exempt and as the 1/n method, which spreads the premium over the policy period, changed how premium is booked. Second, the gap between my 19.4% and the reported 19.8% is small, but it shows why I label the source on every number.
How do you choose the best health insurance plan in India 2026?
Pick the plan whose terms hurt you least in the worst case. Start with the wording, then compare price. The table lists the ten checks that decide most claim outcomes.
| Check | What to look for | Why it matters |
|---|---|---|
| Sum insured | Enough for a serious illness in your city; consider a super top-up for the rest | Medical bills can exceed a small base cover quickly |
| Room rent | No cap, or a cap that matches the hospitals you would use | A cap can cut the whole bill proportionately |
| Waiting periods | PED wait at or below 36 months; check disease-specific waits | Decides when known conditions are covered |
| Co-payment | None below age 60 where possible | You pay a fixed share of every claim |
| Sub-limits | No disease-wise caps on common surgeries | Caps apply even if the sum insured is large |
| Restoration | Sum insured restored after a claim; read the trigger conditions | Protects against a second claim in the same year |
| Cashless network | Your usual hospitals are listed | Reduces the cash you must arrange |
| Claim record | IRDAI data plus insurer disclosures, read with care | Shows how claims behave in practice |
| Renewal terms | Lifelong renewal, and how premium revisions work | Cover must stay affordable as you age |
| Portability | Credit for waiting periods if you switch insurers | Keeps accrued benefits |
Cite this table: PositionalCalls, “Ten Checks Before Buying a Health Plan, as of 17 November 2026”; IRDAI Master Circular of 29 May 2024 and insurer policy wordings.
Readers searching for the best mediclaim policy India 2026 often compare only price. A cheaper plan that caps room rent or adds a 20% co-pay can cost far more at claim time. For family cover, our guide to family health insurance plans covers floater maths in detail.
What do IRDAI rules guarantee on the best health insurance plans in India 2026?
IRDAI’s Master Circular on Health Insurance Business, dated 29 May 2024, set floors that insurers cannot go below, and insurers may offer better terms. These floors apply to every plan you compare on this page.
| Rule | What it says | How to use it |
|---|---|---|
| Pre-existing disease wait | Maximum 36 months; earlier practice was up to 48 months | Reject any plan quoting a longer wait for the same condition |
| Moratorium | After 60 continuous months, claims cannot be contested for non-disclosure, except proven fraud | Disclose honestly at purchase; keep cover continuous |
| Cashless approval | Insurer decides a cashless request within 1 hour | Ask the hospital desk to file the request at admission |
| Discharge approval | Final authorisation within 3 hours of the hospital’s request | Follow up if discharge is delayed |
| Entry age | No upper age limit for buying new health cover | Older buyers should compare terms, not assume refusal |
| Individual premium GST | 0% from 22 September 2025 (Notification 16/2025-CT(R)) | Check that your renewal notice shows no GST |
Cite this table: PositionalCalls, “IRDAI Health Insurance Floors, as of 17 November 2026”; IRDAI Master Circular of 29 May 2024 as summarised by ICICI Lombard, PolicyX and Bajaj General; GST notification as reported by tax explainers.
The primary documents are on the IRDAI website and the GST portal. I read the rules through several secondary summaries, so confirm clause numbers on the circular itself. If a plan quotes a longer pre-existing wait than 36 months, it does not match the 2024 rules for new products.
Which are the top health insurance companies in India, and which plans do people compare?
The ten plans below are widely compared by Indian buyers who shortlist the best health insurance plans in India 2026, listed alphabetically by insurer and not ranked. Plan versions change and newer variants exist for some products, so confirm the version on sale.
| Insurer | Plan | Built for | Headline feature to confirm in the brochure |
|---|---|---|---|
| Aditya Birla Health | Activ One Max | Wellness-minded buyers | Wellness rewards linked to healthy activity |
| Bajaj Allianz General | Health Guard | First-time, budget buyers | Entry-level hospitalisation cover with simple terms |
| Care Health | Supreme | Buyers wanting wide reach | Broad cashless network and restoration options |
| HDFC ERGO | Optima Secure | Buyers wanting higher effective cover | Cover enhancement from the first year |
| ICICI Lombard | Complete Health Insurance | People leaving employer cover | Portability from group cover and app-based claims |
| ManipalCigna | ProHealth Plus | Preventive-care buyers | Health check-ups and wellness benefits |
| Niva Bupa | ReAssure 2.0 (check newer versions) | Long-term buyers | Premium locked at entry age option; restoration of cover |
| SBI General | Arogya Supreme | Buyers outside metros | Bank-group brand and wide network |
| Star Health | Comprehensive | Families | In-house claim handling and maternity options |
| Star Health | Senior Citizens Red Carpet | Buyers aged 60 and above | Entry-age window for older buyers; check co-pay |
Cite this table: PositionalCalls, “Ten Widely Compared Health Plans, as of 17 November 2026”; alphabetical, not a ranking; the plan list is carried from the 25 October version and plan names were not re-verified against brochures.
I have left out per-plan claim ratios, premium quotes and hospital counts on purpose. Third-party sites show different figures for the same insurer, and premiums vary with age, city and sum insured. Ask each insurer for the current brochure, policy wording and a premium for your own profile, because the plan that suits a 30-year-old is not the one that suits a 62-year-old.
Among standalone health insurers, IRDAI data for FY 2024-25 showed a combined incurred claim ratio of 68.06%. As reported by Business Standard, Care Health was at 64.53%, Aditya Birla Health at 71.50% and ManipalCigna at 74.81%. These are premium-based ratios, not a ranking of service quality. Lists of the top health insurance companies India buyers see differ by whether they sort on size, claim ratio or complaints.
Which type of health insurance plan suits you: individual, family, senior or budget?
Match the structure to your household first, then compare insurers, because the best health insurance plans in India 2026 differ for each household type. Each subsection answers one common search.
Which family health insurance plans in India work for a young family?
A floater shares one sum insured across all members, which keeps the premium lower for young, healthy families. The risk is that one large claim drains the pool. Many families therefore pick a floater for self, spouse and children and a separate policy for parents. Our family floater guide shows the arithmetic.
What is the best senior citizen health insurance in India?
Senior plans differ most on co-payment, disease-wise sub-limits, waiting periods and entry age. Premiums are higher and claims are more frequent, so read these clauses first. Our guides to senior citizen health insurance and health insurance for parents compare these terms in depth.
Is a basic mediclaim policy still worth considering?
A basic mediclaim policy reimburses hospital bills up to the sum insured and little else. Modern plans add day-care cover, restoration, AYUSH and wellness features. If budget is tight, a basic plan with a super top-up can be a workable layered structure, provided you accept its caps.
Do you need a wide cashless network?
Network size matters most outside a metro or if you travel often. Count the hospitals you would actually use, not the headline number. Serious-illness cover is a different product: it pays a lump sum on diagnosis, so read critical illness insurance before assuming a hospital plan covers income loss.
How do you read a health insurer’s claim ratio without being misled?
Two different numbers are often mixed up: the claim settlement ratio counts how many claims were paid, while the incurred claim ratio compares claims with premium earned. A low incurred ratio does not prove better service, and a high one does not prove worse.
PositionalCalls WhatsApp channel
Get health insurance rule updates on WhatsApp
- IRDAI, GST and tax-limit changes, dated
- Plain-English insurance explainers
- Links to updated insurance guides
| Metric | What it measures | Limit |
|---|---|---|
| Claim settlement ratio (CSR) | Share of claims paid by number or amount | Definitions and periods differ across publishers |
| Incurred claim ratio (ICR) | Claims paid and reserved divided by premium earned | Mixes pricing with payout behaviour |
| Grievances per policies | Complaints relative to policies in force | Check Bima Bharosa data and ombudsman reports |
| Claims settled within 3 months | Speed of settlement | Does not show rejections |
Cite this table: PositionalCalls, “Health Insurance Claim Metrics, as of 17 November 2026”; IRDAI disclosures as summarised by Business Standard and Angel One.
Myth check: a single big percentage such as 98% or 99% on a blog is not proof that an insurer pays almost every claim. Angel One reports IRDAI’s February 2026 release of FY 2024-25 settlement ratios, with some insurers above 99%, but those ratios cover claims settled within three months and say nothing about rejections. Use the IRDAI Annual Report, the insurer’s public disclosures and the IRDAI Bima Bharosa portal for complaints.
My method: compare at least three years of data, prefer figures that name their source and definition, and ignore any ranking that does not show how it was built.
How much health insurance cover is enough?
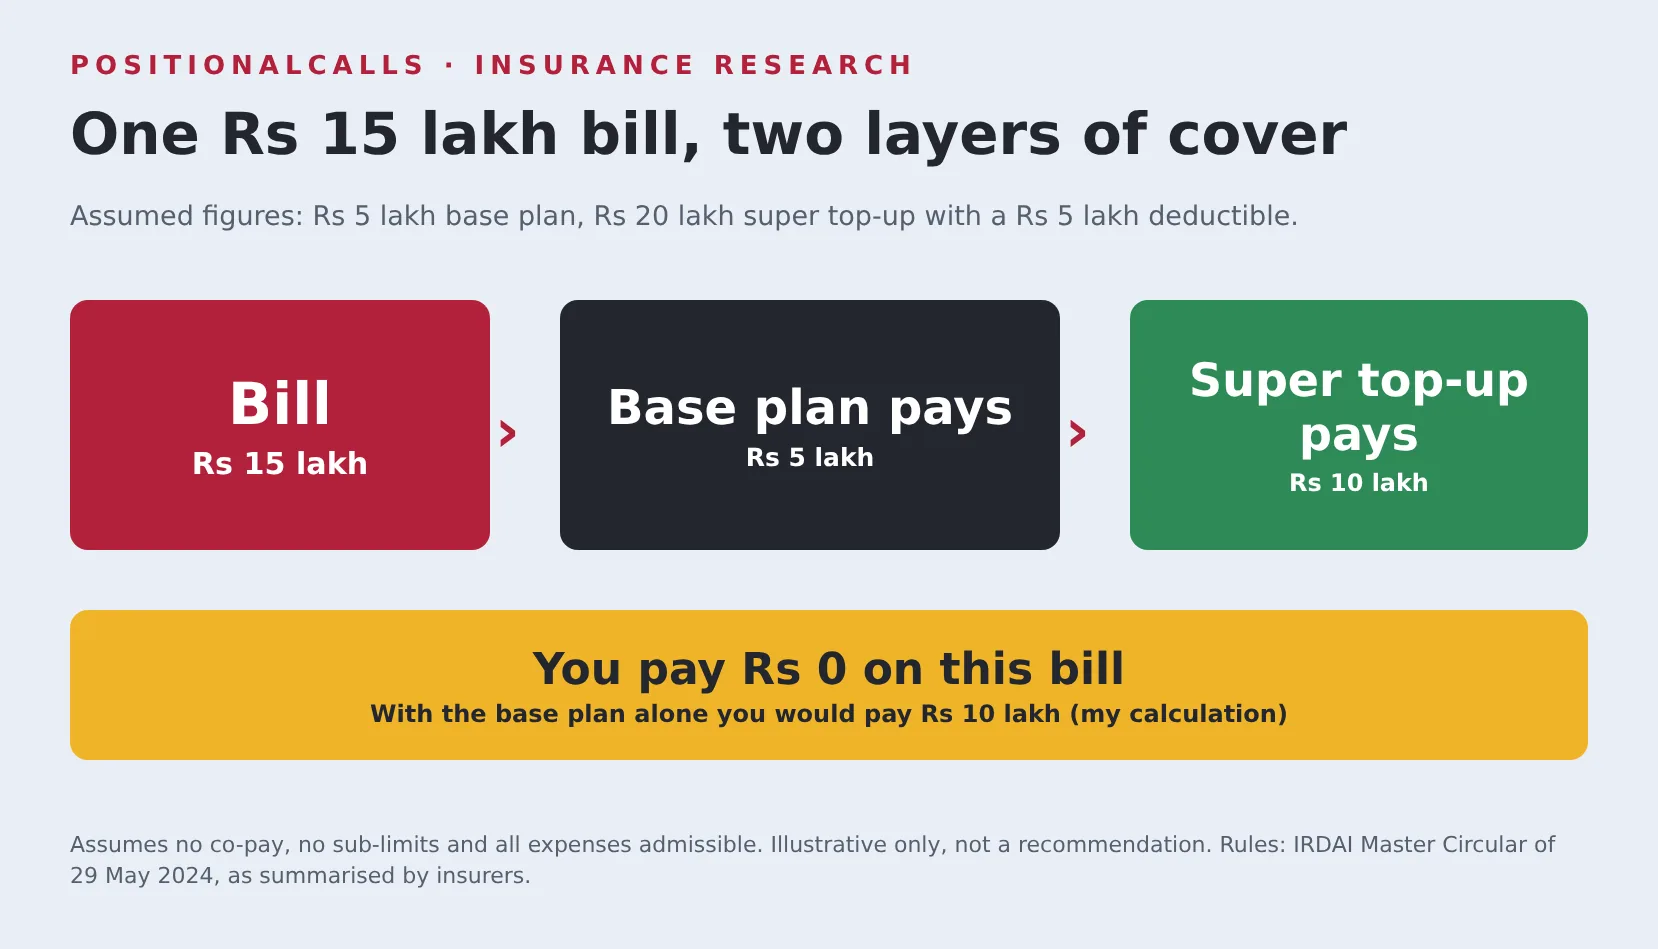
There is no universal number for the best health insurance plans in India 2026. A practical approach is to choose a base plan you can afford at renewal for life, then add a super top-up for large bills. A super top-up pays only after your bills pass a deductible, so it costs less than a big base plan.
The table is an illustration with assumed figures, not a forecast. It assumes no co-pay, no sub-limits and all expenses admissible. My calculation: out-of-pocket equals the bill minus what the base plan and the top-up pay.
| Hospital bill (assumed) | Base Rs 5 lakh only: you pay | Base Rs 5 lakh plus Rs 20 lakh super top-up (Rs 5 lakh deductible): you pay | How the bill splits |
|---|---|---|---|
| Rs 4 lakh | Rs 0 lakh | Rs 0 lakh | Base pays Rs 4 lakh, top-up pays Rs 0 lakh |
| Rs 8 lakh | Rs 3 lakh | Rs 0 lakh | Base pays Rs 5 lakh, top-up pays Rs 3 lakh |
| Rs 15 lakh | Rs 10 lakh | Rs 0 lakh | Base pays Rs 5 lakh, top-up pays Rs 10 lakh |
| Rs 30 lakh | Rs 25 lakh | Rs 5 lakh | Base pays Rs 5 lakh, top-up pays Rs 20 lakh |
Cite this table: PositionalCalls, “Base Plan versus Base Plus Super Top-Up, assumed figures, as of 17 November 2026”; my calculation, illustrative only.
Read our super top-up guide before you decide, because deductible rules and claim sequencing differ by policy.
Which of the best health insurance plans in India 2026 fits your profile?
Your life stage changes which clauses matter. Use the first table to find your profile, then the second to see which product layer does what. This is education, not a recommendation of any insurer.
| Buyer profile | Prioritise | Watch out for |
|---|---|---|
| Single professional, 25 to 35 | Enough base cover, no room-rent cap, restoration | Choosing a very low sum insured only to cut premium |
| Young family with children | Floater terms, maternity and newborn clauses, a super top-up | Maternity waiting periods and sub-limits |
| Parents aged 60 and above | Entry terms, co-pay, disease-wise sub-limits, PED wait | Co-pay that raises your share of every claim |
| Self-employed or freelancer | A personal base plan plus top-up; no group cover to fall back on | Gaps in cover while you shop around |
| Employee with group cover | Keep a personal base plan; read the group policy’s exit terms | Losing cover when you change jobs |
| Buyer with a known condition | Shortest pre-existing disease wait; full disclosure | Claim rejection for non-disclosure |
Cite this table: PositionalCalls, “Health Plan Priorities by Buyer Profile, as of 17 November 2026”; education, not advice.
| Product layer | What it pays | Best used as |
|---|---|---|
| Individual base plan | Hospital bills for one person up to the sum insured | Core cover for each adult |
| Family floater | One shared pool for all insured members | Core cover for a young family |
| Super top-up | Bills above a deductible, up to its own limit | A cheaper layer for large bills |
| Critical illness plan | A lump sum on diagnosis of listed illnesses | Income support during treatment |
| Senior citizen plan | Hospital bills with age-specific terms | Cover for buyers aged 60 and above |
Cite this table: PositionalCalls, “Health Insurance Product Layers, as of 17 November 2026”.
Treat these layers as building blocks. The best health insurance plans in India 2026 for most households combine a sound base plan with a top-up, and add a serious-illness plan only if the gap in income support worries you.
What does a health insurance plan cost in India in 2026?
The price of the best health insurance plans in India 2026 depends on age, city, sum insured, add-ons, pre-existing conditions and claim history, and I do not quote plan premiums because they change often and sources conflict. What you can check on any quote is the tax added to that premium.
From 22 September 2025, GST is nil on individual health insurance, including family floater and senior citizen plans, as per the 56th GST Council decision notified under 16/2025-CT(R). Group and employer policies still attract 18% GST.
| Item | Before 22 September 2025 | From 22 September 2025 |
|---|---|---|
| Base annual premium (example) | Rs 30,000 | Rs 30,000 |
| GST at 18% (my calculation: 30,000 x 0.18) | Rs 5,400 | Rs 0 |
| Total payable | Rs 35,400 | Rs 30,000 |
Cite this table: PositionalCalls, “Health Premium Before and After the GST Exemption, my calculation, as of 17 November 2026”; the Rs 30,000 premium is an assumed example.
The date of premium payment decides the GST treatment, not the policy start date. If a renewal notice shows GST on an individual policy paid after that date, ask the insurer to explain.
How can a room-rent cap shrink your claim?
Some policies reduce all related charges in the same ratio when the room costs more than the cap. Illustration: if the cap is Rs 5,000 a day and you take a Rs 10,000 room, 5,000 divided by 10,000 leaves 50% of room-linked charges payable. Policies without a cap avoid this. Read the clause before buying.
How much tax can you save on health insurance under Section 126?
Section 126 of the Income-tax Act, 2025 replaced Section 80D from FY 2026-27 and allows up to Rs 1,00,000 in deductions on health premiums and eligible medical spending, in the old regime only.
ClearTax says the Income-tax Act, 2025 came into effect on 1 April 2026, and that Section 126 governs health insurance deductions, replacing Section 80D of the 1961 Act, which still applies to FY 2025-26 returns. CalcGuru and SBI General describe the limits and conditions as carried over, with drafting changes. Check the Income Tax Department website for the rule text.
| Who is insured | Annual deduction limit | Note |
|---|---|---|
| Self, spouse and children (below 60) | Rs 25,000 | Includes preventive check-up up to Rs 5,000 |
| Self, spouse and children (senior citizen) | Rs 50,000 | Applies when the payer is a senior citizen |
| Parents below 60 | Additional Rs 25,000 | Separate from your own limit |
| Senior citizen parents | Additional Rs 50,000 | Cash is allowed only for preventive check-ups |
| Overall maximum | Rs 1,00,000 | Senior self plus senior parents, old regime only |
Cite this table: PositionalCalls, “Health Insurance Deduction Limits, Section 126, as of 17 November 2026”; ClearTax, CalcGuru, SBI General, ICICI Prudential Life.
My calculation: at the 30% slab, a Rs 1,00,000 deduction saves Rs 30,000 of tax, or Rs 31,200 with 4% cess, before any surcharge. That saving exists only if you choose the old regime. Aditya Birla Sun Life and ICICI Lombard both say the default new regime generally does not allow the deduction, so compare total tax under both regimes before you choose.
Qwikfilings adds that where senior citizen parents have no health insurance, their actual medical expenditure is deductible up to Rs 50,000 when paid by a non-cash mode. This is education, not tax advice, so ask a qualified tax professional before choosing a regime.
What fine print and risks should you check before buying health insurance?
In the best health insurance plans in India 2026, the clauses that cut a claim are room-rent caps, co-payment, disease-wise sub-limits, disease-specific waits, premium revisions and permanent exclusions.
- Room-rent caps: a daily cap can reduce every related charge, not just the room.
- Co-payment: a fixed share of each claim is yours, often higher for older buyers.
- Disease-wise sub-limits: caps on cataract, knee replacement or similar can apply under a large sum insured.
- Disease-specific waits: separate waits can apply beyond the pre-existing disease wait.
- Premium revision: premiums can rise with age bands and approved revisions.
- Permanent exclusions: cosmetic procedures and self-inflicted injury are typically excluded.
Non-disclosure is the most avoidable risk with even the best health insurance plans in India 2026. Declare every known condition. The 60-month moratorium protects only a policy that has run continuously without a break.
What mistakes should you avoid, and what is the buying checklist?
Most bad outcomes with the best health insurance plans in India 2026 come from a handful of avoidable mistakes, and a short checklist catches them.
- Buying on premium alone and ignoring room-rent and co-pay clauses.
- Hiding a known condition to get a lower price.
- Letting the policy lapse and losing accrued waiting-period credit.
- Assuming employer cover will last after a job change.
- Relying on a blog’s single claim-ratio number.
- Not checking whether your hospital is in the cashless network.
Checklist before you pay
- Sum insured sized for your city, with a super top-up considered.
- No or reasonable room-rent cap.
- PED wait at or below 36 months.
- Co-pay and sub-limits understood.
- Restoration conditions read.
- Lifelong renewal confirmed.
- Premium shown without GST for an individual policy.
- Policy wording downloaded before payment.
Insurance stocks are a separate topic from buying cover. Our insurance stocks research explains how listed insurers are valued, and it is educational only.
How do you buy a health plan and file a claim step by step?
To buy one of the best health insurance plans in India 2026 you need age and ID proof, bank details and an honest list of medical history; the cost is the base premium plus any add-ons, and the tax angle is in the Section 126 part above.
- Shortlist two or three plans. Match the type (individual, floater, senior) to your household.
- Download the wording. Read waiting periods, room rent, co-pay and exclusions.
- Disclose honestly. Fill the proposal form in full and keep a copy.
- Pay on the insurer’s official site or app. Check that the premium shows no GST on an individual plan.
- Plan the claim route. Save the helpline, policy number and network list; for planned surgery, request pre-authorisation.
- Escalate if stuck. Write to the insurer’s grievance cell, then use the Bima Bharosa portal or the insurance ombudsman.
Scam warning: never share OTPs or card details with callers claiming to settle or speed up a claim, and do not pay through links forwarded on messaging apps. Use only the insurer’s official site or app. This guide has no referral or affiliate links.
Term cover is a separate need; see term insurance plans.
What do most people miss about the best health insurance plans in India 2026?
The points readers most often miss are that clauses beat brand, that headline claim ratios are not comparable, and that the tax benefit needs the old regime.
- Easy to miss: room-rent and co-pay clauses affect claims more than a few hundred rupees of premium.
- Claim ratios: blog figures are not comparable; the same insurer can show different numbers, as the 68.06% and 68.73% gap shows.
- Tax: the Section 126 saving exists only in the old regime.
- What would change this view: a new IRDAI circular, a change in Section 126 limits, or a reversal of the GST exemption.
- Action: decide your base cover and renewal budget first, then compare wordings.
Bottom line
The best health insurance plans in India 2026 are the ones whose wording protects you in a worst-case claim. Check room rent, co-pay, waiting periods and renewal terms, then add a super top-up if bills could be large. Next read: family health insurance plans and the floater maths.
This page is part of the Insurance and Personal Finance research series. Our research methodology explains how I handle sources and conflicts.
PositionalCalls WhatsApp channel
Insurance updates in one channel
- Circular and tax-limit changes, dated
- Plain-English health cover guides
- Links to new insurance pages
Health insurance plans in India: frequently asked questions
Which are the best health insurance plans in India 2026?
There is no single best plan for everyone. The best health insurance plans in India 2026 are the ones whose sum insured, room-rent terms, waiting periods and network suit your age, city and family. Compare the policy wording of two or three plans, not just the premium, before you choose.
How much sum insured is enough for the best health insurance plans in India 2026?
It depends on your city, age and family size. A common method is to size the base cover for a likely hospital bill in your city and add a super top-up for large bills. The scenario table on this page shows how a Rs 5 lakh base plan and a Rs 20 lakh top-up share a bill.
Is there GST on health insurance premiums in 2026?
No GST applies to individual health insurance premiums paid on or after 22 September 2025, including family floater and senior citizen plans, per the 56th GST Council decision and Notification 16/2025-CT(R). Group and employer policies still attract 18% GST, as reported by tax and insurer explainers.
What is the maximum waiting period for pre-existing diseases?
Under IRDAI’s Master Circular on Health Insurance Business dated 29 May 2024, the maximum waiting period for pre-existing diseases is 36 months. Insurers may offer shorter waits. Always read the waiting-period clause and any disease-specific waits in the policy wording, because they can differ from the headline figure.
Which are the top health insurance companies in India?
India has standalone health insurers and general insurers that sell the best health insurance plans in India 2026 buyers compare. The top health insurance companies India buyers compare change with size and claim record every year. Use IRDAI’s annual report and each insurer’s public disclosures to compare claim data, and ignore rankings that do not show how they were built.
What is the best mediclaim policy in India 2026?
Mediclaim is an older name for basic hospitalisation cover. The best mediclaim policy India 2026 buyers choose is usually a modern plan with clear room-rent terms, restoration of the sum insured and day-care cover. A basic mediclaim policy can still suit a tight budget if you accept its limits.
Which family health insurance plans in India suit a family of four?
Family health insurance plans India buyers pick usually come as a floater, where one sum insured is shared by all members. A floater is cost-efficient for young, healthy families. If older parents are included, many families buy separate plans for them. Compare floater and individual quotes for your own ages.
What is the best senior citizen health insurance in India?
For senior citizen health insurance India buyers should check entry age, co-payment, disease-wise sub-limits and waiting periods before the premium. IRDAI’s 2024 circular removed the upper entry age for new cover, but terms still differ by plan. Our senior citizen guide goes deeper into those clauses.
How much tax can I save on health insurance under Section 126?
Under the old regime you can claim up to Rs 25,000 for self, spouse and children (Rs 50,000 if senior) plus up to Rs 25,000 or Rs 50,000 for parents, capped at Rs 1,00,000. The default new regime does not allow it. Section 126 replaced Section 80D from FY 2026-27, with limits reported as unchanged.
Should I buy health insurance or rely on my employer’s cover?
Employer cover usually ends when you leave the job, and it may be too small for a serious illness. Many people keep a personal base plan alongside group cover. This is general education, not advice. Compare your group policy’s limits and exit terms with a personal plan before you decide.
Sources
- Outlook Money: IRDAI 2024-25 annual report, health premiums cross Rs 1.27 lakh crore, press, IRDAI data.
- TaxTMI: health claims paid ratio by number, 2022-23 to 2024-25, extract of the IRDAI report.
- Ditto: IRDAI Annual Report highlights, broker explainer, lives covered.
- Algates Insurance: IRDAI Annual Report 2024-25 highlights, claims processed and paid.
- Business Standard: paying claims or pushing back, IRDAI data on insurers, January 2026, press.
- CAalley: paying claims or pushing back (Business Standard syndication), standalone insurer ratios.
- ORF: India’s health insurance boom and the transparency deficit, think-tank analysis, 68.73% figure.
- Media Infoline: health insurance payout gap analysis, trade press.
- Angel One: IRDAI releases 2026 claim settlement ratios, February 2026 release.
- Coverfox: non-life growth in FY26 led by health, 17 April 2026, provisional.
- A2Z TaxCorp: GST cut lifts health insurance premiums to record in FY26, quotes Financial Express and GIC provisional data.
- A2Z TaxCorp: standalone health insurers’ market share 13.6% in FY26, provisional.
- Insurance Business: India insurance growth to cool in FY27, 5 May 2026, trade press.
- Business Standard: robust growth, valuations to drive gains for general insurers, December 2025, 1/n accounting.
- Business Standard: health, motor insurance sales jump on GST exemption, 3 November 2025, press.
- Business Standard: muted growth after the GST revamp, 7 October 2025, General Insurance Council data.
- ICICI Lombard: new IRDAI health insurance guidelines, insurer explainer.
- PolicyX: IRDAI health insurance rules, 16 September 2026, aggregator.
- ClearTax: Section 126 of the Income-tax Act, 2025, tax explainer.
- CalcGuru: health insurance and 80D, what the new regime leaves you, tax explainer.
- SBI General: can medical bills be claimed under Section 80D, insurer explainer.
- Aditya Birla Sun Life Insurance: health insurance tax benefits, old vs new regime, insurer explainer.
- Qwikfilings: Section 80D tax savings on health insurance, filing explainer.
- PositionalCalls: family health insurance plans, senior citizen health insurance, super top-up health insurance, critical illness insurance and insurance stocks research.
PositionalCalls.com is an independent research site founded by Shubham Chaudhary. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser, and it is not an IRDAI-licensed insurance adviser. This guide is educational only and makes no plan recommendation, target or guarantee. How this was researched: I did not open the IRDAI circulars, the annual report, the GST notification or the Income-tax Act myself. Rules, ratios and tax limits come from named secondary summaries and insurer pages, and FY26 figures are provisional. The ten plan names were carried from the 25 October version and not re-checked against current brochures. Confirm terms with the insurer before buying.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive