
Sector outlook · Banking
Looking for PSU bank stocks in India 2026? This page replaces the earlier quick-picks list with a side-by-side of ten public sector banks on reported Q2 FY27 profit, asset quality, loan and deposit growth and capital, and shows how to compare them yourself. It names no winners.
Quick answer
The PSU bank stocks in India 2026 cannot be ranked from data alone, because the right bank depends on your goal. Ten public sector banks reported Q2 FY27 profit growth from 8.4% (Canara Bank) to 41.4% (Bank of Maharashtra), and gross NPA from 1.25% to 2.55%. This page compares them with no picks.
Latest update (Saturday, 14 November 2026, 4:45 PM IST): Rebuilt around Q2 FY27 results, replacing the six-bank list, the “Quick Picks” box and the value labels, which had no figures behind them. I could not open any bank filing, so figures are headline-level from press reports and summary pages.
Key takeaways
- No picks: there is no ranked list, rating, score or price target here. The earlier “Best Overall”, “Safest” and “Turnaround” labels are removed because no data supported them.
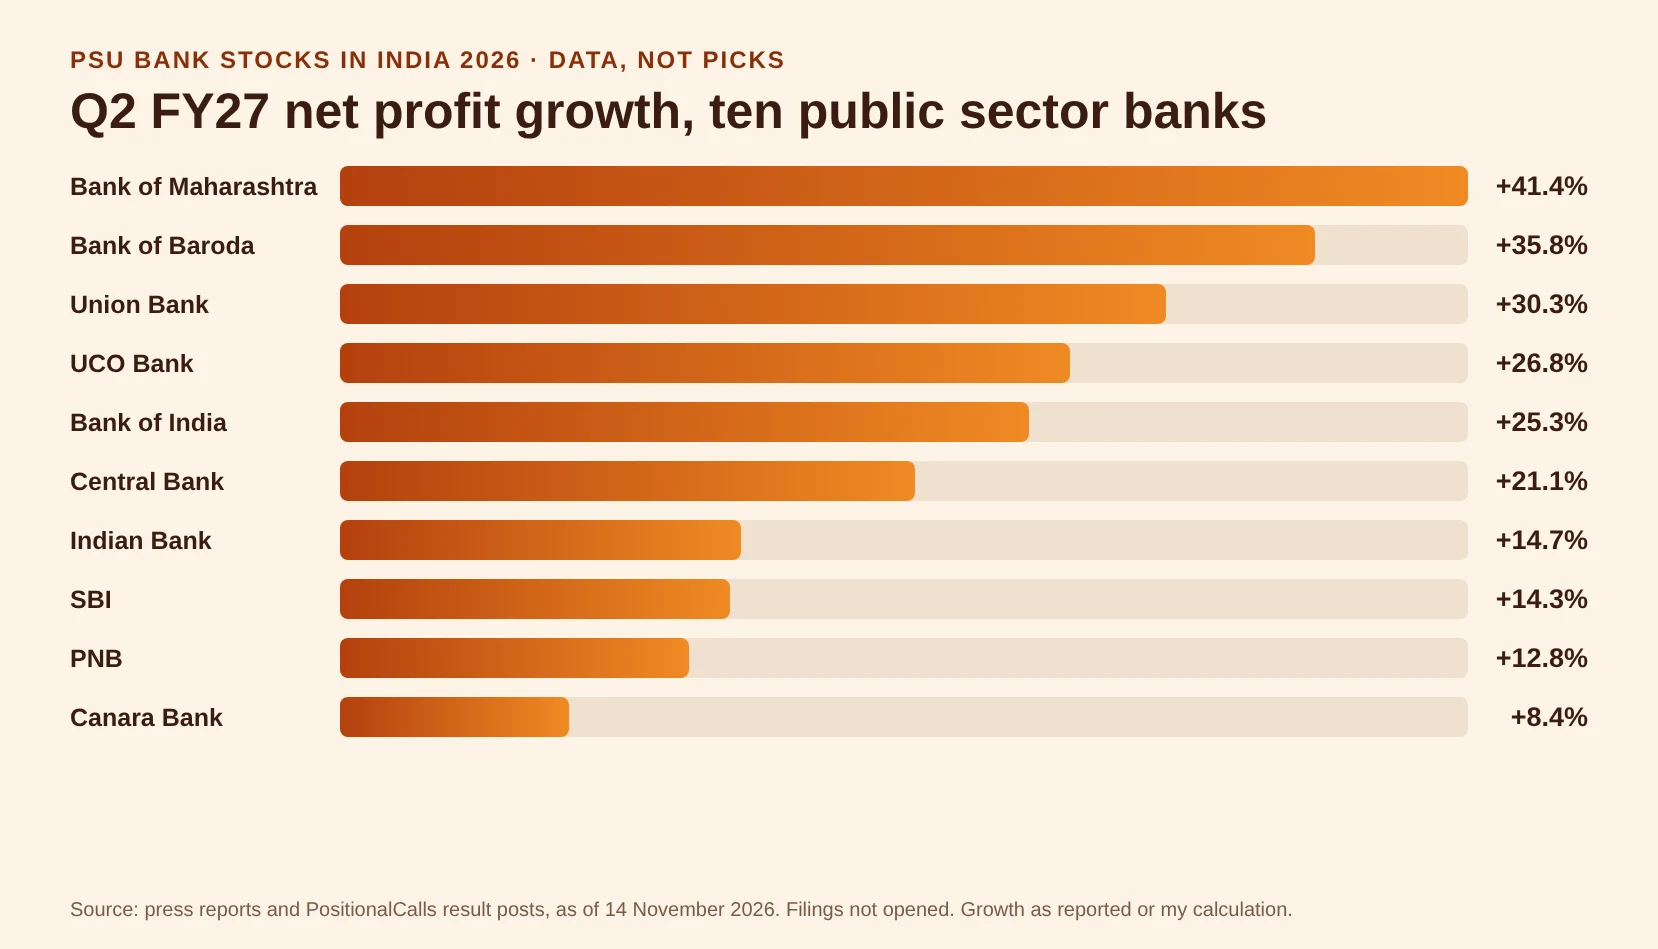
- Profit growth: Bank of Maharashtra +41.4%, Bank of Baroda +35.8%, Union Bank +30.3%, UCO +26.8%, Bank of India +25.3%, Central Bank +21.1%, Indian Bank +14.7%, SBI +14.3%, PNB +12.8%, Canara +8.4%.
- Asset quality: gross NPA ranged from 1.25% at Bank of Maharashtra and 1.33% at Canara to 2.39% at Central Bank and 2.55% at PNB; net NPA was 0.12% to 0.42%.
- Margins: NIM was 2.55% to 2.94% at the five banks that reported one, against 3.32% to 4.31% at four private banks on my other page.
- Quality of growth: SBI’s base had a Rs 4,593 crore gain, Bank of Baroda booked a Rs 4,093 crore treasury gain, and Indian Bank’s operating profit growth falls from 46.58% to 18% without NSE-related gains.
- Group view: about Rs 57,042 crore of combined profit for the ten, up about 19.0% (my calculation); the five largest rose 17.8% and the five smaller ones 24.2%.
In plain words: every public sector bank I checked earned more than a year ago, and bad-loan ratios fell at every bank where I found a year-ago figure. What separates them is how much of the profit came from one-off gains, how thin the margin is, and whether deposits are growing as fast as loans.
Data note: Figures are as of 14 November 2026, 4:45 PM IST and cover the quarter to 30 September 2026, standalone unless stated. They follow PSU Connect, Free Press Journal, Business Today, Multibagg, a Geekchamp summary of Canara Bank, Upstox and 5paisa, and my own SBI and Bank of Baroda posts. I could not open the exchange filings. Derived numbers are my calculation. Indian Overseas Bank and Punjab & Sind Bank are not in the tables.
1. What can a data page say about PSU bank stocks in India 2026?
A data page can show which public sector banks grew profit fastest, which have the cleanest loans and which keep the widest margin, but it cannot name the best PSU bank stocks in India 2026, because the right bank for a safety seeker differs from the right bank for a growth seeker.
Searches for PSU bank stocks in India 2026 usually want a short list. That is a recommendation, and PositionalCalls is not SEBI registered and gives no buy or sell calls. What I can do is put the reported numbers side by side so you can apply your own goal. The table below maps the common goals to the measure that actually tests them.
| If your goal is | Check this measure | Q2 FY27 evidence on this page | Caution |
|---|---|---|---|
| Safety | Gross and net NPA, capital adequacy, provision coverage | Gross NPA from 1.25% (Bank of Maharashtra) to 2.55% (PNB); capital adequacy found for four banks, 16.21% to 17.19% | Capital adequacy is missing for six of ten banks |
| Growth | Advances growth and whether deposits keep pace | Advances growth 14.7% to 30.16%; deposit growth 6.87% to 21.59% | Loan growth outrunning deposits can squeeze margins |
| Profitability | NIM, operating profit and net profit growth | NIM 2.55% to 2.94% where found; profit +8.4% to +41.4% | One-off gains lift some of the growth |
| Dividends | Payout history and capital buffers | Not covered here; no dividend figures were checked | See the dividend page and the tax guide |
| Government link | Government shareholding and capital plans | Not covered here | Check the latest shareholding pattern |
| Value | Price-to-book against return on equity | No price or valuation data used | Valuation needs live prices, which this page does not use |
Cite this table: Goal-to-measure map by PositionalCalls; evidence from the Q2 FY27 figures in the tables below, as of 14 November 2026, 4:45 PM IST.
What changed from the earlier version
The earlier page opened with a “Quick Picks” box naming a best overall, best high-growth, best value, safest, high-ROE and turnaround bank, and listed six banks with one-line strengths and no figures. It also carried a sector snapshot table with trend words such as “strong” and “improving” and no numbers. I removed the labels and replaced the words with reported Q2 FY27 data for ten banks. The earlier list stopped at six names, and I added Bank of India, Bank of Maharashtra, Central Bank and UCO Bank because their results were available.
Background from the earlier version, not re-checked here: several banks in this group were enlarged by the 2019 and 2020 public sector bank mergers, which is why Bank of Baroda, PNB, Canara, Union Bank and Indian Bank are much larger than they were. The mergers matter for comparing old figures, but this page uses only Q2 FY27 against Q2 FY26.
2. What did ten public sector banks report in Q2 FY27?
Across PSU bank stocks in India 2026, all ten banks grew profit. Bank of Maharashtra rose 41.4%, Bank of Baroda 35.8%, Union Bank 30.3%, UCO 26.8%, Bank of India 25.3%, Central Bank 21.1%, Indian Bank 14.7%, SBI 14.3%, PNB 12.8% and Canara 8.4%, while margins and asset quality differed more than profit.
| Bank (Q2 FY27) | Net profit (Rs crore) | Profit change | NIM | Gross NPA | Net NPA |
|---|---|---|---|---|---|
| SBI | 23,038 | +14.3% | 2.94% | 1.39% | 0.36% |
| Bank of Baroda | 6,531.5 | +35.8% | 2.74% | 1.78% | 0.37% |
| Union Bank of India | 5,537 | +30.3% | 2.86% | 2.42% | 0.42% |
| Punjab National Bank | 5,532 | +12.8% | 2.58% | 2.55% | Not found |
| Canara Bank | 5,175 | +8.4% | 2.55% | 1.33% | 0.30% |
| Indian Bank | 3,462.2 | +14.7% | Not found | 1.61% | 0.14% |
| Bank of India | 3,202 | +25.3% | Not found | 1.60% | 0.42% |
| Bank of Maharashtra | 2,310 | +41.4% | Not found | 1.25% | 0.12% |
| Central Bank of India | 1,468.9 | +21.1% | Not found | 2.39% | 0.31% |
| UCO Bank | 785.6 | +26.8% | Not found | 1.96% | 0.18% |
Cite this table: Q2 FY27 results per PSU Connect, Free Press Journal, Business Today, Multibagg, Geekchamp, Upstox, 5paisa and PositionalCalls result posts; growth rates as reported or my calculation from the stated year-ago profit; filings not opened.
Adding the ten profits gives about Rs 57,042 crore against about Rs 47,934 crore a year earlier, a rise of about 19.0% (my calculation). SBI alone is about 40% of the total. The five largest banks (SBI, Bank of Baroda, Union, PNB and Canara) rose about 17.8%, and the five smaller banks (Indian Bank, Bank of India, Bank of Maharashtra, Central Bank and UCO) rose about 24.2%, partly because they start from lower profits. Year-ago profit for PNB and Bank of India is back-calculated from reported growth rates, so the totals are approximate. Indian Overseas Bank’s headline profit of Rs 1,912 crore and Punjab & Sind Bank are not in the totals because I found no usable detail. For the sector-level reading, see my banking sector outlook 2026 and banking sector earnings pages.
3. What do the numbers show bank by bank?
Each card below lists only reported Q2 FY27 facts and one thing to verify in the filing. None is a rating.
SBI
Net profit Rs 23,038 crore (+14.3%) on a year-ago base of Rs 20,160 crore that included a Rs 4,593 crore gain, per my SBI Q2 results FY27 post. NIM 2.94%, gross NPA 1.39%, net NPA 0.36%. Advances grew 17.84% and deposits 12.27%. Check in the filing: Whether the base-year gain distorts the growth rate.
Bank of Baroda
Net profit Rs 6,531.5 crore (+35.8%, a record), NIM 2.74%, gross NPA 1.78%, net NPA 0.37%, capital adequacy 16.61%. Treasury income was Rs 4,093 crore against Rs 1,086 crore, linked to an NSE share sale; loans grew 18% (13.5% excluding FCNR(B)). See my Bank of Baroda Q2 results FY27 post. Check in the filing: How much of the profit rise is the one-time treasury gain.
Union Bank of India
Net profit Rs 5,537 crore (+30.3% from Rs 4,249 crore), NII Rs 10,583 crore (+20.09%), NIM 2.86% (3.03% excluding a tax refund), gross NPA 2.42% against 3.29%, net NPA 0.42% against 0.55%. Domestic advances grew 17.35% and deposits 6.87%. Treasury income was Rs 701 crore against Rs 1,073 crore. Check in the filing: The gap between loan and deposit growth.
Punjab National Bank
Net profit Rs 5,532 crore (+12.8%), NIM 2.58% (2.50% in Q1), gross NPA 2.55%, down 90 bps, slippage ratio 0.77% against 0.71%. Advances grew 14.7% and deposits 9.9%. Check in the filing: Why slippage rose while the NPA ratio fell.
Canara Bank
Net profit Rs 5,175 crore (+8.4% from Rs 4,774 crore), NII Rs 11,005 crore (+20.4%), NIM 2.55%, gross NPA 1.33%, net NPA 0.30%, provision coverage 95.34%, capital adequacy 17.19%. Global advances grew 19.5% and deposits 13.1%. A summary page reports operating profit up only 1.98% and other income down 18.17%, and that management expects Rs 10,000 to 12,000 crore of extra expected-credit-loss provisioning over one to two years with no Q2 impact. These come from automated summary pages, so treat them as unconfirmed. Check in the filing: Why operating profit grew far less than NII, and the provisioning plan.
Indian Bank
Net profit Rs 3,462 crore (+14.7% from Rs 3,018 crore), gross NPA 1.61% against 2.60%, net NPA 0.14% against 0.16%, slippage ratio 0.69%. Operating profit rose 46.58%, or 18% excluding NSE-related gains. Capital adequacy is given as 16.21% by one source, while another lists 16.21% as Tier 1 with CET1 at 15.18%. Management raised its FY27 guidance for advances growth to 13% to 14% (from 11% to 13%) and deposits to 11% to 12% (from 9% to 11%); these are guidance, not results. Check in the filing: The total capital adequacy ratio, and how much operating profit came from NSE-related gains.
Bank of India
Net profit Rs 3,202 crore (+25.34%), operating profit Rs 5,089 crore (+33.19%), NII Rs 7,007 crore (+18.52%), gross NPA Rs 13,648 crore (1.60%, down 24.24% in amount), net NPA Rs 3,557 crore (0.42%). Global advances were Rs 8,55,071 crore (+20.58%) and deposits Rs 10,37,530 crore (+21.59%). Check in the filing: NIM and capital adequacy, which I did not find.
Bank of Maharashtra
Net profit Rs 2,310 crore (+41.42% from Rs 1,633 crore, the highest growth of the ten), NII Rs 3,954 crore (+21.76%), gross NPA 1.25% against 1.72%, net NPA 0.12% against 0.18%. Net advances were Rs 3,25,641 crore (+30.16%) and deposits Rs 3,76,407 crore (+21.50%). The shares rose 1.06% to Rs 76.10 on the results day, 26 October. Check in the filing: NIM and capital adequacy, which I did not find, and how 30% loan growth is funded.
Central Bank of India
Net profit Rs 1,468.86 crore (+21.1% from Rs 1,212.88 crore), operating profit Rs 2,268.30 crore (+27.0%), gross NPA 2.39% against 3.01%, net NPA 0.31% against 0.48%, capital adequacy 17.18%, annualised return on assets 1.03%. The source gave no NII, NIM or growth figures. Check in the filing: Why gross NPA is still above 2%, and the slippage trend.
UCO Bank
Net profit Rs 785.64 crore (+26.8% from Rs 619.76 crore) on total income of Rs 8,174.08 crore (+10.14%), gross NPA 1.96% against 2.56%, net NPA 0.18% against 0.43%. A provisional business update on 1 October showed advances of Rs 2.88 lakh crore, up 24.68%. Check in the filing: What drove profit growth well above income growth; the sources do not say.
4. How clean are the loans behind PSU bank stocks in India 2026?
Gross NPA ratios fell at every bank among the PSU bank stocks in India 2026 where I found a year-ago figure. The ratios range from 1.25% at Bank of Maharashtra to 2.55% at PNB, with Union Bank, PNB and Central Bank still above 2.3%.
PositionalCalls WhatsApp channel
Follow public sector bank results
- Quarterly PSU bank results in plain words
- NPA, margin and loan-growth numbers without tips
- A message when this page is updated
| Bank | Gross NPA Q2 FY27 | Year-ago gross NPA | Fall, bps (my calculation) | Net NPA Q2 FY27 / year-ago |
|---|---|---|---|---|
| Bank of Maharashtra | 1.25% | 1.72% | 47 | 0.12% / 0.18% |
| Canara Bank | 1.33% | Not found | Not found | 0.30% / not found |
| SBI | 1.39% | Not found | Not found | 0.36% / not found |
| Bank of India | 1.60% | Not found (amount down 24.24%) | Not found | 0.42% / not found |
| Indian Bank | 1.61% | 2.60% | 99 | 0.14% / 0.16% |
| Bank of Baroda | 1.78% | Not found | Not found | 0.37% / not found |
| UCO Bank | 1.96% | 2.56% | 60 | 0.18% / 0.43% |
| Central Bank of India | 2.39% | 3.01% | 62 | 0.31% / 0.48% |
| Union Bank of India | 2.42% | 3.29% | 87 | 0.42% / 0.55% |
| Punjab National Bank | 2.55% | About 3.45% (implied) | 90 (reported) | Not found |
Cite this table: Asset quality per PSU Connect, Free Press Journal, Business Today, Multibagg, Geekchamp and my Bank of Baroda post; PNB year-ago is implied by its reported 90 bps fall; filings not opened.
The weakest starting points moved the most: Indian Bank’s ratio fell 99 bps, PNB’s 90 bps and Union Bank’s 87 bps. A buyer who defines safety as the lowest ratio would read the table one way, and one who defines it as the biggest improvement would read it another way. That is why I do not rank. Net NPA is low everywhere, at 0.12% to 0.42% among the nine banks with a figure, which reflects heavy provisioning, so the gap between gross and net NPA is itself a data point to read in the filing.
PSU bank stocks in India 2026 and the capital adequacy gap
| Bank | Capital adequacy | Note |
|---|---|---|
| Canara Bank | 17.19% | Basel III, per a summary page |
| Central Bank of India | 17.18% | Basel III, per PSU Connect |
| Bank of Baroda | 16.61% | Per my result post |
| Indian Bank | 16.21% | Sources conflict: one calls it Tier 1, with CET1 15.18% |
| Other six banks | Not found | Read the Q2 filing |
Cite this table: Capital adequacy per PSU Connect, Multibagg, Geekchamp and my Bank of Baroda post; filings not opened.
Capital adequacy shows how much loss a bank can absorb, and I found it for only four of the ten banks. The earlier page said capital strength had been “strengthened through government recapitalization” without a figure for any bank. If safety matters to you, read the capital adequacy and common equity lines in each bank’s Q2 filing and compare them with the RBI minimum for its category.
5. How fast are PSU banks growing, and is deposit growth keeping up?
Among PSU bank stocks in India 2026, advances grew 14.7% to 30.16% at the banks with figures, and deposits lagged loans at most of them, with Union Bank’s domestic deposits trailing its advances by 10.5 points. Bank of India was the exception, with deposits growing slightly faster than advances.
| Bank | Advances growth | Deposit growth | Gap, points (my calculation) |
|---|---|---|---|
| Bank of Maharashtra (net advances) | 30.16% | 21.50% | 8.7 |
| Canara Bank (global) | 19.5% | 13.1% | 6.4 |
| SBI | 17.84% | 12.27% | 5.6 |
| Union Bank (domestic) | 17.35% | 6.87% | 10.5 |
| Punjab National Bank | 14.7% | 9.9% | 4.8 |
| Bank of India (global) | 20.58% | 21.59% | -1.0 |
| UCO Bank (provisional, 1 October) | 24.68% | Not found | Not found |
Cite this table: Advances and deposit growth per Business Today, Free Press Journal, Geekchamp, 5paisa, Multibagg and PSU Connect; definitions differ by bank (net, gross, global, domestic); provisional where noted.
A gap matters because a bank that lends faster than it gathers deposits has to find funding elsewhere, which can cost margin. I did not find the funding mix for any bank, so I cannot say how much each gap costs. Indian Bank gave FY27 guidance, not a result: advances growth of 13% to 14% and deposit growth of 11% to 12%. At the system level, RBI data reported by The Week shows bank credit up 17.94% against deposits up 16.60% on 15 October 2026, a gap of 1.34 points (my calculation).
6. How do PSU banks compare with private banks on this data?
On Q2 FY27 data the public sector banks grew profit faster as a group, but they earned thinner margins and carried higher gross NPA than the four large private banks on my other page, so the comparison depends on which measure you pick.
| Measure | Public sector banks (this page) | Four private banks (my other page) |
|---|---|---|
| Profit growth, group | Ten banks about +19.0%; five largest +17.8% | HDFC Bank, ICICI, Axis and Kotak about +15.8% |
| Profit growth, range | +8.4% to +41.4% | +4.7% to +38% |
| NIM, range found | 2.55% to 2.94% (five banks) | 3.32% to 4.31% |
| Gross NPA, range | 1.25% to 2.55% | 1.04% to 1.20% |
| Loan growth, range reported | 14.7% to 30.16% | 16.3% to 30% |
| FCNR(B)-adjusted loan growth | Bank of Baroda 13.5% (others not found) | ICICI 24.1%, Kotak 19%, Axis 19% |
Cite this table: Public sector figures from this page; private figures from my best bank stocks in India 2026 data page; groups are not like-for-like in size; filings not opened.
The private banks’ margin advantage is large, about 0.4 to 1.8 points of NIM on the figures found (my calculation), and their gross NPA ratios are all near 1% to 1.2%. Public sector banks have caught up on asset quality at several names, with Bank of Maharashtra at 1.25% and Canara at 1.33%. For the full private-bank comparison, see my best bank stocks in India 2026 data page, which keeps to its own question.
7. Where does profit growth in PSU bank stocks in India 2026 come from?
At SBI a one-time gain in the year-ago base lowers the growth rate, at Bank of Baroda a treasury gain from an NSE share sale lifts it, and at Indian Bank NSE-related gains explain about 61% of operating profit growth. The source of profit matters as much as its size.
| Bank | Profit growth | Item that affects it | Direction of effect |
|---|---|---|---|
| SBI | +14.3% | Year-ago base included a Rs 4,593 crore gain | Lowers reported growth |
| Bank of Baroda | +35.8% | Treasury income up about Rs 3,007 crore on an NSE share sale | Lifts profit; one-time |
| Indian Bank | +14.7% | Operating profit +46.58%, or +18% excluding NSE-related gains | Lifts operating profit; one-time |
| Union Bank | +30.3% | NIM 3.03% excluding a tax refund; treasury income fell to Rs 701 crore from Rs 1,073 crore | Refund lifts NIM; treasury lowers profit |
| Canara Bank | +8.4% | Operating profit +1.98% and other income -18.17% on a summary page; extra provisioning expected | Lower non-interest income; provisions a risk |
| Bank of India | +25.3% | Operating profit +33.19%, ahead of net profit growth | Gap between operating and net profit |
Cite this table: Items per my SBI and Bank of Baroda posts, Multibagg, PSU Connect, Free Press Journal and a Geekchamp summary; differences are my calculation and are before tax where treasury is concerned.
Indian Bank is the clearest example: operating profit rose 46.58% but only 18% without NSE-related gains. That means about 28.6 points of the growth, or roughly 61% of it, came from those gains (my calculation: 46.58 less 18, divided by 46.58). Bank of Baroda’s treasury income rose about Rs 3,007 crore, more than its Rs 1,722 crore rise in net profit, again with the before-and-after-tax caveat. I did not find whether other banks in this group booked NSE-related gains, so I do not assume either way. Check each bank’s other-income note.
8. How do you compare PSU bank stocks in India 2026 yourself?
Pick your goal first, then compare banks on the matching measures from the latest filing, adjust for one-time items, and look at more than one quarter before you form a view.
- Fix the goal: safety, growth, dividends or a long holding period each need different measures, as the table in section 1 shows.
- Read the filing, not the headline: open the results on the NSE or BSE site and find net profit, NIM, gross and net NPA, capital adequacy and provision coverage.
- Strip one-offs: look for treasury gains, NSE-related gains, tax refunds, base-year gains and provision write-backs.
- Check funding: compare advances growth with deposit growth and look at the cost of deposits.
- Compare at least four quarters: one quarter is not a track record, and public sector bank profits have moved sharply from one year to the next.
- Read the shareholding pattern: note the government’s stake and any announced capital or share-sale plans.
- Add price last: a bank can be strong and expensive. Valuation needs live prices, which I do not use on this page.
- Think about tax: gains are taxed under the rules in my capital gains tax on shares guide, and dividends under my dividend tax in India guide.
If your question is narrower, see my high-dividend bank stocks page, my bank stocks under Rs 100 page and my PSU banks capital rotation explainer. Each keeps to its own question, so this page does not repeat them.
9. What are the risks of PSU bank stocks in India 2026?
The main risks are thin margins after the repo rate rose to 5.50%, deposits growing slower than loans, profit that leans on one-off gains, higher provisioning at some banks, and asset quality that is still above 2% at three banks.
A second set of risks is in the process. Stock prices can fall even when profit rises, because prices reflect expectations. This page uses no price data, apart from one results-day move for Bank of Maharashtra, so it cannot tell you whether a bank’s results were already reflected in its price. Brokerage ratings were also not used, because a rating is an opinion and not a company fact. Government decisions on capital, mergers or share sales are a further risk that no results table can show.
10. What most people miss about PSU bank stocks
- What stands out: the fastest growers include banks with items that flatter growth, so a ranking by profit growth is not a ranking by quality.
- Easy to miss: the five smaller banks grew about 24.2% against 17.8% for the five largest, but they started from lower profits, and gross NPA at Central Bank is still 2.39%.
- What would change the picture: December-quarter margins after the rate rise, and capital adequacy lines for the six banks where I found none.
- Caution: this page does not say which bank to buy. It shows what each reported and where the data is thin.
Bottom line
The right PSU bank stocks in India 2026 depend on your goal, and the data does not name one winner. In Q2 FY27 all ten public sector banks grew profit and gross NPA fell at every bank with a year-ago figure, while some of the profit growth came from NSE-linked and treasury gains and margins stayed thin. Compare banks on the measure that matches your goal, and read the filings.
Next read: see the sector view in our banking sector outlook 2026.
Part of the Sector Outlook series on PositionalCalls.
PositionalCalls WhatsApp channel
Keep the banking data in one place
- Sector outlook and earnings updates
- RBI decisions and what they mean for banks
- Updates when the next quarter is filed
FAQs on PSU bank stocks in India 2026
What are the best PSU bank stocks in India 2026?
This page does not name them, because PositionalCalls gives no buy or sell calls and the best PSU bank stocks in India 2026 depend on your goal. It compares ten public sector banks on Q2 FY27 profit, NPA, growth and capital, and shows the measures to check for safety, growth and dividends.
Which PSU bank grew profit fastest in Q2 FY27?
Bank of Maharashtra grew net profit fastest among the ten public sector banks, up 41.42% to Rs 2,310 crore. Bank of Baroda followed at 35.8% and Union Bank at 30.3%. Bank of Baroda’s growth includes a treasury gain, so a high growth rate is not the same as a high-quality one.
Which PSU bank had the lowest gross NPA in Q2 FY27?
Among the ten banks, Bank of Maharashtra reported the lowest gross NPA at 1.25%, followed by Canara Bank at 1.33%, SBI at 1.39% and Bank of India at 1.60%. PNB was highest at 2.55%, followed by Union Bank at 2.42% and Central Bank at 2.39%. Definitions vary by source.
Are PSU bank stocks safe for long-term investors?
No share is risk free. PSU bank stocks can fall when margins narrow, provisions rise or the market reprices them. A safety check uses gross and net NPA, slippage and capital adequacy from the filing, across several quarters. I found capital adequacy for only four of ten banks, so verify it before judging safety.
How did PSU banks compare with private banks in Q2 FY27?
The ten public sector banks grew profit about 19.0% as a group against about 15.8% for four large private banks (my calculation), but the public sector NIM of 2.55% to 2.94% was below the private 3.32% to 4.31%. Gross NPA was also higher, at 1.25% to 2.55% against 1.04% to 1.20%.
Which PSU bank has the highest net interest margin?
Of the five public sector banks with a figure, SBI reported the widest NIM at 2.94%, followed by Union Bank at 2.86%, Bank of Baroda at 2.74%, PNB at 2.58% and Canara at 2.55%. I did not find a margin for Indian Bank, Bank of India, Bank of Maharashtra, Central Bank or UCO.
Why does this page not rank PSU bank stocks in India 2026?
A ranking would be a recommendation, which PositionalCalls does not give, and the earlier labels such as safest and best value had no stated method. Rankings by profit growth also mislead, because SBI, Bank of Baroda and Indian Bank each have an item that changes the growth picture. The page shows the evidence so you can apply your own goal.
What is the capital adequacy of public sector banks?
I found it for four of ten banks: Canara Bank 17.19%, Central Bank 17.18%, Bank of Baroda 16.61% and Indian Bank 16.21%, where one source calls the Indian Bank figure Tier 1. Capital adequacy for the other six banks was not found, so read each Q2 filing and compare it with the RBI minimum.
Do PSU bank stocks pay dividends?
Each bank’s board decides its own dividend, and I did not check dividend figures for this page. Look at the declared amount, record date and payout history in each bank’s filings. For tax on dividends and gains, see the dividend tax and capital gains guides linked on this page.
What should I monitor each quarter for PSU bank stocks in India 2026?
Track net profit and its source, NIM, gross and net NPA, slippage ratio, capital adequacy, and advances against deposit growth. For the next update, the December-quarter results will show the first effect of the October rate rise, per secondary reports, on margins and funding costs at public sector banks.
Sources
- PSU Connect: Indian Bank Q2 FY27, 15 October 2026 results; capital adequacy label conflicts with Multibagg.
- PSU Connect: Central Bank of India Q2 FY27, 17 October 2026.
- Free Press Journal: Bank of India Q2 FY27, 23 October 2026.
- Free Press Journal: UCO Bank Q2 FY27, 15 October 2026.
- Business Today: Bank of Maharashtra Q2 FY27, 26 October 2026.
- Geekchamp: Canara Bank Q2 FY27, 27 October 2026; an automated summary, single source.
- Multibagg: Indian Bank Q2 FY27 and guidance, 23 October 2026; an automated summary.
- Multibagg: Union Bank Q2 FY27; an automated summary with internal inconsistencies.
- 5paisa: banking stocks after Q2 FY27, 9 November 2026.
- Free Press Journal (PTI): public sector bank profits, Q2 FY26, 5 November 2025; used for year-ago bases.
- The Week: bank credit grows 17.94%, 30 October 2026; RBI data.
- PositionalCalls: Bank of Baroda Q2 results FY27 (my result post).
- Reserve Bank of India: policy statements and statistics.
- Named, not linked: PSU Watch and Upstox coverage of PNB and SBI, a Cofacto and CompoundingAI summary of Canara Bank, a UCO Bank provisional business update on Sahi, and a PSU Connect headline on Indian Overseas Bank, as read for my banking sector posts, as of 14 November 2026, 4:45 PM IST. No BSE or NSE filing was opened.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive