
Earnings · Commercial Vehicles
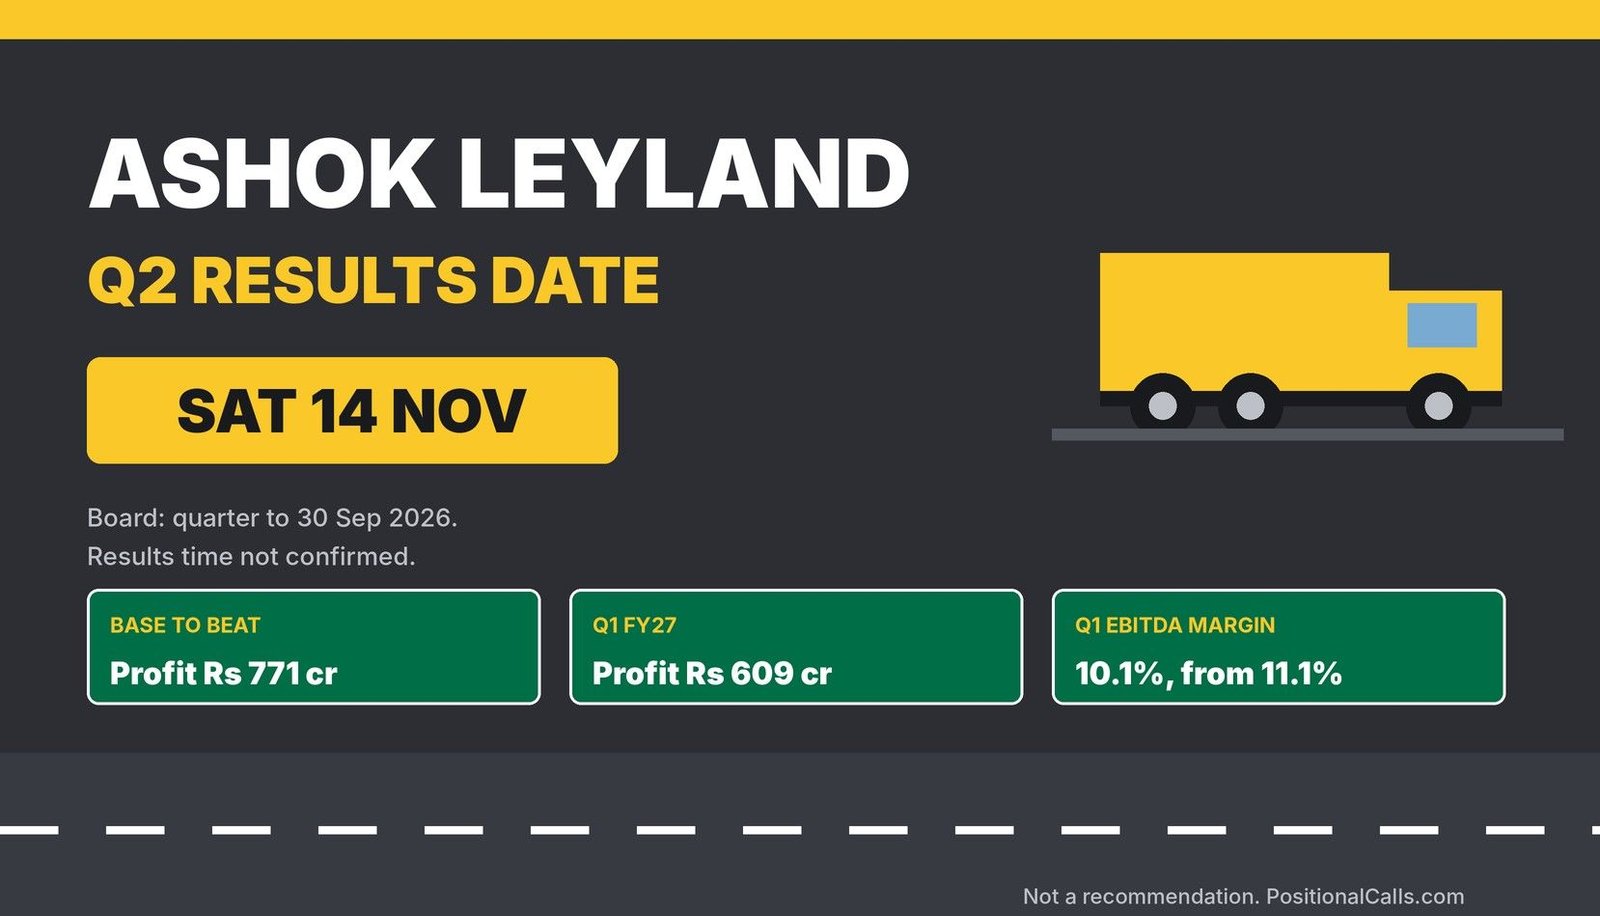
The Ashok Leyland Q2 results date is Saturday, 14 November 2026. Here are the year-ago base, the Q1 FY27 profit and margin, the September truck volumes and the checks for results day.
Quick answer
The Ashok Leyland Q2 results date is Saturday, 14 November 2026, per an Upstox results list, for the quarter and half-year ended 30 September 2026. The base to beat is Q2 FY26 standalone net profit of Rs 771 crore on revenue from operations of Rs 9,588 crore. The results time is not stated.
Latest update (Thursday, 12 November 2026, 1:05 PM IST): Upstox lists Ashok Leyland among 318 companies due to report on Saturday, 14 November, in a list updated on 8 November. I did not find a company notice, a results time, an analyst consensus or published results at the time of writing.
Key takeaways
- Date: Saturday, 14 November 2026, the last day of the results window, per Upstox. I did not open a company notice, so treat the date as reported, not confirmed.
- Base to beat: Q2 FY26 standalone net profit Rs 771 crore on revenue from operations of Rs 9,588.18 crore (+9.34%), per Business Standard.
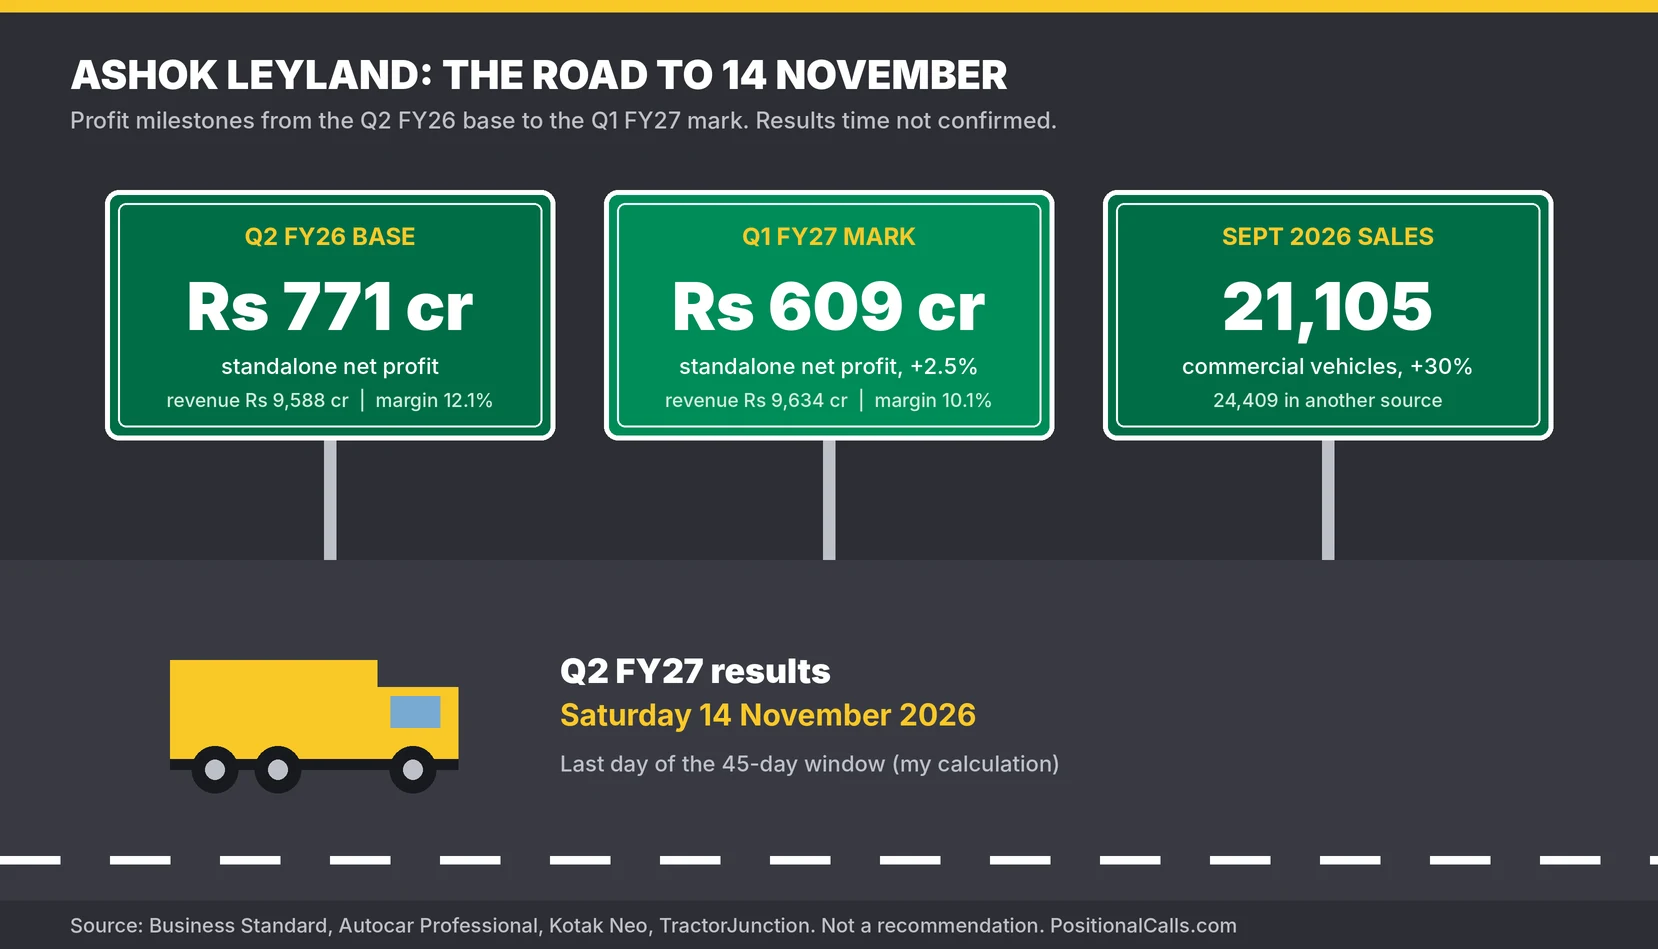
- Nearer mark: Q1 FY27 standalone net profit Rs 609.11 crore (+2.5%) on revenue of Rs 9,634.35 crore (+10.43%), with EBITDA margin 10.1% against 11.1%.
- Margin squeeze: Q1 FY27 EBITDA was flat at Rs 970 crore as raw material cost rose to 71.5% of sales.
- Volumes: September 2026 total commercial vehicle sales rose about 30% to 21,105 units in one source; another source shows 24,409 units and 28%.
- Conflicting bases: Q2 FY26 profit appears as Rs 756 crore, Rs 771 crore and Rs 820 crore across sources; I explain each below.
In plain words: Ashok Leyland is a Hinduja group commercial vehicle maker, mainly trucks, buses and light commercial vehicles. Its standalone results show the vehicle business; consolidated results add subsidiaries such as its finance arm and Switch Mobility.
Data note: Figures are as of 12 November 2026, 1:05 PM IST and are standalone unless stated. They follow Business Standard, Autocar Professional, Kotak Neo, Free Press Journal, HDFC Sky and TractorJunction. I could not open the exchange filings, so quarterly figures are headline-level. Derived numbers are my calculation. I found no analyst consensus for Ashok Leyland Q2.
In this post
When is the Ashok Leyland Q2 results date, and at what time will it be announced?
The Ashok Leyland Q2 results date is Saturday, 14 November 2026, according to an Upstox results list updated on 8 November. The results cover the quarter and half-year ended 30 September 2026. The results time is not stated in that list.
The Upstox list gives no meeting time and no agenda, and it does not mention a dividend. It groups 318 companies on 14 November, including Ashok Leyland, TVS Srichakra and Panacea Biotec, and the list is partial. Companies must report within 45 days of the quarter-end, which makes Saturday, 14 November the legal limit (my calculation), so the Ashok Leyland Q2 results date falls on the last day. Last year the Q2 results came on Wednesday, 12 November 2025, with Business Standard publishing its report at 4:53 pm, so this year’s date is two days later. A Saturday meeting is unusual, which is one more reason to check the exchange notice.
Ashok Leyland Q2 results date: what each source says
| Item | What was reported | Source and date | Status |
|---|---|---|---|
| Board meeting | 14 November 2026 | Upstox, updated 8 Nov | Reported |
| Agenda | Not stated | Upstox | Not stated |
| Results time | Not stated | None found | Not confirmed |
| Last year’s date | 12 November 2025 | Business Standard | Reported |
| Analyst consensus | Not found | None | Not available |
Cite this table: Results date status, as of 12 November 2026, 1:05 PM IST, PositionalCalls.
See the Q2 results hub for other reporters, and Tata Motors PV and Eicher Motors for other vehicle makers.
Why the day matters for vehicle-maker investors
September truck sales rose sharply while Q1 profit grew only 2.5% on a margin squeeze, so the Ashok Leyland Q2 results date shows whether volume growth is reaching profit (my reading, not a forecast).
What is the profit and revenue base Ashok Leyland has to beat in Q2 FY27?
The Q2 FY26 standalone base is net profit of Rs 771 crore against Rs 770.10 crore a year earlier, on revenue from operations of Rs 9,588.18 crore, up 9.34%. EBITDA was Rs 1,162 crore, up 14.25%, at a margin of 12.1% against 11.6%, per Business Standard.
| Q2 FY26 (quarter to 30 Sep 2025) | Q2 FY26 | Q2 FY25 | Change |
|---|---|---|---|
| Revenue from operations | Rs 9,588.18 crore | Rs 8,769 crore (my calculation) | +9.34% |
| Standalone net profit | Rs 771 crore | Rs 770.10 crore | +0.1% (my calculation) |
| EBITDA | Rs 1,162 crore | Rs 1,017 crore | +14.25% |
| EBITDA margin | 12.1% | 11.6% | +0.5 points |
| Net profit margin on revenue | 8.0% | 8.8% (my calculation) | -0.8 points |
| Interim dividend | Rs 1 a share | Not found | Paid by 11 Dec 2025 |
Cite this table: Ashok Leyland Q2 FY26 standalone base per Business Standard; margins calculated by PositionalCalls.
The Rs 1,162 crore EBITDA ties to 12.1% of Rs 9,588 crore (my calculation). The Q2 FY25 revenue of Rs 8,769 crore is my back-calculation from the reported 9.34% growth, so treat it as approximate. The reasons for the flat profit are not given in the pages I opened, beyond a general mention of demand, product premiumisation, network growth and cost optimisation.
Three Q2 FY26 profit figures
| Figure | Value | Source | My reading |
|---|---|---|---|
| Standalone net profit | Rs 771 crore | Business Standard capital market report | Matches Rs 770.10 crore a year earlier; used as the base |
| Net profit | Rs 755.77 crore (+7.1%) | Business Standard results report | Looks like a consolidated or attributable figure; not confirmed |
| Profit after tax | Rs 819.70 crore (+6.9%) | Kotak Neo; Free Press Journal headline | Likely consolidated before minority share; not confirmed |
| Revenue | Rs 10,543.97 crore | Business Standard results report | Does not tie to Rs 9,588 crore; basis unclear |
| Total income | Rs 12,711.75 crore | Kotak Neo | Consolidated, including the finance arm |
Cite this table: Ashok Leyland Q2 FY26 figures compared by PositionalCalls; readings are mine and not confirmed against the filing.
Business Standard’s results report also quotes an EBITDA margin of 12.1%, but Rs 1,162 crore over its Rs 10,544 crore revenue is about 11.0% (my calculation), so that revenue is likely a different basis from the Rs 9,588 crore in its other report. Kotak Neo’s EPS also moves 46% lower year on year while its profit rises, which suggests a restated share count. On results day, compare the same line and the same basis, standalone or consolidated, on both sides.
What did Ashok Leyland report in Q1 FY27, the nearest mark?
In Q1 FY27 Ashok Leyland reported standalone revenue from operations of Rs 9,634.35 crore, up 10.43%, net profit of Rs 609.11 crore, up 2.5%, and EBITDA flat at Rs 970 crore, a margin of 10.1% against 11.1%, per Kotak Neo and Autocar Professional.
| Q1 FY27 (quarter to 30 June 2026) | Q1 FY27 | Q1 FY26 | Change |
|---|---|---|---|
| Revenue from operations | Rs 9,634.35 crore | Rs 8,725 crore | +10.43% |
| Standalone net profit | Rs 609.11 crore | Rs 593.73 crore | +2.5% reported; +2.6% by my calculation |
| EBITDA | Rs 970 crore | Rs 970 crore | Flat |
| EBITDA margin | 10.1% | 11.1% | -100 basis points |
| Other income | Rs 85.1 crore | Not found | +61% |
| Net cash | Rs 2,252 crore | Rs 820 crore (my calculation) | +Rs 1,432 crore |
Cite this table: Ashok Leyland Q1 FY27 per Autocar Professional and Kotak Neo; ties checked by PositionalCalls.
These tie: Rs 970 crore over Rs 9,634.35 crore is 10.1%, and Rs 609.11 crore over Rs 593.73 crore is 2.6% (my calculation). Raw material cost was 71.5% of sales, up 90 basis points on the year. Q1 FY27 net profit of Rs 609.11 crore is 21.0% below the Q2 FY26 base of Rs 771 crore, and Q1 revenue of Rs 9,634.35 crore is 0.5% above Q2 FY26 revenue (my calculation). Those are different quarters, so this is not a growth rate. It shows that Q2 profit would have to rise well above the Q1 level to beat the base. Net cash fell to Rs 2,252 crore from Rs 5,899 crore at the end of March 2026.
Consolidated Q1 FY27 and the Q4 FY26 jump
| Measure | Q1 FY27 | Q1 FY26 | Change |
|---|---|---|---|
| Consolidated revenue | Rs 13,069.59 crore | Rs 11,708.54 crore | +11.62% |
| Consolidated net profit | Rs 667.77 crore | Rs 657.72 crore | +1.52% |
| Profit before tax | Rs 949.72 crore | Rs 891.41 crore | +6.54% |
| Commercial vehicle segment profit | Rs 701.86 crore | Not found | Not available |
| Financial services segment profit | Rs 171.87 crore | Not found | Not available |
| Earnings per share | Rs 1.05 | Rs 1.04 | Marginally higher |
Cite this table: Ashok Leyland Q1 FY27 consolidated per Free Press Journal; segment lines before interest and tax.
Standalone Q4 FY26 profit was Rs 1,404.72 crore per Kotak Neo, which is why Q1 FY27 shows a 56.6% fall from the previous quarter (my calculation). Autocar Professional gives Q4 consolidated profit of Rs 1,381 crore and notes a one-time charge of Rs 384 crore for the new Labour Codes in FY26. Quarter-on-quarter comparisons are therefore less useful than the year-on-year ones.
What do the monthly volumes say about Ashok Leyland Q2 FY27?
Ashok Leyland reported September 2026 total commercial vehicle sales of 21,105 units, up 30.17%, with domestic medium and heavy trucks up 44%, per TractorJunction. HDFC Sky, from a PTI feed, shows 24,409 units, up 28%. The two do not match.
| September 2026 category | Sept 2026 | Sept 2025 | Change |
|---|---|---|---|
| Total commercial vehicles | 21,105 | 16,213 | +30.17% |
| Domestic commercial vehicles | 20,135 | 15,572 | +29.31% |
| Domestic M&HCV trucks | 12,724 | 8,862 | +44% |
| Domestic LCVs | 7,411 | 6,710 | +10% |
| Exports | 970 | 641 | +51.33% |
Cite this table: Ashok Leyland September 2026 sales per TractorJunction; gross M&HCV 13,244 plus gross LCV 7,861 ties to 21,105.
HDFC Sky shows trucks and buses of 16,188 units, up 37%, and LCVs of 7,861, up 12%, but these add to 24,049, not the 24,409 it quotes, and 24,409 against 18,813 is about 30%, not 28% (my calculation). The higher figure probably includes buses and other categories, which I could not confirm. TractorJunction’s August 2026 headline shows combined sales up 43% and truck sales up 60%, but I read only the headline. I did not find a total for the September quarter, so I cannot say what Q2 FY27 volumes were. For the base, Q2 FY26 volumes were 26,307 domestic M&HCV, 17,697 domestic LCV and 4,784 exports, a total of 48,788 units (my calculation from Business Standard).
PositionalCalls WhatsApp channel
The results, then the margin check
- The revenue, profit and margin lines as soon as they appear
- Volumes and costs explained
- Links to the updated page
What has Ashok Leyland said about dividends, investments and costs?
Ashok Leyland declared an interim dividend of Rs 1 a share with Q2 FY26 and a second interim of Rs 2.50 for FY26, a total of Rs 3.50 and no final dividend, per Autocar Professional. In Q1 FY27 it approved investments in Optare and Hinduja Housing Finance.
| Item | Reported | Comment | Source |
|---|---|---|---|
| Q2 FY26 interim dividend | Rs 1 a share, paid by 11 Dec 2025 | Declared with the Q2 FY26 results | Business Standard |
| Second interim dividend FY26 | Rs 2.50 a share; record date 3 June 2026 | Total FY26 Rs 3.50; no final dividend | Autocar Professional |
| Optare Plc (UK) | Up to 25 million pounds | Board approval with Q1 FY27 results | Autocar Professional |
| Hinduja Housing Finance | Up to Rs 500 crore | Board approval with Q1 FY27 results | Autocar Professional |
| Cost outlook | Material costs a concern; pricing, savings and mix being pursued | Management comment on Q1 | Autocar Professional |
Cite this table: Ashok Leyland corporate items as reported; not verified against filings.
Autocar Professional gives no FY27 guidance. Of these items, the dividend history is the one most relevant to the date: Ashok Leyland paid an interim dividend alongside Q2 results last year, but none is mentioned for 14 November, so check the filing. Management’s comment on rising material costs matches the 100 basis point margin fall in Q1.
What drives Ashok Leyland’s Q2 numbers: volumes, margin and other income?
Four lines drive the quarter: truck volumes, price realisation against raw material cost, other income and the mix of buses, defence and exports. In Q1 FY27 EBITDA margin fell to 10.1% while volume rose 10.2%.
| Driver | Q2 FY26 | Q1 FY27 | What to read on results day |
|---|---|---|---|
| Revenue from operations | Rs 9,588 crore | Rs 9,634 crore | Whether volume growth shows up |
| Net profit | Rs 771 crore | Rs 609 crore | Level against both marks |
| EBITDA margin | 12.1% | 10.1% | Cost pass-through |
| Total CV volume | 48,788 units (my calculation) | 48,763 units | Q2 FY27 total volume |
| Other income | Not found | Rs 85.1 crore | Share in profit |
Cite this table: Ashok Leyland driver checklist, PositionalCalls; figures from the sources above.
Items to check in the filing
- Revenue from operations against Rs 9,588 crore and Rs 9,634 crore.
- Standalone net profit against Rs 771 crore and Rs 609.11 crore.
- EBITDA and margin against 12.1% and 10.1%.
- Other income and any exceptional item.
- Any dividend announcement and the consolidated profit line.
A note on the numbers
Total commercial vehicle volume was 48,763 units in Q1 FY27 against 48,788 in Q2 FY26, a gap of 0.1% (my calculation, with the Q2 FY26 total built from three categories), so the Q2 FY27 volume has to rise on the Q1 level to lift revenue above the base.
What would different Ashok Leyland Q2 outcomes look like in numbers?
If Q2 revenue from operations grows 10% on the Rs 9,588 crore base, it would be about Rs 10,547 crore; at the Q1 FY27 net margin of 6.3%, profit would be about Rs 664.5 crore. These are arithmetic illustrations, not forecasts.
| Revenue growth on Q2 FY26 | Revenue, Rs crore | Profit at 6.3% margin | Profit at 8.0% margin |
|---|---|---|---|
| +10% | 10,547.0 | 664.5 | 843.8 |
| +15% | 11,026.4 | 694.7 | 882.1 |
| +20% | 11,505.8 | 724.9 | 920.5 |
| +25% | 11,985.2 | 755.1 | 958.8 |
Cite this table: Ashok Leyland Q2 FY27 arithmetic, my calculation. Base: Q2 FY26 revenue from operations Rs 9,588.18 crore. Margins are Q1 FY27 and Q2 FY26 standalone net margins. Not forecasts.
| Net profit level, Rs crore | Change vs Q2 FY26 base (771) | Change vs Q1 FY27 (609.11) |
|---|---|---|
| 600 | -22.2% | -1.5% |
| 700 | -9.2% | +14.9% |
| 771 | 0.0% | +26.6% |
| 850 | +10.2% | +39.5% |
| 950 | +23.2% | +56.0% |
Cite this table: Ashok Leyland Q2 FY27 profit arithmetic, my calculation. Levels are illustrations, not forecasts.
Three worked examples
Example 1, margin held at Q1. Revenue up 10% to about Rs 10,547 crore at a 6.3% margin gives profit of about Rs 664.5 crore, 13.8% below the base of Rs 771 crore (my calculation).
Example 2, margin back at last year’s level. Revenue up 20% to about Rs 11,506 crore at 8.0% gives about Rs 920.5 crore, 19.4% above the base.
Example 3, profit level. A profit of Rs 609.11 crore, equal to Q1, would be 21.0% below the Q2 FY26 base (my calculation).
How do I read the Ashok Leyland results on results day?
On results day read, in this order: revenue from operations against Rs 9,588 crore and Rs 9,634 crore, standalone net profit against Rs 771 crore and Rs 609.11 crore, then EBITDA margin, other income and any dividend.
| Order | Line to read | Mark to compare | Why it comes first |
|---|---|---|---|
| 1 | Revenue from operations | Rs 9,588 crore; Rs 9,634 crore | Top-line trend |
| 2 | Standalone net profit | Rs 771 crore; Rs 609.11 crore | The headline |
| 3 | EBITDA margin | 12.1%; 10.1% | Cost pass-through |
| 4 | Other income | Rs 85.1 crore in Q1 | Quality of profit |
| 5 | Consolidated profit | Rs 667.77 crore in Q1 | Finance arm and subsidiaries |
| 6 | Dividend | None mentioned | Check the filing |
Cite this table: Ashok Leyland results-day reading order, PositionalCalls.
On the Ashok Leyland Q2 results date, compare like with like: use standalone against standalone and consolidated against consolidated, and say which one a headline uses.
How do I read the Ashok Leyland filing and avoid fake alerts?
On results day, open the NSE or BSE announcement for Ashok Leyland Limited, not a link in a message, and read the standalone results table first. Treat any tip that asks for an OTP, payment or login as fake.
- Open the exchange announcement page for Ashok Leyland Limited.
- Read the unaudited standalone and consolidated results for the quarter ended 30 September 2026.
- Note revenue, total expenses and the profit lines.
- Compare with Rs 9,588 crore, Rs 1,162 crore EBITDA and Rs 771 crore.
- Read the other income line and any exceptional item.
- Check the segment note and any dividend announcement.
PositionalCalls is not SEBI-registered, gives no buy or sell calls and never asks for payment. Nothing here is investment advice.
What do most people miss about the Ashok Leyland Q2 results?
Around the Ashok Leyland Q2 results date, most readers miss that the year-ago profit has three values, that monthly sales sources disagree, that Q1 profit is below the Q2 base and that no consensus was found.
Analyst’s note. What stands out: Q1 FY27 volume rose 10.2% yet EBITDA stayed flat at Rs 970 crore, so growth did not reach the margin (my reading). What is easy to miss: Q1 profit of Rs 609.11 crore is 21.0% below the Q2 FY26 base, so the base is demanding. What would change the view: a margin recovery towards the 12.1% of last year. Caution: scenarios are arithmetic, not forecasts. Reader action: read revenue, standalone profit and margin first.
A last point on sources. Several figures here come from news reports and aggregators, and these can differ from the filing: Q2 FY26 profit is Rs 771 crore in one place and Rs 820 crore in another, and September sales have two totals. Before using any number in a decision, open the exchange filing, check the definition of each line and note the date of the report. I list each source with its date below so the comparison can be repeated.
Another habit worth keeping is to write down the three or four numbers you care about before the filing appears, such as revenue, standalone profit and EBITDA margin, so you can read the result against your own checklist and not against the headline. Headlines tend to pick the largest percentage change, which can look dramatic even when the rupee change is modest. The rupee figure and the base it is measured against tell the fuller story.
If a figure on this page changes after the filing, the Updated date at the top will change too, and the Latest update line will say what moved. Previews like this one are converted into results pages once the numbers are out, so the comparison tables are kept and the year-ago base stays visible next to the new figures.
Vehicle makers report quarters shaped by monthly dispatches, input costs and the product mix of trucks, buses and light vehicles, so a strong sales month can sit beside a thin margin. Reading volume, margin and other income together gives a steadier picture than any one headline number alone.
Bottom line
The Ashok Leyland Q2 results date is 14 November 2026. The base is Rs 771 crore profit on Rs 9,588 crore revenue, and Q1 FY27 profit was Rs 609.11 crore. I will update this page with the actual numbers. See our stock market coverage.
PositionalCalls WhatsApp channel
Never miss a results update
- Results dates and dividend dates
- Numbers explained without tips or targets
- Updated posts as they go live
Ashok Leyland Q2 results date: frequently asked questions
When is the Ashok Leyland Q2 results date?
The Ashok Leyland Q2 results date is Saturday, 14 November 2026, per an Upstox results list updated on 8 November. The results cover the quarter and half-year ended 30 September 2026. The results time is not stated, so check the exchange announcement. Last year it reported on 12 November.
What was Ashok Leyland profit in Q2 FY26?
Ashok Leyland reported Q2 FY26 standalone net profit of Rs 771 crore against Rs 770.10 crore, on revenue from operations of Rs 9,588.18 crore, up 9.34%, per Business Standard. EBITDA was Rs 1,162 crore at 12.1%. This is the base for the Ashok Leyland Q2 results date comparison.
What did Ashok Leyland report in Q1 FY27?
Ashok Leyland reported Q1 FY27 standalone revenue from operations of Rs 9,634.35 crore, up 10.43%, and net profit of Rs 609.11 crore, up 2.5%, with EBITDA flat at Rs 970 crore and a 10.1% margin, per Kotak Neo and Autocar Professional. Volume was a record 48,763 units.
Why do Ashok Leyland Q2 FY26 profit figures differ?
Q2 FY26 shows Rs 771 crore standalone in one report, Rs 755.77 crore in another and Rs 819.70 crore at Kotak Neo and Free Press Journal. The last two look like consolidated or attributable measures, which I could not confirm. Check the filing before the Ashok Leyland Q2 results date comparison.
How many vehicles did Ashok Leyland sell in September 2026?
TractorJunction shows total September 2026 sales of 21,105 units, up 30.17%, with domestic M&HCV trucks up 44%. HDFC Sky, from a PTI feed, shows 24,409 units, up 28%, and its segments do not add up. I did not find an official figure, so check the company release.
Has Ashok Leyland paid a dividend this year?
Ashok Leyland declared an interim dividend of Rs 1 a share with its Q2 FY26 results, paid by 11 December 2025, and a second interim of Rs 2.50 with record date 3 June 2026, a total of Rs 3.50. It had no final dividend for FY26, per Business Standard and Autocar Professional.
Will Ashok Leyland declare a dividend on 14 November?
No dividend is mentioned in the sources I found for the 14 November meeting, which cover the Q2 and H1 results. The board could still announce one, as it did with the Q2 FY26 results, so check the exchange announcement after the Ashok Leyland Q2 results date.
Is there an analyst estimate for Ashok Leyland Q2?
I did not find an analyst consensus for Ashok Leyland Q2 FY27 in the sources I read, so this page shows only the year-ago base, Q1 FY27 and arithmetic scenarios. Check the exchange filing and broker notes after the board meeting. The scenarios are not forecasts.
Why did Ashok Leyland margin fall in Q1 FY27?
Autocar Professional shows EBITDA flat at Rs 970 crore, a margin of 10.1% against 11.1%, with raw material cost at 71.5% of sales, up 90 basis points. Management called rising material costs a concern and said it is pursuing better price realisation and cost savings.
Is this financial advice about Ashok Leyland?
No. This page is not investment advice, a target or a recommendation, and PositionalCalls is not SEBI-registered. It reports company figures and sources with dates, and labels my calculations. Read the exchange filing and consult a registered adviser before any decision.
Sources
- NSE India: corporate announcements: where the results will appear.
- BSE India: corporate announcements: the results filing.
- Upstox: upcoming Q2 FY27 results list, updated 8 November 2026.
- Autocar Professional: Ashok Leyland Q1 FY27, August 2026.
- Kotak Neo: Ashok Leyland Q1 FY27 results, 2026.
- Free Press Journal: Ashok Leyland Q1 consolidated, 2026.
- Business Standard: Ashok Leyland Q2 FY26, 12 November 2025.
- Business Standard: Ashok Leyland Q2 PAT Rs 771 crore, 12 November 2025.
- Kotak Neo: Ashok Leyland Q2 FY26 results, 2025.
- TractorJunction: Ashok Leyland September 2026 sales, October 2026.
- HDFC Sky: Ashok Leyland September sales, 1 October 2026.
- Autocar Professional: Ashok Leyland Q4 FY26, May 2026.
Disclosure: PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent research and education site founded by Shubham Chaudhary. Nothing here is a recommendation, target or investment advice. How I researched this: for the Ashok Leyland Q2 results date I read Business Standard, Autocar Professional, Kotak Neo, Free Press Journal, HDFC Sky and TractorJunction, noted where sources differ, and marked every derived number as my calculation. I did not open any company filing or exchange document. Figures are as of 12 November 2026, 1:05 PM IST.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive