
Results analysis · Auto
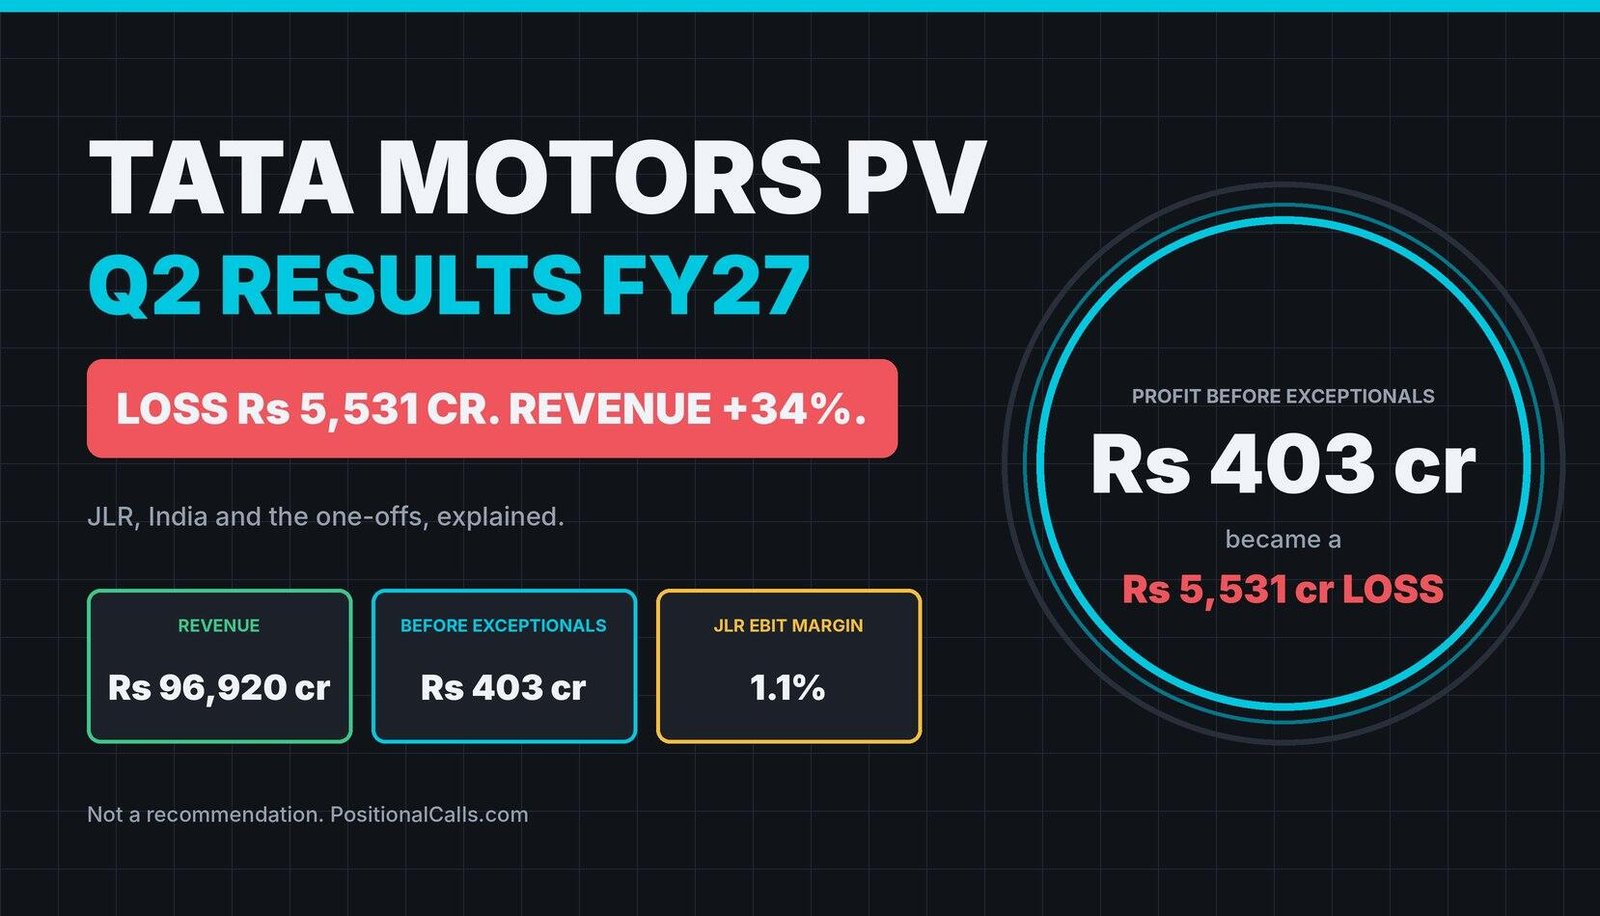
Looking for the Tata Motors PV Q2 results FY27? TMPV reported on 13 November 2026: record revenue of Rs 96,920 crore, up 34%, and a consolidated net loss of Rs 5,531 crore. This page separates the loss from the operating result, JLR from India, and the year-ago profit that is not a like-for-like base.
Quick answer
Tata Motors PV Q2 results FY27: TMPV reported a consolidated net loss of Rs 5,531 crore on revenue of Rs 96,920 crore, up 34%. Profit before exceptional items was Rs 403 crore, so the loss sits below that line. JLR revenue rose 20.3% to £5.9 billion, but its free cash flow was negative.
Latest update (Friday, 13 November 2026, 6:30 PM IST): Tata Motors Passenger Vehicles reported Q2 FY27 on Friday, 13 November 2026; Upstox listed revenue at 4:25 PM IST and the loss at 4:45 PM IST, after the NSE close. Business Upturn, Lapaas Voice, Investywise and Multibagg carried the figures. I did not find the exceptional-item amount, the tax line or a share price after the results, and I have not opened the exchange filing.
Key takeaways
- Headline: consolidated net loss of Rs 5,531 crore on revenue of Rs 96,920 crore, up 34% from Rs 72,349 crore (Business Upturn, Upstox, Lapaas Voice).
- Operating result: profit before exceptional items was Rs 403 crore, against about minus Rs 5,462 crore a year ago; EBITDA margin was 6.2% and EBIT margin 1.1% (Upstox, Investywise).
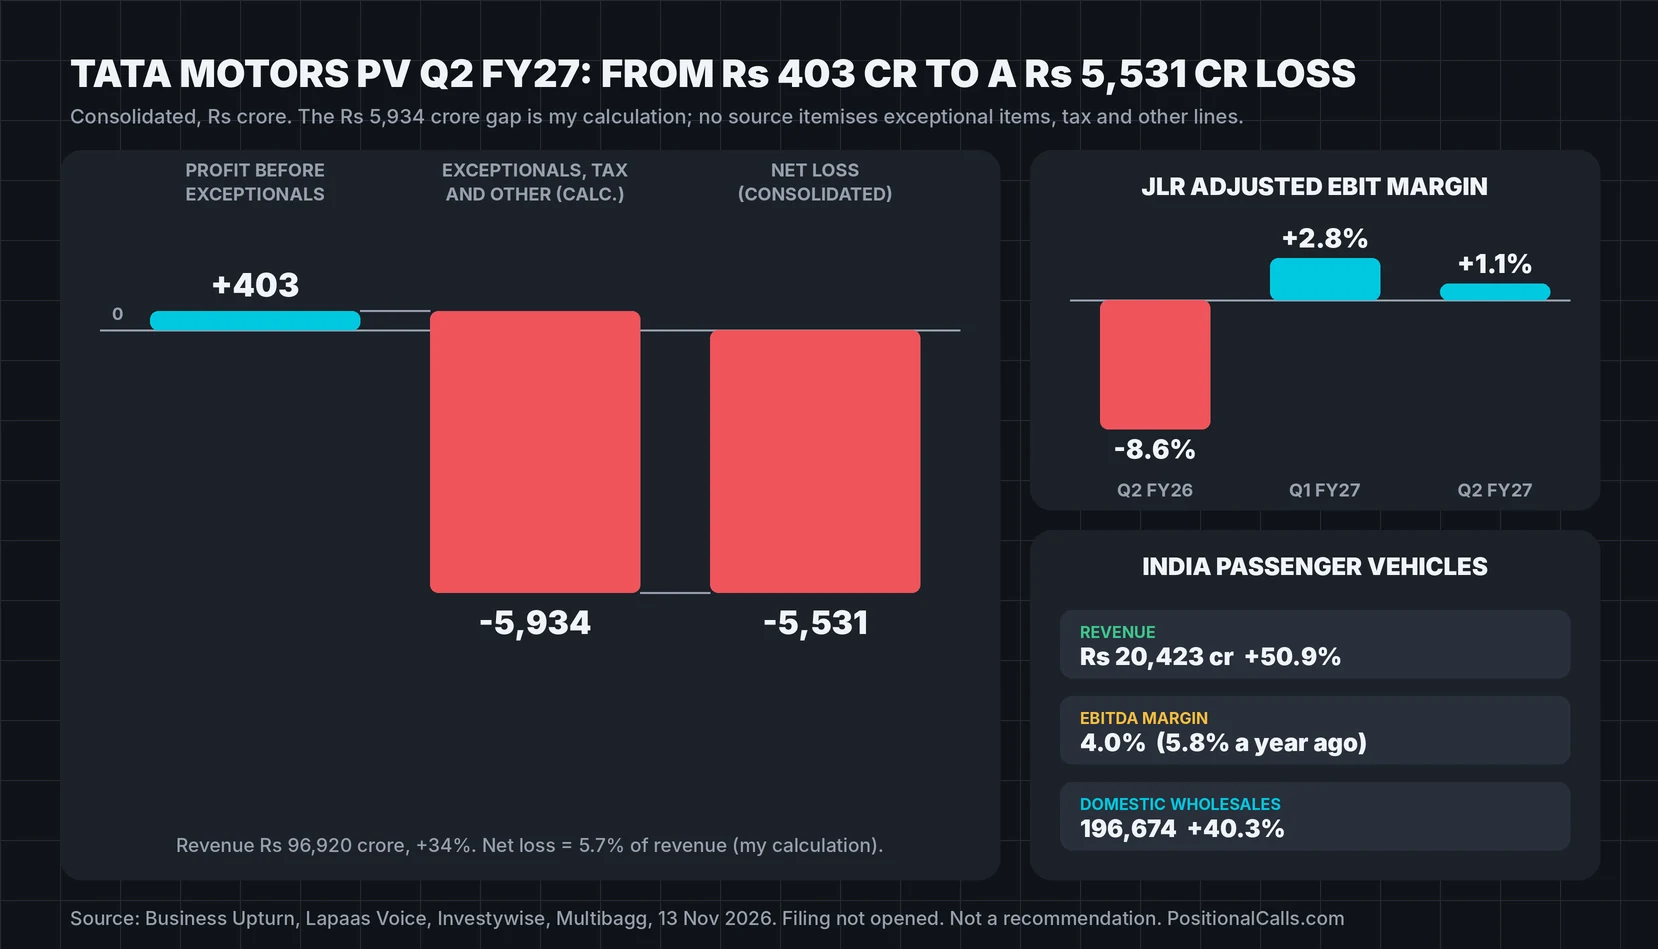
- The gap: Rs 403 crore of profit before exceptional items became a Rs 5,531 crore loss, so about Rs 5,934 crore sits in exceptional items, tax and other lines that no source itemises (my calculation).
- JLR: revenue £5.9 billion, up 20.3%; EBIT margin 1.1% against 2.8% in June; free cash flow about minus £540 million; £530 million of exceptional items; FY27 margin guidance cut to 2-3% (Multibagg).
- India: passenger vehicle revenue of Rs 20,423 crore, up 50.9%, a record, with EBITDA margin down 180 basis points to 4.0% (Investywise).
- Conflicts: EBITDA appears as Rs 4,866 crore and as about Rs 6,009 crore, and the year-ago profit of Rs 76,170 crore is not a like-for-like base. Filing not opened.
In plain words: Tata Motors Passenger Vehicles owns Jaguar Land Rover and Tata’s car business in India. Group revenue was the highest on record, but one-off charges, mainly in JLR, and cash outflows turned the quarter into a loss. Last year’s reported profit was inflated by a non-cash gain, so the two years cannot be compared directly.
Data note: Figures are as of 13 November 2026, 6:30 PM IST and are consolidated unless stated, for the quarter to 30 September 2026. Headline figures come from Business Upturn, Lapaas Voice and the Upstox live blog; segment lines from Investywise and Multibagg (an automated summary, with an AI disclaimer). Derived numbers are my calculation. Where sources differ I show both.
In this post
- What did TMPV report?
- Why do the sources differ?
- Which Tata Motors is this?
- From Rs 403 crore to the loss
- The year-ago base problem
- What did JLR report?
- What did India report?
- Cash, debt and guidance
- What did the preview say?
- What the reports do not show
- What does the arithmetic show?
- How to read the next results
- How to read the filing
- What most people miss
- FAQs
- Sources
What did Tata Motors PV report in the Tata Motors PV Q2 results FY27?
Tata Motors Passenger Vehicles reported a consolidated net loss of Rs 5,531 crore for the quarter to 30 September 2026 on revenue of Rs 96,920 crore, up 34% from Rs 72,349 crore. Profit before exceptional items was Rs 403 crore, so the loss comes from items below the operating line.
The results came on Friday, 13 November 2026, after the NSE’s regular 3:30 PM close, so the first trading reaction falls on Monday, 16 November (my reading of the timing). Revenue was the highest the company has reported, and the India passenger vehicle business also posted its highest quarterly revenue. The loss is the story, and the sections below take it apart.
| Tata Motors PV Q2 FY27 (consolidated) | Q2 FY27 | Q2 FY26 | Change |
|---|---|---|---|
| Revenue | Rs 96,920 crore | Rs 72,349 crore | +34.0% (my calculation: +33.96%) |
| Net profit or loss | Loss of Rs 5,531 crore | Profit of Rs 76,170 crore (includes a non-cash gain) | Not like for like |
| Profit before exceptional items | Rs 403 crore | About minus Rs 5,462 crore (my calculation) | Up Rs 5,865 crore (Investywise) |
| EBITDA margin | 6.2% | About minus 0.1% (my calculation) | +630 bps (Upstox, Investywise) |
| EBIT margin | 1.1% | About minus 6.8% | +790 bps (Upstox, Investywise) |
| Free cash flow | Minus Rs 6,300 crore | Not found | Investywise |
Cite this table: Tata Motors PV Q2 FY27 per Business Upturn, Lapaas Voice, Upstox and Investywise; lines marked my calculation were calculated by PositionalCalls.
These tie where I can test them. Rs 96,920 crore over Rs 72,349 crore is 33.96%. A profit before exceptional items of Rs 403 crore, up Rs 5,865 crore, implies a year-ago figure of about minus Rs 5,462 crore (my calculation), which matches the preview. The net loss is 5.7% of revenue (my calculation). The quarter therefore shows two things at once: an operating result that moved to a small profit and a bottom line that is deeply negative.
Why do the sources show different numbers for the Tata Motors PV result?
Sources agree on revenue, the loss and the margin direction, but EBITDA appears as Rs 4,866 crore (Business Upturn, margin about 5%) and as about Rs 6,009 crore (Investywise and Upstox, margin 6.2%), and the year-ago profit is not a like-for-like base. Both are shown below.
| Item | Figure A | Figure B | My reading |
|---|---|---|---|
| EBITDA | Rs 4,866 crore, about 5%, against minus Rs 1,404 crore (Business Upturn) | 6.2% margin, +630 bps (Upstox, Investywise); about Rs 6,009 crore (my calculation) | Different definitions; a gap of about Rs 1,143 crore |
| Year-ago profit | Rs 76,170 crore (Business Upturn, Reuters via Lapaas) | About minus Rs 6,400 crore excluding a non-cash gain (my preview calculation) | Reported year-ago profit includes a one-time gain |
| Loss basis | Consolidated net loss of Rs 5,531 crore | Whether it is attributable to owners is not stated (Lapaas) | Filing will show the split |
| JLR wholesales | 82,500, +24.7% (Multibagg) | 82,400, +24.5% (my preview) | Rounding or a revision |
| EBIT margin 1.1% | Consolidated (Upstox, Investywise) | JLR adjusted EBIT (Multibagg) | Both read 1.1%; I treat them as separate figures |
| JLR FY27 free cash outflow | £125 crore, about £1.25 billion (Multibagg) | H1 outflow already about £1.54 billion (my sum of Q1 and Q2) | Does not fit; unit or period error possible |
Cite this table: Tata Motors PV Q2 FY27 conflicts across sources, PositionalCalls, as of 13 November 2026, 6:30 PM IST.
Multibagg writes JLR amounts in “£ crore”; a crore is ten million, so £589.4 crore is £5,894 million, which ties to Investywise’s £5,894 million. That reading also ties year-ago figures to my preview (for example minus £791 million free cash flow), so I use it throughout, but I did not open the JLR release and treat the guidance numbers with extra care.
Which Tata Motors is this, and how does it differ from the commercial vehicle result?
This is Tata Motors Passenger Vehicles Limited (TMPV), which holds Jaguar Land Rover and Tata’s India passenger car and EV business. Tata Motors Limited, the commercial vehicle company, reported on 23 October 2026 and is a separate entity.
| Entity | Business | Q2 FY27 result | Where on this site |
|---|---|---|---|
| Tata Motors Passenger Vehicles (TMPV) | JLR, Tata passenger cars and EVs in India | Loss of Rs 5,531 crore on revenue of Rs 96,920 crore (13 November) | This page |
| Tata Motors Limited (commercial vehicles) | Trucks and buses | Profit of about Rs 1,253 crore on revenue of Rs 25,338 crore (23 October) | Tata Motors Q2 results FY27 |
Cite this table: Tata Motors entities after the demerger, PositionalCalls, as of 13 November 2026, 6:30 PM IST; the commercial vehicle figures are from my earlier post.
Headlines that say only “Tata Motors” can mean either. The names, the revenue scale and the date tell them apart: Rs 96,920 crore is the passenger vehicle group, and Rs 25,338 crore is the commercial vehicle company.
How does a profit before exceptional items of Rs 403 crore become a loss in the Tata Motors PV Q2 results FY27?
Profit before exceptional items was Rs 403 crore and the net loss was Rs 5,531 crore, a gap of Rs 5,934 crore (my calculation). No source gives the exceptional-item total, the tax line or the minority share, but JLR alone reports about £530 million of exceptional items.
| Step (consolidated) | Rs crore | Source or check |
|---|---|---|
| Profit before exceptional items | 403 | Investywise (“PBT bei”) |
| Net loss | -5,531 | Business Upturn, Lapaas Voice, Upstox |
| Gap between the two | 5,934 | My calculation: 403 + 5,531 |
| JLR exceptional items | £530 million | Multibagg: restructuring, employee separation, asset write-downs; rupee value not found |
| Exceptional items, total | Not found | No source gives it |
| Tax and minority share | Not found | No source gives them |
Cite this table: Tata Motors PV Q2 FY27 bridge, PositionalCalls, as of 13 November 2026, 6:30 PM IST; implied lines are my calculation.
The gap cannot be split from the pages I read. If JLR’s £530 million of exceptional items were converted to rupees, it would explain a large part of Rs 5,934 crore, but I did not find the exchange rate used, so I do not convert it (my reading, unconfirmed). Storyboard18’s headline says exceptional costs drove the loss; the page did not load, so I cite it as headline only. Tax and minority lines could move the figure either way.
Why is last year’s Rs 76,170 crore profit not a base for Q2 FY27?
The Rs 76,170 crore year-ago profit was inflated by a non-cash gain linked to the demerger, per Autocar Professional and Reuters via Lapaas Voice. It is larger than that quarter’s revenue of Rs 72,349 crore, so a year-on-year comparison with the Rs 5,531 crore loss misleads.
| Measure | Q2 FY27 | Q2 FY26 | Reading |
|---|---|---|---|
| Reported net result | Loss of Rs 5,531 crore | Profit of Rs 76,170 crore | Swing of Rs 81,701 crore, which Business Upturn cites; not meaningful |
| Net result excluding the gain (my preview calculation) | Loss of Rs 5,531 crore | About minus Rs 6,400 crore | The loss is about Rs 870 crore smaller on this basis (my calculation) |
| Profit before exceptional items | Rs 403 crore | About minus Rs 5,462 crore | The cleanest like-for-like line |
| Revenue | Rs 96,920 crore | Rs 72,349 crore | +34.0% |
Cite this table: Tata Motors PV year-ago base, PositionalCalls, as of 13 November 2026, 6:30 PM IST; the notional gain of about Rs 82,600 crore is from my preview and was not re-verified.
The ex-gain figure of about minus Rs 6,400 crore is my calculation from the preview’s numbers (Rs 76,170 crore less a gain of about Rs 82,600 crore), and I did not re-open the year-ago filing. The safe comparisons are revenue, profit before exceptional items and the margins. Read the result against those, and treat any headline about a Rs 81,701 crore “fall in profit” as a base effect.
What did JLR report in Q2 FY27?
JLR revenue rose 20.3% to £5.9 billion, wholesales rose 24.7% to 82,500, but retail fell 7.5% to 79,000, the adjusted EBIT margin was 1.1% against 2.8% in June, and free cash flow was about minus £540 million.
| JLR (as reported) | Q2 FY27 | Q1 FY27 | Q2 FY26 |
|---|---|---|---|
| Revenue | £5,894 million | £5,973 million | £4,900 million |
| Revenue growth | +20.3% on the year; -1.3% on June | Not found | Not found |
| Adjusted EBIT margin | 1.1% | 2.8% | -8.6% |
| Adjusted EBITDA margin | 6.6% | 8.1% | -1.6% |
| Profit before exceptional items | £6 million | £109 million | -£485 million |
| Free cash flow | -£540 million | -£998 million | -£791 million |
| Wholesales | 82,500 (+24.7%) | Not found | Not found |
| Retail sales | 79,000 (-7.5%) | Not found | 85,371 |
Cite this table: JLR Q2 FY27 per Multibagg and Investywise (units converted from crore as explained above); year-ago figures tie to my preview.
Wholesales exceeded retail by about 3,500 units (my calculation), which can mean stock is building in the channel; no source says so. Multibagg’s profit bridge from June to September gives volume and mix as minus 7.7, net pricing minus 3.3, foreign exchange and commodities minus 1.8, and contribution costs plus 2.5 including a 3.0 warranty benefit; the unit of those lines is not stated. The group EBIT margin recovered from last year mainly because last year carried the JLR cyber incident (Investywise), so the year-on-year change reads better than the sequential one.
PositionalCalls WhatsApp channel
The loss, then the layers
- The Tata Motors PV numbers as they appear
- Exceptional items explained
- Links to updated posts
What did the India passenger vehicle business report?
India passenger vehicle revenue rose 50.9% to a record Rs 20,423 crore, with EBITDA margin down 180 basis points to 4.0%, EBIT margin at minus 0.3% and profit before exceptional items at breakeven. Domestic wholesales were 196,674, up 40.3%.
| India passenger vehicles | Q2 FY27 | Q2 FY26 | Change |
|---|---|---|---|
| Revenue | Rs 20,423 crore | About Rs 13,500 crore | +50.9% (Investywise) |
| EBITDA margin | 4.0% | 5.8% | -180 bps |
| EBIT margin | -0.3% | 0.2% | -50 bps |
| Profit before exceptional items | About breakeven | Not found | Investywise |
| Domestic wholesales | 196,674 | 140,189 | +40.3% (my preview data) |
| EV volume | 47,150 (about 24% of domestic, my calculation) | About 24,800 | +90% (CEO, Investywise) |
Cite this table: India passenger vehicle lines per Investywise and my preview; the year-ago EV figure is derived from the reported 90% rise.
Volume and revenue grew strongly and margin fell: higher volume did not lift the profit margin, which the company attributes in outlook language to cost control and calibrated pricing still to come (Investywise). India is about 21% of group revenue, with JLR making up most of the rest (rough, my calculation: Rs 20,423 crore of Rs 96,920 crore, ignoring other lines and eliminations).
What do cash, debt and JLR guidance show in the Tata Motors PV Q2 results FY27?
Group free cash flow was minus Rs 6,300 crore and net debt Rs 50,800 crore at 30 September. JLR cut its FY27 EBIT margin guidance to 2-3% and says it expects a free cash outflow; the figure given, £125 crore, conflicts with H1 outflows and needs the JLR release.
| Item | Reading | Source and caution |
|---|---|---|
| Group free cash flow, Q2 | -Rs 6,300 crore | Investywise |
| Group net debt, 30 September 2026 | Rs 50,800 crore | Investywise; year-ago net automotive debt was about Rs 20,100 crore in my preview, and the basis may differ |
| JLR liquidity | About £6.0 billion | Multibagg; cash £1.8 billion plus undrawn facilities and a new £1.0 billion term loan |
| JLR FY27 EBIT margin guidance | 2-3% | Multibagg; the June guide was about 4% in my preview |
| JLR FY27 free cash outflow | £125 crore (about £1.25 billion) | Conflicts with H1 outflow of about £1.54 billion |
| JLR investment | About £3.4 billion for FY27; £1.77 billion spent in H1 | Multibagg; £300 million below plan |
Cite this table: Tata Motors PV cash, debt and guidance per Investywise and Multibagg, as of 13 November 2026, 6:30 PM IST; not checked against the filing.
The guidance conflict matters: an outflow of £1.25 billion for the year cannot follow an H1 outflow of £1.54 billion unless cash comes back in H2, so either the figure is for a different period or it is mis-stated (my reading). Do not rely on it until the JLR release is read. Management’s own words, per Investywise, list geopolitical volatility, luxury demand, the pace of EV adoption and commodity costs as the things to watch; no numeric targets were given for the group.
How did the Tata Motors PV Q2 results FY27 compare with the preview?
The preview set Q2 FY26 revenue at Rs 72,349 crore, JLR free cash flow at minus £791 million, India margins near 5.8% EBITDA and found no analyst estimate. Revenue beat the base by 34%; the loss was not anticipated by any estimate, because none was found.
| Preview mark | Preview value | Result | Comparison |
|---|---|---|---|
| Q2 FY26 revenue | Rs 72,349 crore | Rs 96,920 crore | +34.0% |
| Q2 FY26 JLR EBIT margin | -8.6% | 1.1% | +970 bps |
| Q2 FY26 JLR free cash flow | -£791 million | -£540 million | £251 million smaller outflow (my calculation) |
| India EBITDA margin | 5.8% | 4.0% | -180 bps |
| JLR wholesales | 82,400 (reported monthly data) | 82,500 | Within 100 units |
| India domestic wholesales | 196,674 | Not restated | Matches the preview data |
Cite this table: Tata Motors PV preview marks against the result, PositionalCalls, as of 13 November 2026, 6:30 PM IST.
The preview found no consensus estimate, so there is nothing to beat or miss, and I do not call the result either. Read the preview at Tata Motors PV Q2 results date FY27.
What do the reports not show about the Tata Motors PV Q2 results FY27?
The reports I read do not show the exceptional-item total, the tax line, the minority share, a dividend, a share price after the results, an analyst estimate, India market share, or standalone figures. All figures are headline-level and several come from automated summaries.
| Item | Found? | Why it matters |
|---|---|---|
| Exceptional-item total | No; JLR £530 million only | Explains most of the loss |
| Tax and minority share | No | Moves the loss attributable to owners |
| Dividend | None found | Record date decides who is paid |
| Share price after results | No; the results came after the close | First reaction falls on Monday 16 November |
| Analyst estimate | No | Needed to say beat or miss |
| Filing text | Not opened | All figures are headline-level |
Cite this table: Tata Motors PV items not found in the pages read, PositionalCalls, as of 13 November 2026, 6:30 PM IST.
Two of the sources carry cautions of their own. Multibagg shows an AI disclaimer and uses an unusual unit, and one Investywise page has internal inconsistencies, so I use them for figures that tie to other sources and flag the rest.
What does the arithmetic show for the Tata Motors PV result?
Six checks hold: revenue growth, the margin changes, the JLR bridge and the half-year sum tie; one does not: the JLR free cash outflow guidance against H1. The gap between profit before exceptional items and the loss cannot be tested without the filing.
| Check (my calculation) | Working | Result |
|---|---|---|
| Revenue growth | 96,920 / 72,349 – 1 | +33.96% |
| Sequential revenue | 96,920 / 95,799 – 1 | +1.2% on Q1 FY27 |
| EBITDA at 6.2% | 6.2% x 96,920 | About Rs 6,009 crore against Rs 4,866 crore at Business Upturn |
| Loss gap | 403 + 5,531 | Rs 5,934 crore below the operating line |
| JLR EBIT margin change | 1.1 – (-8.6) | +970 bps (matches Investywise) |
| JLR H1 revenue | 597.3 + 589.4 crore | £11.87 billion (matches +3.2%) |
| JLR H1 free cash flow | 99.8 + 54 crore | -£1.54 billion, above the £1.25 billion FY outflow guide |
Cite this table: Tata Motors PV Q2 FY27 tie-outs by PositionalCalls from the sources listed.
Two worked examples for a Tata Motors PV Q2 results FY27 reader
Example 1, the loss margin. Rs 5,531 crore over Rs 96,920 crore is a net loss of 5.7%, while profit before exceptional items of Rs 403 crore is 0.4% of revenue (my calculation). Example 2, the EBITDA gap. At 6.2% the EBITDA is about Rs 6,009 crore; at Rs 4,866 crore the margin is 5.0%, so the two definitions differ by 1.2 points, or about Rs 1,143 crore.
How do I read the next Tata Motors PV results after this one?
On the next results, read in this order: profit before exceptional items, the exceptional-items note, JLR free cash flow and guidance, JLR retail against wholesales, India EBITDA margin and net debt. These show whether the loss was a one-off.
| Order | Line to read | Mark to compare | Why it comes first |
|---|---|---|---|
| 1 | Profit before exceptional items | Rs 403 crore | The clean operating line |
| 2 | Exceptional items and tax | JLR £530 million; total not found | Drove the loss |
| 3 | JLR free cash flow | -£540 million; H1 -£1.54 billion | Funds the net debt |
| 4 | JLR retail against wholesales | 79,000 against 82,500 | Shows demand, not shipments |
| 5 | India EBITDA margin | 4.0%; Q2 FY26 5.8% | Growth did not lift margin |
| 6 | Net debt | Rs 50,800 crore | Balance sheet pressure |
Cite this table: Tata Motors PV reading order, PositionalCalls.
Any article on the Tata Motors PV Q2 results FY27 should say whether it is the passenger vehicle company or the commercial vehicle company, whether the loss is attributable to owners, and whether the year-ago profit is adjusted. If it does not, it is a headline, not a reading.
How do I read the Tata Motors PV filing and avoid fake tips?
Open the NSE or BSE announcement for Tata Motors Passenger Vehicles Limited, not a link in a message, and read the results table, the exceptional-items note and the investor presentation. Never pay anyone for results tips.
- Open the exchange announcement page for Tata Motors Passenger Vehicles Limited.
- Read the unaudited consolidated and standalone results for the quarter ended 30 September 2026.
- Compare with Rs 96,920 crore, Rs 403 crore and Rs 5,531 crore.
- Read the exceptional items, tax and non-controlling interest lines.
- Check the JLR figures against JLR’s own release, in pounds.
PositionalCalls is not SEBI-registered, gives no buy or sell calls and never asks for payment. Nothing here is investment advice.
What do most people miss in the Tata Motors PV Q2 results FY27?
Most readers of the Tata Motors PV Q2 results FY27 miss that profit before exceptional items was positive, that last year’s profit was a non-cash gain, and that JLR cash flow and a lower guidance matter more than the headline loss.
Analyst’s note. What stands out: revenue grew 34% and the operating line turned positive, yet exceptional charges, mostly in JLR, produced a loss (my reading). What is easy to miss: the headline year-on-year swing of Rs 81,701 crore is a base effect, and the retail-wholesale gap at JLR is a quieter signal than the loss. Caution: figures come from news and summary pages and I did not open the filing; this note is reasoning, not a forecast or target. Reader action: read the exceptional items and cash flow in the filing before relying on a headline.
Bottom line
The Tata Motors PV Q2 results FY27 show record revenue of Rs 96,920 crore, up 34%, a profit before exceptional items of Rs 403 crore and a consolidated net loss of Rs 5,531 crore, with JLR margin and cash flow weaker than in June. The gaps are the exceptional-item total, tax and the dividend, and this page gives no call. Read the preview at Tata Motors PV Q2 results date FY27.
PositionalCalls WhatsApp channel
Never miss an update
- Results dates and dividend news
- Numbers explained without tips or targets
- Updated posts as they go live
Tata Motors PV Q2 results FY27: frequently asked questions
What were the Tata Motors PV Q2 results FY27?
The Tata Motors PV Q2 results FY27 show a consolidated net loss of Rs 5,531 crore on revenue of Rs 96,920 crore, up 34% from Rs 72,349 crore. Profit before exceptional items was Rs 403 crore, EBITDA margin 6.2% and EBIT margin 1.1%. I did not open the filing.
Why did Tata Motors PV report a loss in Q2 FY27?
Profit before exceptional items was Rs 403 crore, so the loss of Rs 5,531 crore sits below that line. JLR alone reports about £530 million of exceptional items, but no source gives the group total, the tax line or the minority share. The filing will show them.
Is the Tata Motors PV loss worse than last year?
Not on a like-for-like basis. The year-ago profit of Rs 76,170 crore included a non-cash gain, and excluding it the year-ago result was about minus Rs 6,400 crore (my preview calculation). Profit before exceptional items improved from about minus Rs 5,462 crore to Rs 403 crore.
What did JLR report in Q2 FY27?
JLR revenue rose 20.3% to £5.9 billion, wholesales rose 24.7% to 82,500 and retail fell 7.5% to 79,000. The adjusted EBIT margin was 1.1% against 2.8% in June, and free cash flow was about minus £540 million, per Multibagg and Investywise.
What did Tata Motors India report in Q2 FY27?
India passenger vehicle revenue rose 50.9% to a record Rs 20,423 crore. EBITDA margin fell 180 basis points to 4.0%, EBIT margin was minus 0.3% and profit before exceptional items was about breakeven. Domestic wholesales were 196,674, up 40.3%, with EV volume up 90%.
Is this the same Tata Motors as the 23 October result?
No. The 23 October result was Tata Motors Limited, the commercial vehicle company, with revenue of Rs 25,338 crore. This Tata Motors PV Q2 results FY27 post covers Tata Motors Passenger Vehicles, which holds JLR and the India car business, with revenue of Rs 96,920 crore.
Why do the EBITDA figures differ across sources?
Business Upturn gives EBITDA of Rs 4,866 crore, about 5%, against minus Rs 1,404 crore a year ago. Upstox and Investywise give a 6.2% margin, which is about Rs 6,009 crore (my calculation). Neither states its definition, so compare each only with its own year-ago figure.
Did Tata Motors PV declare a dividend with Q2 results?
I found no dividend in the pages I read for the Tata Motors PV Q2 results FY27, and no mention of one in the summaries. Only the board outcome in the exchange filing can confirm a dividend and its record date, so check the BSE or NSE announcement.
What is JLR’s revised FY27 guidance after the Tata Motors PV Q2 results FY27?
Multibagg reports that JLR cut its FY27 adjusted EBIT margin guidance to 2-3% and expects a free cash outflow of about £125 crore, or £1.25 billion. That conflicts with an H1 outflow of about £1.54 billion, so I do not rely on it until the JLR release is read. The June guide was about 4%.
Is this a buy or sell recommendation for Tata Motors PV?
No. PositionalCalls is not SEBI-registered and gives no buy or sell calls, targets or price zones. This page reports the results from news and summary pages, I did not open the filing, and nothing here is investment advice. Consult a registered adviser before investing.
Sources
- NSE India: corporate announcements: Tata Motors Passenger Vehicles results filing.
- BSE India: corporate announcements: Tata Motors Passenger Vehicles results filing.
- Business Upturn: Tata Motors PV Q2 results, 4:30 PM IST; EBITDA differs from other sources.
- Lapaas Voice: Tata Motors PV Q2 FY27 net loss, 4:40 PM IST; cites Reuters for the year-ago profit.
- Upstox: Q2 results live blog, 13 November 2026.
- Investywise: Tata Motors PV Q2 FY27; segment lines, with internal inconsistencies noted.
- Investywise: Tata Motors PV board outcome; EBITDA, PBT and net debt.
- Multibagg: JLR margin pressure Q2 FY27; an automated summary with an AI disclaimer.
- Multibagg: JLR revises FY27 guidance; the free cash outflow figure conflicts with H1.
- Autocar Professional: Tata Motors PV Q2 FY26, the year-ago base and one-time gain.
Disclosure: PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent research and education site founded by Shubham Chaudhary. Nothing here is a recommendation, target or investment advice. How I researched this: for this page I read Business Upturn, Lapaas Voice, Upstox, Investywise, Multibagg and Autocar Professional, plus my own Tata Motors PV preview for the year-ago base and monthly volumes, noted where sources differ, and marked every derived number as my calculation. I did not open any company filing or exchange document. Figures are as of 13 November 2026, 6:30 PM IST.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive