
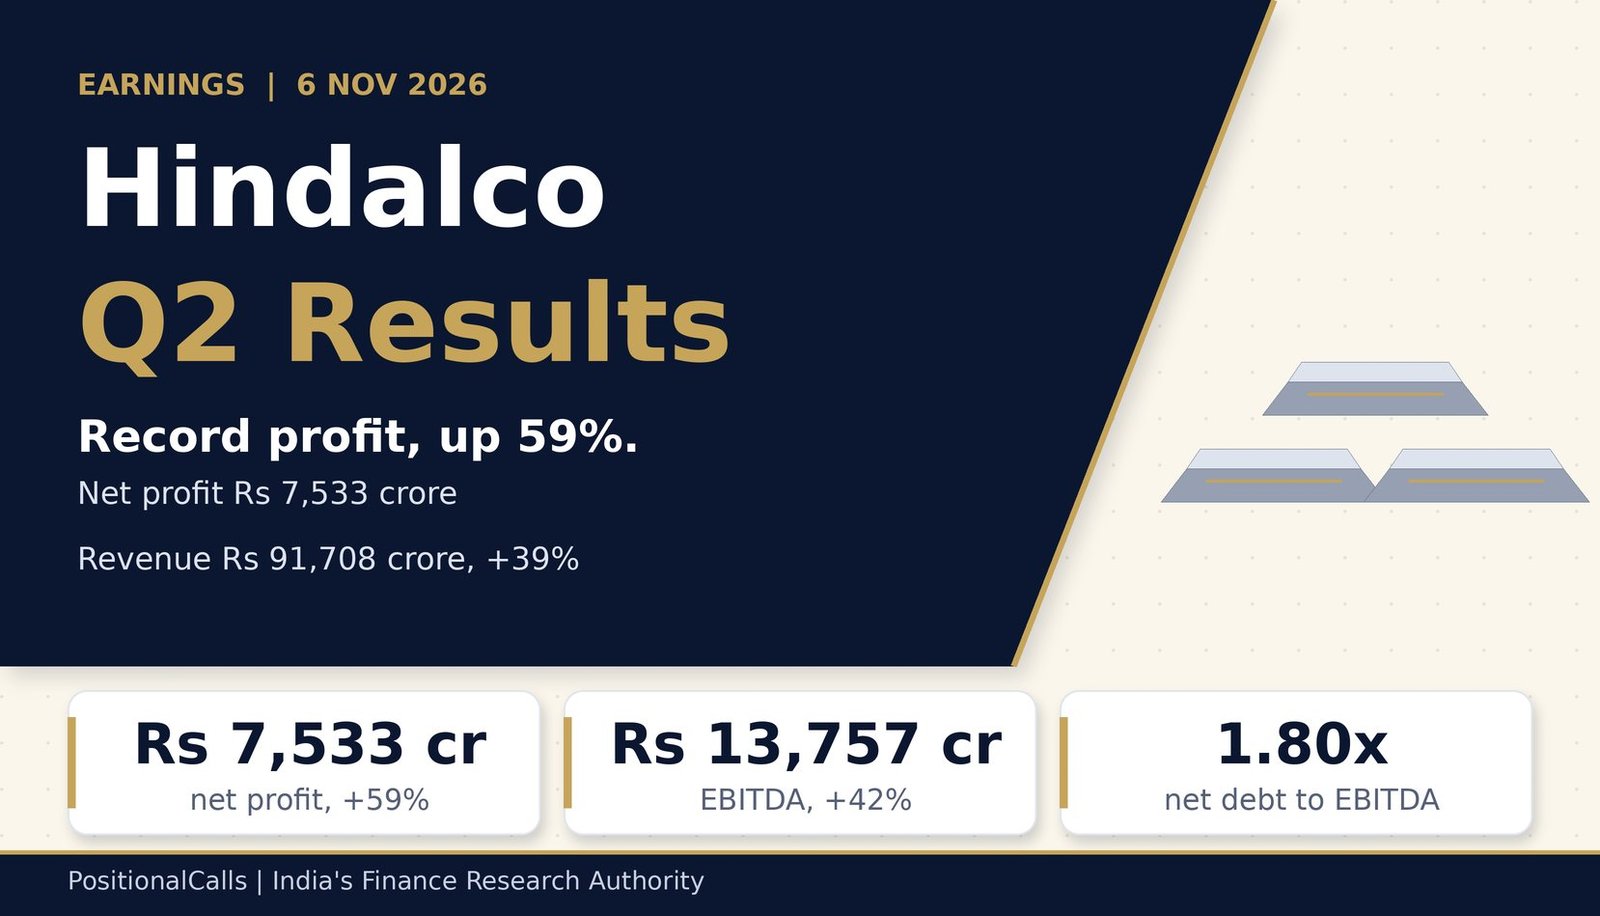
Earnings · Hindalco Industries
Hindalco net profit Q2 FY27 hit a record Rs 7,533 crore on 6 November 2026, beating even the highest case in our preview. Here is what drove it, what Novelis added, how the shares reacted and what to watch next.
Quick answer
Hindalco net profit Q2 FY27 was a record Rs 7,533 crore, up 58.9% year on year, on revenue of Rs 91,708 crore (+39%) and EBITDA of Rs 13,757 crore (+42%), reported on 6 November 2026. The shares closed about 2% higher at Rs 957.70 on the BSE.
Latest update (Saturday, 7 November 2026, 9:30 AM IST): The results, the Novelis release and the first share-price reaction are all in. Net debt to EBITDA eased to 1.80x. I found no Q3 date and no first-session reaction after the results beyond Friday’s close; Monday’s price will be added.
Key takeaways
- Profit: Hindalco net profit Q2 FY27 is Rs 7,533 crore, up 58.9% year on year and 7.4% on Q1 (my calculation).
- Revenue and EBITDA: Rs 91,708 crore (+38.8%) and Rs 13,757 crore (+42%), a margin of 15.0% against 17.7% in Q1.
- Engines: aluminium upstream EBITDA Rs 7,009 crore (+55%), record copper Rs 1,673 crore (+164%), Novelis Rs 4,858 crore.
- Quality: Novelis EBITDA includes $39 million of insurance recoveries; excluding it, growth is about 11% in dollars (my calculation).
- Shares: Rs 957.70 on the BSE (+1.88%); net debt to EBITDA 1.80x.
In plain words: Hindalco makes aluminium and copper in India and owns Novelis, a large US aluminium sheet maker. This quarter metal prices were higher and every engine contributed, so profit grew faster than sales. Part of the jump came from one-off insurance money at Novelis, which will not repeat.
Data note: Figures are as of Saturday, 7 November 2026, 9:30 AM IST. They follow Hindalco’s Q2 FY27 press release of 6 November 2026 and Novelis’s release of 5 November, as carried by EquityBulls, and reports by Upstox, Zee Business, Whalesbook, Kotak Neo and Mint. I did not open the exchange filing. Novelis reports in US dollars under US GAAP. Derived numbers are my calculation. The year-ago base of Rs 9,684 crore EBITDA matches the +42% growth the company reports.
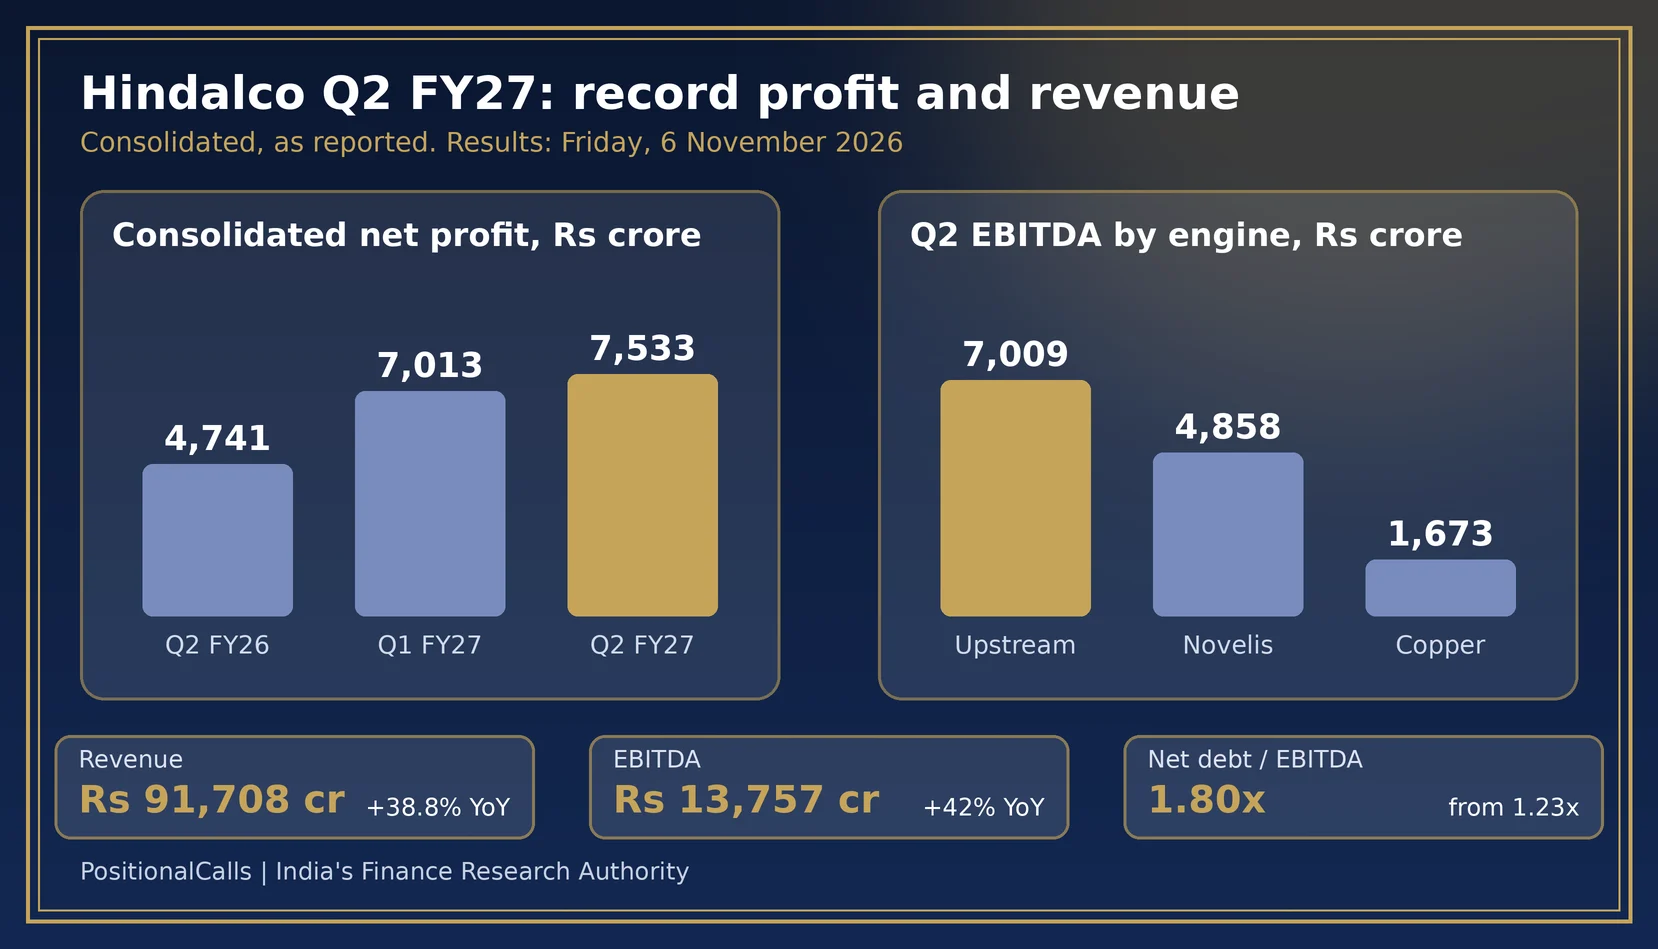
What was Hindalco net profit Q2 FY27, and what were the other Q2 results?
Hindalco net profit Q2 FY27 was Rs 7,533 crore (+58.9%), on consolidated revenue of Rs 91,708 crore (+38.8%), EBITDA of Rs 13,757 crore (+42%), for the quarter ended 30 September 2026, all records.
| Consolidated, Rs crore | Q2 FY26 | Q1 FY27 | Q2 FY27 | Change |
|---|---|---|---|---|
| Revenue from operations | 66,058 | 84,825 | 91,708 | +38.8% YoY; +8.1% QoQ |
| EBITDA | 9,684 | 14,989 | 13,757 | +42.1% YoY; -8.2% QoQ |
| EBITDA margin (my calculation) | 14.7% | 17.7% | 15.0% | +0.3 points YoY |
| Net profit | 4,741 | 7,013 | 7,533 | +58.9% YoY; +7.4% QoQ |
| H1 revenue | 1,30,290 | Not applicable | 1,76,533 | +35.5% |
| H1 EBITDA (my calculation) | 18,357 | Not applicable | 28,746 | +56.6% |
| H1 net profit (my calculation) | 8,745 | Not applicable | 14,546 | +66.3% |
Cite this table: PositionalCalls, “Hindalco Q2 FY27 Results Table, as of 5 November 2026”.
Hindalco net profit Q2 FY27 rose 7.4% on Q1 even though EBITDA fell 8.2%, which looks odd until you read the Novelis section below: insurance recoveries and special items lifted profit. Consolidated total income was Rs 92,651 crore against Rs 66,771 crore, per Kotak Neo. Standalone profit rose 7.3% to Rs 5,132 crore from Rs 4,784 crore in Q1 (my calculation).
Why did Hindalco net profit Q2 FY27 jump 59%?
Every engine grew: aluminium upstream EBITDA rose 55% to Rs 7,009 crore, copper hit a record Rs 1,673 crore (+164%) and Novelis adjusted EBITDA rose 32% in rupees. Non-LME-linked businesses supplied about half of earnings.
| Engine (Q2 FY27) | Revenue, Rs crore | EBITDA, Rs crore | Growth in EBITDA | Note |
|---|---|---|---|---|
| Aluminium upstream | 13,364 (+33%) | 7,009 | +55% | Margin about 52% |
| Aluminium downstream | 5,511 (+45%) | Not in sources | Record, per company | Revenue base 3,809 |
| Copper | Not in sources | 1,673 | +164% | Record; Q2 FY26 was 634 |
| Novelis | 56,798 (+37%) | 4,858 (adjusted) | +32% in rupees; +20% in dollars | Rs 41,418 crore revenue a year ago |
| Non-LME-linked businesses | Not applicable | 6,860 | +50% | About 50% of EBITDA (my calculation: 49.9%) |
Cite this table: PositionalCalls, “Hindalco Engine Table Q2 FY27, as of 5 November 2026”.
Operating leverage. Revenue rose 38.8%, EBITDA 42.1% and profit 58.9%. The margin edged up to 15.0% from 14.7%, so EBITDA growth came mostly from sales, price and volume rather than from a big margin gain; profit grew faster because costs below EBITDA rose more slowly.
What “non-LME-linked” means. LME is the London Metal Exchange, where aluminium and copper prices are set. Novelis, copper downstream and aluminium downstream earn mainly conversion margins, so they depend less on the LME price. The company says these businesses delivered about half of EBITDA, which makes earnings steadier when metal prices swing.
Hindalco EBITDA Q2 FY27: margin and the Q1 comparison
Hindalco EBITDA Q2 FY27 of Rs 13,757 crore is a 15.0% margin, against 17.7% in Q1 FY27 and 14.7% a year ago (my calculation). Read it as strong growth on a year earlier but a step down from Q1’s record.
Worked example: what each point of margin is worth
On revenue of Rs 91,708 crore, one percentage point of EBITDA margin is Rs 917 crore. Q1 FY27’s 17.7% margin on the same revenue would have given EBITDA of about Rs 16,230 crore against the actual Rs 13,757 crore, a gap of about Rs 2,470 crore (my calculation). That gap is why EBITDA fell on Q1 even as revenue rose.
Novelis Q2 FY27 results: what did Novelis report, and how much was one-off?
For Hindalco net profit Q2 FY27, Novelis reported net sales of $5.9 billion (+25%), adjusted EBITDA of $508 million (+20%) and net income of $210 million (+29%), helped by $39 million of Oswego insurance recoveries and favourable metal effects.
| Novelis (US GAAP) | Q2 FY26 | Q2 FY27 | Reading |
|---|---|---|---|
| Net sales | $4.7 billion | $5.9 billion (+25%) | Higher aluminium prices |
| Rolled shipments | 941 kilotonnes | 919 kilotonnes (-2%) | Automotive and specialty lower |
| Adjusted EBITDA | $422 million | $508 million (+20%) | Includes $39 million insurance recoveries |
| Adjusted EBITDA per tonne (my calculation) | $448 | About $553 | Q1 FY27 was $563; FY27 target about $500 |
| EBITDA per tonne excluding insurance (my calculation) | Not applicable | About $510 | $469 million over 919 kilotonnes |
| Net income | About $163 million (derived) | $210 million (+29%) | $146 million excluding special items |
| Net leverage (Novelis basis) | Not captured | 4.7x | Different basis from Hindalco’s 1.80x |
Cite this table: PositionalCalls, “Novelis Q2 FY27 Read-Across, as of 5 November 2026”.
Excluding the $39 million insurance recovery, Novelis adjusted EBITDA would be about $469 million, an 11% rise on $422 million (my calculation). At roughly Rs 95.6 to the dollar (implied by Rs 4,858 crore against $508 million), the recovery is worth about Rs 370 crore of Hindalco’s EBITDA. Hindalco’s rupee growth for Novelis, +32% against +20% in dollars, also reflects a weaker rupee of about 10% (my calculation).
Cash flow and Bay Minette
Novelis used $418 million of operating cash in the first six months, against an inflow of $411 million a year earlier, and its adjusted free cash flow was an outflow of $1.8 billion because of working capital, the Oswego fires and spending on its Bay Minette plant in Alabama. Bay Minette produced its first coil in September and expects commercial shipments in the first quarter of fiscal 2028. Novelis’s finance chief said falling capital spending should return free cash flow to positive toward the end of this fiscal year.
Preview versus actual: how did our Hindalco preview hold up?
Hindalco net profit Q2 FY27 beat the highest case in our preview scenarios on revenue and profit, while the margin landed in the lower half of the preview’s range and net debt to EBITDA eased from 1.95x to 1.80x.
Our preview, Hindalco Q2 results FY27: date, base to beat and Novelis, was published on 31 October 2026. Here is the comparison. The preview’s cases were arithmetic illustrations, not forecasts.
| Preview mark | What the preview showed | Actual Q2 FY27 | Reading |
|---|---|---|---|
| Date | Board and call Friday, 6 November, 4:30 PM IST; one weekly list showed 2 November | Results on Friday, 6 November | Company date was right |
| Base to beat | Q2 FY26 profit Rs 4,741 crore | Rs 7,533 crore (+58.9%) | Well above the base |
| Q1 bar | Q1 FY27 profit Rs 7,013 crore | +7.4% on Q1 | Above the Q1 record |
| Top revenue case | +32% on Q2 FY26, Rs 87,197 crore | Rs 91,708 crore (+38.8%) | Above the top case |
| Top profit case | Rs 7,013 crore, H1 +60.4% | Rs 7,533 crore; H1 +66.3% | Above the top case |
| Margin range | 14.7% to 17.7% | 15.0% | Lower half of the range |
| Novelis per tonne | Q1 was $563; target about $500 | About $553; about $510 excluding insurance | Above the target, slightly below Q1 |
| EBITDA definition trap | Rs 9,684, 9,104 and 8,966 crore all quoted for the base | +42% growth implies the Rs 9,684 crore base | Company headline definition used |
| Net debt to EBITDA | Q1 was 1.95x | 1.80x | Eased |
| Estimate | None found | Zee Business estimate Rs 6,880 crore; actual 9.5% higher (my calculation) | Beat on that estimate |
Cite this table: PositionalCalls, “Hindalco Preview Versus Actual, as of 5 November 2026”.
PositionalCalls WhatsApp channel
Hindalco results, then the next metals filing
- Price reactions and estimate changes as they appear
- Novelis and Hindalco numbers side by side
- Links to every updated Q2 FY27 page
After Hindalco net profit Q2 FY27 was reported, the Hindalco share price closed 1.88% higher at Rs 957.70 on the BSE on Friday, 6 November 2026, after rising from about Rs 919.70 at 12:47 PM, before the results appeared, a gain of about 4% in the session (my calculation).
| 6 Nov 2026 | What was reported | Source |
|---|---|---|
| 12:47 PM snapshot | Rs 919.70 (NSE), before the results | Trendlyne |
| First reports of results | About 1:56 PM to 3:26 PM IST | Whalesbook; Zee Business; Upstox |
| Close, BSE | Rs 957.70, +1.88% | Mint via TradingView |
| Close, aggregator | Rs 958, +2.19% | Screener |
| Market value | About Rs 2,15,374 crore | Screener |
| 52-week range | Rs 772 to Rs 1,179 | Screener |
Cite this table: PositionalCalls, “Hindalco Share Price After Q2 Results, as of 5 November 2026”.
Mint reported the stock up 7.25% over a week, 11.30% over two weeks, 21.53% over a year and 7.01% so far this year, but down 6.71% over three months. The 1.88% and 2.19% closes differ because of the exchange and previous-close used; I did not confirm the official NSE close. Nuvama upgraded its rating to Buy and raised FY27 and FY28 EBITDA estimates by 4% to 5%, and noted that 26% of expected FY28 aluminium volume is hedged at $3,168 a tonne. This page carries no targets or ratings of its own, and brokerage views are context, not a recommendation.
Hindalco rose on the day, but the Hindalco share price still sits below its 52-week high of Rs 1,179 by about 19% (my calculation: 957.70 against 1,179). The Monday, 9 November session will be the first full-session reaction, because Sunday’s Muhurat session is a special hour; see Muhurat trading 2026 for the timings.
Did Hindalco net profit Q2 FY27 beat estimates?
Yes, on the one estimate I found. Zee Business reported that profit beat its Rs 6,880 crore estimate, with revenue and EBITDA also ahead; actual profit was about 9.5% above it (my calculation).
I found no second estimate or consensus, so treat the beat as one house’s view. Our preview had no estimate to compare, only the base and the Q1 record. The Q1 pattern is a useful caution: in Q1 FY27 the street expected Rs 5,817 crore and the company delivered Rs 7,013 crore, so Hindalco has now beaten the one estimate quoted in each of the last two quarters. One data point is not a trend.
Which Hindalco figures differ across sources?
Hindalco net profit Q2 FY27 and its related figures vary by source: revenue appears as Rs 91,708 crore and total income as Rs 92,651 crore; profit as Rs 7,532 crore and Rs 7,533 crore; and Novelis EBITDA as Rs 4,858 crore, $508 million, +32% and +20%.
| Figure | Version A | Version B | What to do |
|---|---|---|---|
| Revenue | Rs 91,708 crore revenue from operations | Rs 92,651 crore total income | Use revenue from operations |
| Net profit | Rs 7,533 crore (company; Zee, Whalesbook) | Rs 7,532 crore (Upstox) | Rounding; use Rs 7,533 crore |
| Profit growth | +58.9% (my calculation) | +59% and +58.8% in headlines | Rounding |
| Novelis EBITDA growth | +32% in rupees (Rs 4,858 crore) | +20% in dollars ($508 million) | Name the currency |
| Novelis revenue | Rs 56,798 crore (Kotak Neo) | $5.942 billion (Upstox, Zee) | Same quarter, two currencies |
| Leverage | Hindalco 1.80x | Novelis 4.7x | Different definitions |
| Q2 FY26 EBITDA base | Rs 9,684 crore (company) | Rs 9,104 or 8,966 crore (other sources) | +42% growth implies Rs 9,684 crore |
Cite this table: PositionalCalls, “Hindalco Definition-Trap Table, as of 5 November 2026”.
What changed and when: for Hindalco net profit Q2 FY27, on 5 and 6 November 2026 the Novelis and Hindalco numbers resolved the uncertainty in the preview: the base is Rs 4,741 crore profit and Rs 9,684 crore EBITDA, and the company’s own growth rates use that base. Quote Novelis growth with its currency every time.
What did Hindalco management say about costs, coal and growth?
Managing Director Satish Pai said India aluminium production costs could be about 5% higher in Q3 than in Q2 on elevated coal costs, with relief expected from Q4 as coal availability improves.
| Item | What was reported | Source | Check in the filing |
|---|---|---|---|
| Coal cost | Q3 production cost about 5% above Q2; easing from Q4 | Mint, briefing remarks | Cost per tonne in the presentation |
| Coal stocks | About 50% of normal at some northern plants; Odisha normal | Mint | Plant-level commentary |
| Growth projects | Bay Minette, copper recycling, aluminium battery foil, Aditya FRP, inner grooved tubes | Company release | Capex and timeline |
| Upstream projects | Aluminium refinery, smelters, copper smelters and coal mines on track | Company release | Commissioning dates |
| Earnings call | Held 6 Nov; audio on the company website | Company announcement list | Transcript for margin remarks |
Cite this table: PositionalCalls, “Hindalco Management Commentary, as of 5 November 2026”.
Coal is the swing cost behind Hindalco net profit Q2 FY27 and Indian aluminium smelters generally, which is why our Coal India Q2 results FY27 page is a useful companion read. For peers, see Tata Steel Q2 results FY27 and the Q2 results calendar.
What should you watch next after the Hindalco Q2 results?
After the Hindalco net profit Q2 FY27 print, watch five lines: Q3 aluminium costs, Novelis cash flow, Bay Minette shipments, copper margins and the next results date, which is not announced.
| What to watch | Mark to compare | Why it matters |
|---|---|---|
| India aluminium cost | About 5% higher in Q3 (management) | Margin pressure before Q4 relief |
| Novelis free cash flow | Adjusted outflow of $1.8 billion in H1 | Deleveraging depends on it |
| Bay Minette | First coil in September; shipments in Q1 FY28 | Capex falls and earnings rise if on time |
| Copper EBITDA | Rs 1,673 crore record | Peak or new base? |
| Net debt to EBITDA | 1.80x against 1.95x in Q1 | Direction of leverage |
| Q3 FY27 results date | Not announced as of 7 November 2026 | Confirm on the exchange page |
Cite this table: PositionalCalls, “Hindalco Next-Quarter Watchlist, as of 5 November 2026”.
- Compare Q2 FY27 with Q2 FY26, then Q1 FY27.
- Name the EBITDA definition and the currency for Novelis.
- Strip out the $39 million insurance recovery when judging Novelis.
- Check the notes for exceptional and special items.
- Confirm dates in the exchange filing.
What it costs: reading a filing is free; trading adds brokerage, securities transaction tax and other charges, so check your broker’s current schedule. Tax angle: see our guides to capital gains tax on shares and dividend tax in India. NRI note: see NRI investment in the Indian stock market. Scam warning: fake result alerts and paid tips circulate on results days; never share an OTP.
What do most people miss about Hindalco net profit Q2 FY27?
- Profit rose on Q1 while EBITDA fell. Special items at Novelis lifted profit.
- Novelis growth is 20% or 32%. The difference is the weaker rupee.
- Part of Novelis EBITDA is insurance money. $39 million will not repeat.
- The margin fell on Q1. It was 15.0% against 17.7%.
- Two different leverage ratios. Hindalco 1.80x and Novelis 4.7x use different bases.
- The Rs 7,533 crore is a record, not a run rate. Coal costs rise in Q3.
Analyst’s note: how to think about this quarter
- What stands out (reasoning): Hindalco net profit Q2 FY27 beat the top of the preview’s range, but the margin was lower than in Q1, so the beat came from scale and special items, not from a better margin.
- Easy to miss: about half of EBITDA now comes from non-LME-linked businesses, which makes earnings steadier.
- What would change the view: Novelis free cash flow staying negative past this fiscal year, or coal costs rising well above 5%.
- Caution: one record quarter does not fix a long-term value. This page gives no target or recommendation.
- Reader action: read Novelis excluding insurance, then the Hindalco notes.
Bottom line
Known: Hindalco net profit Q2 FY27 is a record Rs 7,533 crore (+58.9%) on revenue of Rs 91,708 crore (+38.8%) and EBITDA of Rs 13,757 crore (+42%), reported on 6 November 2026. The shares closed about 2% higher.
Not known yet: the first full-session reaction on Monday, other estimate changes and the Q3 date.
Next read: Tata Steel Q2 results FY27, the other large metals result.
Part of the earnings coverage and metals series.
PositionalCalls WhatsApp channel
Never miss a metals result
- Novelis and Hindalco read-across, stamped and sourced
- Plain-language summaries of each filing
- Corrections as they happen
Hindalco net profit Q2 FY27: frequently asked questions
What was Hindalco net profit Q2 FY27?
Hindalco net profit Q2 FY27 was a record Rs 7,533 crore, up 58.9% from Rs 4,741 crore a year earlier and 7.4% above Q1 FY27’s Rs 7,013 crore (my calculation). Revenue rose 39% to Rs 91,708 crore and EBITDA 42% to Rs 13,757 crore.
When were the Hindalco Q2 results announced?
The Hindalco Q2 results came on Friday, 6 November 2026, after the board met, with an earnings call at 4:30 PM IST. The first reports I found are timestamped between about 1:56 PM and 3:26 PM IST. Novelis reported a day earlier, on 5 November.
Did Hindalco net profit Q2 FY27 beat estimates?
Zee Business reported that profit beat its estimate of Rs 6,880 crore, about 9.5% higher (my calculation), and that revenue and EBITDA also beat. I found no second published estimate, so this is one house’s figure, not a consensus.
The Hindalco share price closed 1.88% higher at Rs 957.70 on the BSE on Friday, 6 November, per Mint; Screener shows Rs 958, up 2.19%. A snapshot at 12:47 PM, before the results, showed Rs 919.70 on the NSE, so the stock rose about 4% after.
What was Hindalco EBITDA Q2 FY27, and how does it affect Hindalco net profit Q2 FY27?
Consolidated EBITDA was Rs 13,757 crore, up 42% year on year, a margin of 15.0% on revenue (my calculation). That is 8.2% below Q1 FY27’s record Rs 14,989 crore, when the margin was 17.7%. The company compares with the Rs 9,684 crore base.
What did Novelis report in Q2 FY27?
Novelis reported net sales of $5.9 billion (+25%), adjusted EBITDA of $508 million (+20%) and net income of $210 million (+29%) on shipments of 919 kilotonnes (-2%). Adjusted EBITDA includes $39 million of insurance recoveries tied to the 2025 Oswego fires.
Why did Hindalco net profit Q2 FY27 rise 59% when EBITDA rose 42%?
Profit grew faster because costs below EBITDA grew more slowly, and Novelis net income included special items such as insurance recoveries. Novelis net income was $210 million against $146 million excluding special items (my calculation: $64 million). Check the notes in the filing.
What is Hindalco net debt to EBITDA after Q2 FY27?
It was 1.80x at 30 September 2026, against 1.23x a year earlier and 1.95x at 30 June 2026, per the company. Novelis reports its own leverage of 4.7x on its basis. The two ratios use different definitions, so do not compare them directly.
What did Hindalco management say about costs and outlook?
Managing Director Satish Pai said India aluminium production costs could be about 5% higher in Q3 than in Q2 on elevated coal costs, easing from Q4 as coal availability improves. Bay Minette, copper recycling and aluminium battery foil are expected to raise non-LME-linked earnings.
When will Hindalco announce Q3 FY27 results?
The Hindalco Q3 FY27 results date has not been announced as of 7 November 2026. Last year’s Q3 coverage is on our Hindalco Q3 results FY26 page. Confirm any new date on the NSE or BSE announcement page when the board meeting is intimated.
Sources
- BSE corporate announcements: where the Hindalco filing appears.
- NSE corporate filings: financial results: the same filing on NSE.
- Hindalco Q2 FY27 press release, as carried by EquityBulls, 6 November 2026.
- Novelis Q2 FY27 press release, as carried by EquityBulls, 5 November 2026.
- Upstox: Hindalco Q2 profit soars 59%, 6 November 2026.
- Zee Business: Hindalco Q2 results beat estimates, 6 November 2026.
- Kotak Neo: Hindalco Q2 FY27 results, 6 November 2026.
- Mint via TradingView: Hindalco shares and brokerages, 7 November 2026.
- Screener: Hindalco company page and announcements, 6 November 2026.
- Hindalco press release, Q2 FY26 results (base quarter), 7 November 2025.
- Also named, not linked: Whalesbook, Trendlyne, Business Standard.
Disclosure: PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent research and education site founded by Shubham Chaudhary. Nothing here is a recommendation, target or investment advice. How I researched this: for Hindalco net profit Q2 FY27 I read the company’s and Novelis’s press-release text as carried by EquityBulls and reports by Upstox, Zee Business, Kotak Neo and Mint, noted where sources differ, and marked every derived number as my calculation. I did not open the exchange filing. Figures are as of Saturday, 7 November 2026, 9:30 AM IST.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive