
Earnings · Tata Steel · Q2 FY27
Tata Steel beat the profit consensus and the preview’s EBITDA table, but net debt rose and the UK loss widened. Here are the profit definitions, regional lines, net debt, brokerage views as reported and the price position.
Quick answer
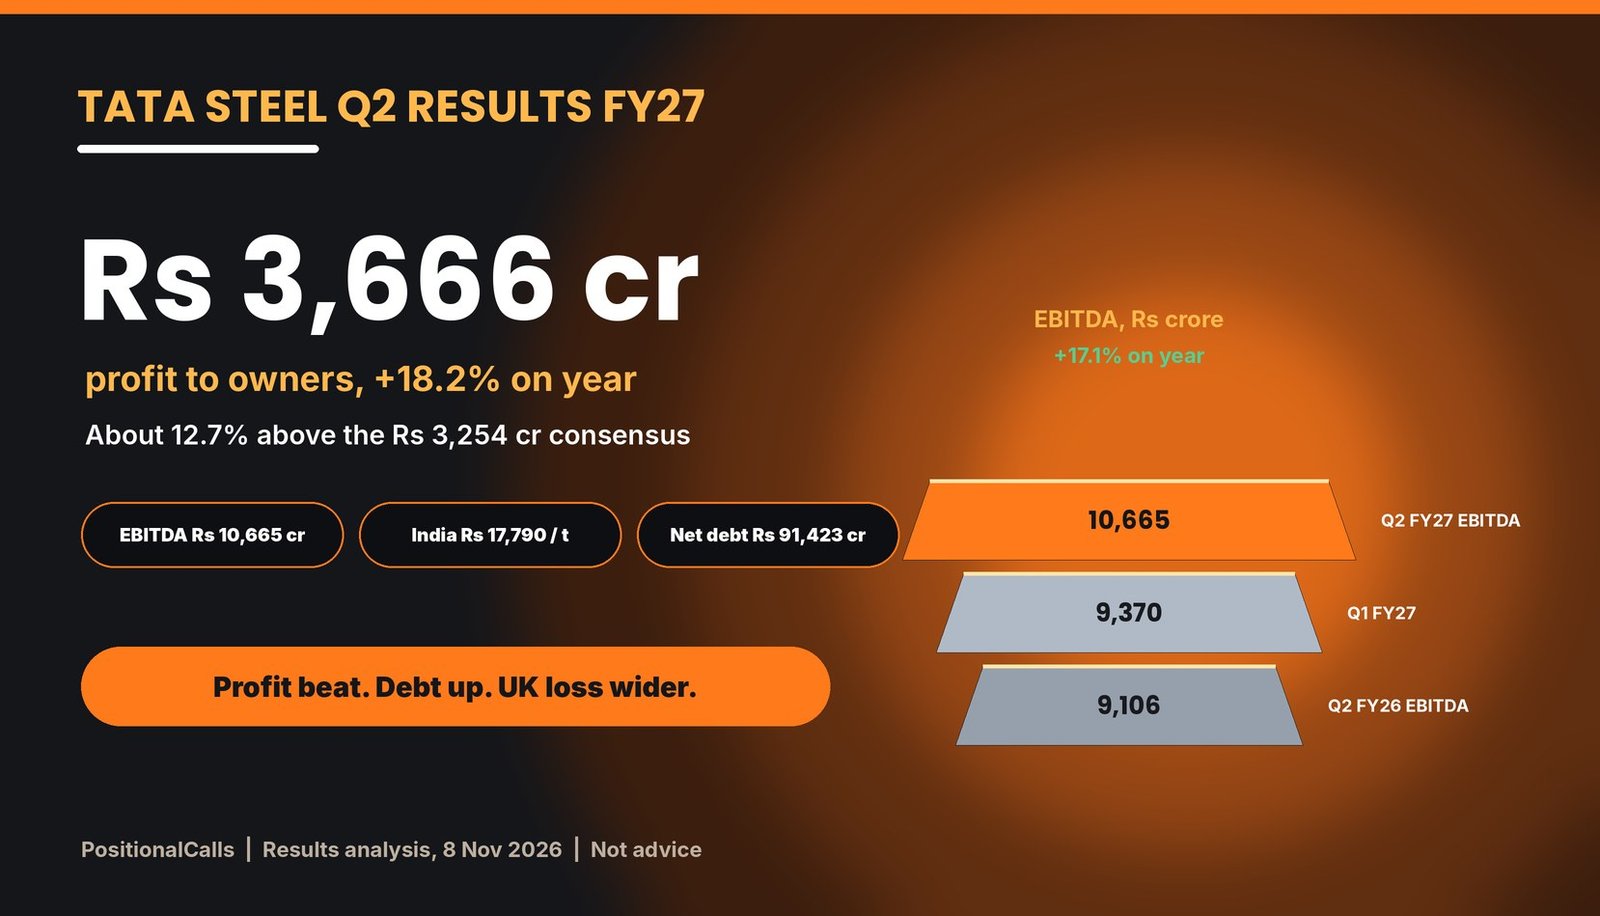
Tata Steel Q2 results FY27: Tata Steel reported profit to owners of Rs 3,666 crore, up 18.2% and about 12.7% above the Rs 3,254 crore consensus (my calculation), with EBITDA of Rs 10,665 crore and revenue of Rs 65,436 crore, on 7 November 2026. Net debt rose to Rs 91,423 crore.
Latest update (Sunday, 8 November 2026, 1:30 AM IST): Tata Steel announced the Tata Steel Q2 results FY27 on Saturday, 7 November, and ANI’s report was published at 6:32 PM IST. The last price I found is Rs 181.20 on Friday, 6 November, before the results (Business Today). I did not find a post-result brokerage note or a price reaction; the first chance is the special Muhurat session on Sunday, 8 November, then the regular session on Monday, 9 November.
Key takeaways
- Profit: Net profit to owners Rs 3,666.41 crore (+18.2% on year, +58.1% on Q1); a rounded Rs 3,700 crore profit after tax includes minority interest.
- Against estimates: Consensus of 12 analysts was Rs 3,253.7 crore (Bloomberg, as cited), so profit was about 12.7% higher (my calculation); revenue beat by about 2.0%.
- EBITDA: Rs 10,665 crore (+17.1% on year, +13.8% on Q1), above every row of the sensitivity table in the preview; consolidated EBITDA per tonne was about Rs 13,466 (my calculation).
- India: India EBITDA Rs 10,634 crore at Rs 17,790 per tonne, a 25% margin, on domestic deliveries of 5.98 million tonnes (+16% on Q1).
- Europe: Netherlands EBITDA recovered to about Rs 790 crore after the plant restart, but the UK loss widened to about Rs 719 crore from Rs 341 crore in Q1.
- Watch: Net debt rose Rs 7,250 crore to Rs 91,423 crore from 30 June (my calculation); no share-price reaction yet, as the result came on a Saturday.
Preview post, 28 October 2026Tata Steel Q2 results preview: new date, base to beat and what to check first
- The move of the board date from 27 October to 7 November
- The Rs 9,106 crore EBITDA and Rs 3,102 crore profit base
- A sensitivity table for Q2 EBITDA and a results-day decoder
Read the full preview post for the checklist made before the numbers arrived.
This results analysis, 8 November 2026What the numbers showed
- Consolidated, India, Netherlands and UK lines against the base
- Profit against the consensus and EBITDA against the preview table
- Net debt, brokerage views as reported and the price position
A table further down grades each preview mark against the actual figure.
How to read this page: it is results analysis, not a recommendation. Brokerage ratings and targets are quoted as reported with source and date; none is mine. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser.
In plain words: Tata Steel earned Rs 3,666 crore after tax and minority share in the September quarter, up from Rs 3,102 crore a year ago. EBITDA is operating profit before interest, tax and depreciation, and net debt is borrowings less cash. Here profit and EBITDA grew, but net debt also grew, so both sides of the story belong in one read.
Data note: as of Sunday, 8 November 2026, 1:30 AM IST. Figures come from press and data-platform summaries of the filing (Business Standard, ANI via The Tribune, Investywise and TradingView); I did not open the BSE or NSE filing or the company press release. Business Standard and Investywise do not give the Netherlands and UK lines in the same currency as ANI, so I show both and tie them. NewsBytes gives revenue of Rs 64,974 crore against Rs 65,436 crore elsewhere; I use the figure three reports share. Derived numbers are marked “my calculation”.
Tata Steel Q2 results FY27: what Tata Steel reported on 7 November
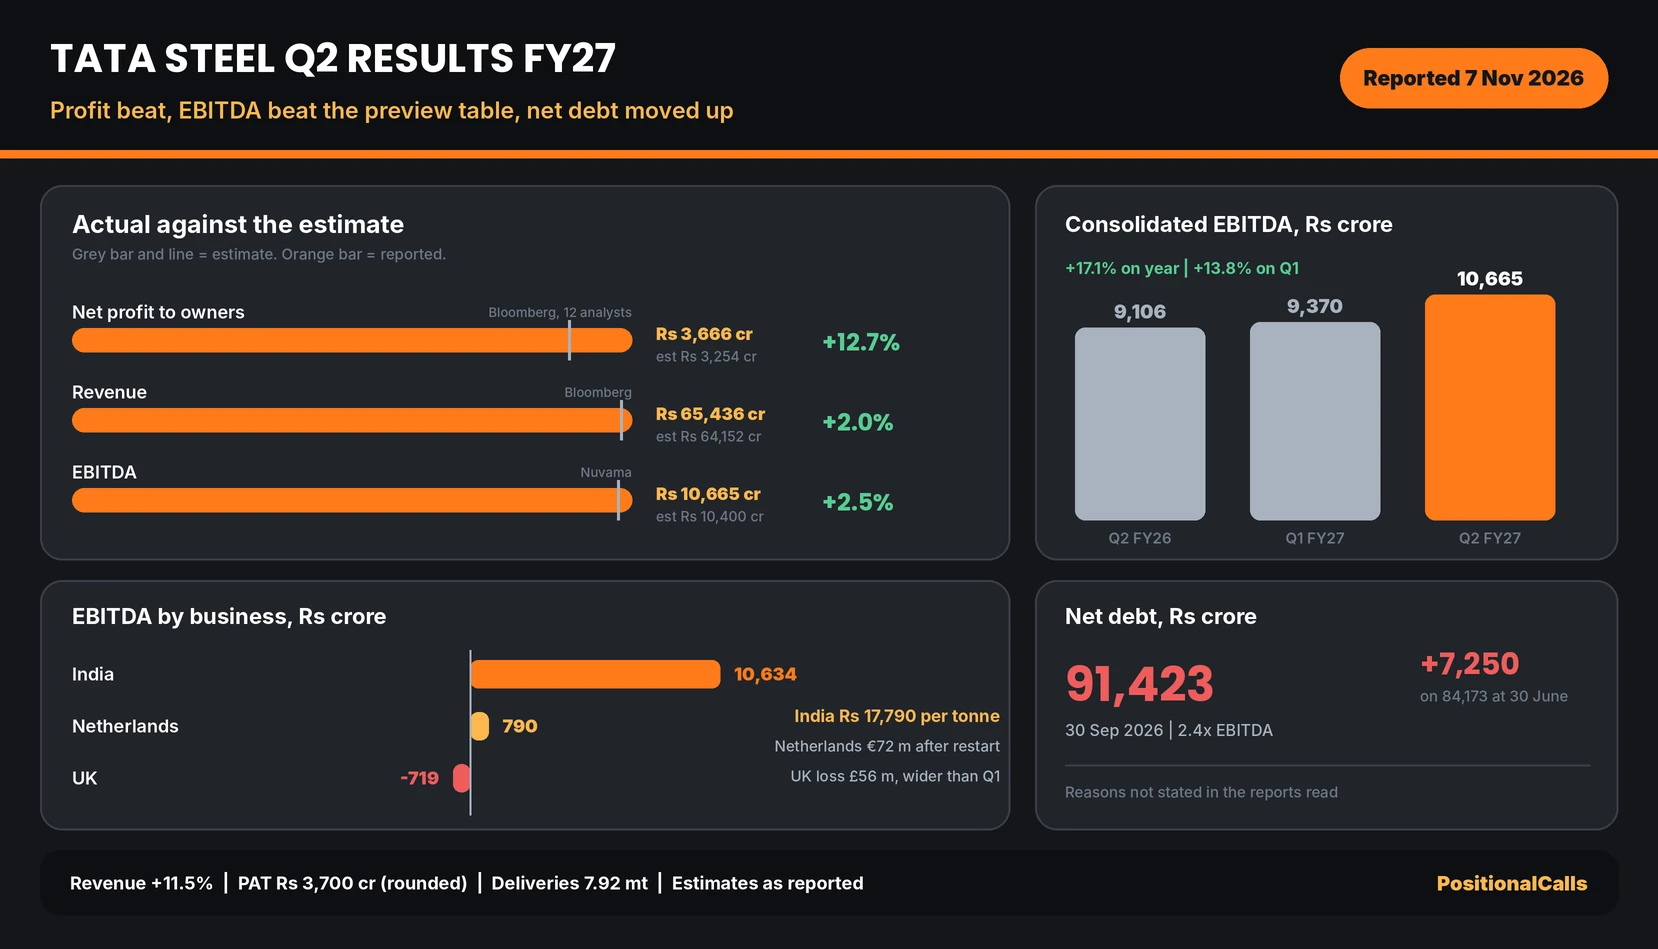
The Tata Steel Q2 results FY27 show revenue of Rs 65,436 crore (+11.5%), EBITDA of Rs 10,665 crore (+17.1%), profit to owners of Rs 3,666 crore (+18.2%) and net debt of Rs 91,423 crore, with 7.92 million tonnes delivered.
| Measure (consolidated) | Q2 FY27 | Q2 FY26 base | Q1 FY27 | Change on year |
|---|---|---|---|---|
| Revenue from operations | Rs 65,436 crore | Rs 58,689 crore | Rs 60,794 crore | +11.5% (+7.6% on Q1) |
| EBITDA | Rs 10,665 crore | Rs 9,106 crore | Rs 9,370 crore | +17.1% (+13.8% on Q1) |
| Profit after tax, reported | Rs 3,700 crore (rounded) | Rs 3,183 crore | Rs 2,385 crore | +16.2% (my calculation) |
| Net profit to owners | Rs 3,666.41 crore | Rs 3,101.75 crore | Rs 2,318.35 crore | +18.2% (+58.1% on Q1) |
| Deliveries | 7.92 million tonnes | 7.91 million tonnes | 7.27 million tonnes | Flat on year, +8.9% on Q1 |
| Net debt | Rs 91,423 crore | Rs 87,040 crore | Rs 84,173 crore | +5.0% on year (my calculation) |
Cite this table: PositionalCalls, “Tata Steel Q2 FY27 Results Table, as of 8 November 2026”.
The Tata Steel Q2 results FY27 are a clear step up from the June quarter: profit to owners rose 58.1% on Q1, EBITDA 13.8% and deliveries 8.9%. Year on year deliveries were flat at 7.92 against 7.91 million tonnes, so the 17.1% EBITDA growth came from price, cost and mix and from Europe, not from tonnes (my reading). Half-year figures tie: Q1 EBITDA of Rs 9,370 crore plus Q2 EBITDA of Rs 10,665 crore is Rs 20,035 crore, the half-year figure in the Investywise table, and half-year revenue of Rs 1,26,231 crore matches the two quarters within Rs 1 crore (my calculation). The rest of this page splits the profit definitions, the regional lines, the grading of the preview post and the balance sheet.
Tata Steel Q2 FY27 profit: Rs 3,666 crore against the Rs 3,254 crore consensus
Net profit attributable to owners was Rs 3,666.41 crore, up 18.2% on year and 58.1% on Q1; against a Bloomberg consensus of Rs 3,253.7 crore from 12 analysts, as cited, that is about 12.7% higher (my calculation).
| Profit definition (consolidated, Rs crore) | Q2 FY27 | Q2 FY26 | Q1 FY27 | Where you see it |
|---|---|---|---|---|
| Net profit attributable to owners | 3,666.41 | 3,101.75 | 2,318.35 | Business Standard, TradingView |
| Profit after tax, incl. minority | About 3,700 | 3,183 | 2,385 | ANI, Investywise (rounded) |
| Minority share (my calculation) | About 34 | About 81 | About 67 | Difference of the two rows |
Cite this table: PositionalCalls, “Tata Steel Q2 FY27 Profit Definitions, as of 8 November 2026”.
The preview’s profit-definition trap showed up again: ANI and Investywise headline Rs 3,700 crore, Business Standard and TradingView use Rs 3,666.41 crore, and NewsBytes rounds to Rs 3,660 crore. The Rs 3,700 crore figure is profit after tax including minority interest; the same table carries Rs 3,183 crore for last year, the preview’s base. The roughly Rs 34 crore gap is a minority share on rounded data. Use Rs 3,666.41 crore for per-share work and for the 18.2% growth in the Tata Steel Q2 results FY27.
The India line needs care. Tata Steel India’s profit after tax of Rs 5,055 crore is larger than the group’s Rs 3,666 crore because it covers India alone, while the group figure also carries the Netherlands, the UK and other subsidiaries (my reading). I found no bridge, and its year-ago base is derived from the reported 19.9% growth.
On the estimate, Business Today listed the Bloomberg consensus at Rs 3,254 crore on 6 November and TradingView gave Rs 3,253.7 crore from 12 analysts after the result, so the two agree. Business Today’s table also lists an undefined “parent net profit” of Rs 4,576 crore that fits no reported figure; I do not use it. Investec’s Ritesh Shah, quoted by TradingView, credited industry tailwinds, cost initiatives and iron ore monetisation. That is one analyst’s reading, and no report sizes any one-off, so check the filing for exceptional items before calling the Tata Steel Q2 results FY27 profit clean.
Tata Steel EBITDA per tonne Q2 FY27: India carried the quarter
India EBITDA was Rs 10,634 crore at Rs 17,790 per tonne and a 25% margin on revenue of Rs 42,653 crore (+22.6%); the fall in per-tonne EBITDA from Q1 was Rs 1,372 against the Rs 1,500 management had guided.
| India business | Q2 FY27 | Q2 FY26 base | Q1 FY27 | Check |
|---|---|---|---|---|
| Revenue | Rs 42,653 crore | Rs 34,787 crore | Rs 36,989 crore | +22.6% on year, matches Business Standard |
| EBITDA | Rs 10,634 crore | Rs 8,654 crore | Rs 9,908 crore | +22.9% on year, +7.3% on Q1 (my calculation) |
| EBITDA per tonne | Rs 17,790 | Not shown | Rs 19,162 | -Rs 1,372 on Q1 (my calculation) |
| Domestic deliveries | 5.98 million tonnes | Not shown | 5.17 million tonnes | +16% on Q1; crude steel 6.18 million tonnes |
Cite this table: PositionalCalls, “Tata Steel India Q2 FY27 Table, as of 8 November 2026”.
In the Tata Steel Q2 results FY27, Tata Steel EBITDA per tonne Q2 FY27 held up better than the guidance in the preview post: management had pointed to about Rs 1,500 lower domestic realisation, and per-tonne EBITDA fell Rs 1,372 (19,162 to 17,790, my calculation), while volumes recovered 16% after the Q1 maintenance shutdowns. 5.98 million tonnes at Rs 17,790 gives Rs 10,638 crore, within Rs 4 crore of the reported Rs 10,634 crore, so the three figures tie. Consolidated EBITDA per tonne was about Rs 13,466 (10,665 over 7.92 million tonnes, my calculation), above the “Rs 13,000” level ANI reports.
Production figures differ by source. The 7 October volume update (Free Press Journal) gave India crude steel of 6.21 million tonnes and domestic deliveries of 5.97 million, against 6.18 million and 5.98 million in the results reports; I use the results figures.
Tata Steel Netherlands and UK in Q2 FY27: recovery and a wider loss
Netherlands EBITDA rose from about Rs 39 crore in Q1 to about Rs 790 crore (€72 million) after the Direct Sheet Plant restart in August, while the UK EBITDA loss widened to about Rs 719 crore (£56 million) from Rs 341 crore in Q1.
| Region | Q2 FY27 | Q2 FY26 | Q1 FY27 | Note |
|---|---|---|---|---|
| Netherlands revenue | Rs 15,330 cr / €1,395 m | Rs 15,719 cr | €1,445 m | -2.5% in rupees (my calculation) |
| Netherlands EBITDA | Rs 790 cr / €72 m | Rs 916 cr / €92 m | Rs 39 cr / €4 m | -13.8% in rupees, -21.7% in euros |
| UK revenue | Rs 5,275 cr / £411 m | Rs 5,927 cr | £484 m | -11.0% in rupees (my calculation) |
| UK EBITDA | -Rs 719 cr / -£56 m | -Rs 765 cr / -£66 m | -Rs 341 cr / -£27 m | Loss narrower on year, wider on Q1 |
| UK deliveries | Down 22% on Q1 | Not shown | Not shown | Weak demand, stock build, trade measures from 1 July |
Cite this table: PositionalCalls, “Tata Steel Europe Q2 FY27 Table, as of 8 November 2026”.
The two currencies tie. Netherlands revenue of Rs 15,330 crore over €1,395 million implies about Rs 10.99 a euro, and EBITDA of Rs 790 crore over €72 million implies about Rs 10.97; for the UK, Rs 5,275 crore over £411 million gives about Rs 12.83 and Rs 719 crore over £56 million about Rs 12.84 (my calculation). That also explains why the Netherlands EBITDA fell 13.8% in rupees but 21.7% in euros against Q2 FY26: the euro-rupee rate moved. Business Standard shows rupees and ANI shows euros and pounds, and the Tata Steel Q2 results FY27 are consistent across both.
The non-India gap, which the preview tracked, turned positive. Consolidated EBITDA of Rs 10,665 crore less India EBITDA of Rs 10,634 crore leaves Rs 31 crore, against minus Rs 538 crore in Q1 and plus Rs 452 crore in the Q2 FY26 base (my calculation). Netherlands and UK together add Rs 71 crore (790 less 719), so other lines and eliminations are about minus Rs 40 crore. The preview noted management’s aim of UK EBITDA breakeven in H2 FY27; with the loss wider than Q1 I found no new guidance in the reports, so that target is an open question for the earnings-call transcript.
For the Tata Steel Q2 results FY27, Europe is therefore the swing factor. The Netherlands plant restarted only in early August, so the quarter holds about two months of its effect, and the company said it is working closely with regulators on environmental issues (Business Standard). In the UK, weak demand, high stock and higher imports pushed deliveries down 22% on Q1, and stock was built ahead of revised trade measures that took effect on 1 July 2026. Neither report gives a Q3 outlook, so any Q3 figure would be my own arithmetic and I do not make one.
PositionalCalls WhatsApp channel
Tata Steel and metals results on WhatsApp
- Profit basis and one-offs stated for each result
- Conflicts between sources shown, not hidden
- The next company on the results calendar
Tata Steel Q2 results FY27 against the preview marks
EBITDA of Rs 10,665 crore came in 4.1% above the highest row of the preview’s sensitivity table, India EBITDA per tonne fell less than guided, the non-India gap turned positive, and the Netherlands restarted, so most preview marks landed on the stronger side.
| Preview mark | What the preview said | What was reported | Reading |
|---|---|---|---|
| Board date | 7 November, moved from 27 October | Results announced on 7 November | Confirmed |
| EBITDA | Rs 9,106 crore base; Rs 9,370 crore Q1 | Rs 10,665 crore | +17.1% on base |
| Sensitivity rows | A 8,593; B 9,706; C 9,126; D 10,244 | Rs 10,665 crore | Above row D by Rs 421 crore |
| India EBITDA per tonne | Assumed Rs 17,662 (Q1 less Rs 1,500) | Rs 17,790 | Rs 128 higher |
| India deliveries | Assumed 5.80 million tonnes | 5.98 million tonnes | 0.18 million higher |
| Non-India gap | Assumed minus Rs 538 crore | Plus Rs 31 crore | Swing of Rs 569 crore |
| Profit to owners | Base Rs 3,102 crore; Q1 Rs 2,318 crore | Rs 3,666 crore | +18.2% on base |
| Netherlands | Restart expected; EBITDA €4 million in Q1 | €72 million; restart in August | Recovered |
| UK | Breakeven aimed for H2 FY27 | Loss of £56 million, wider than Q1 | Not on track in Q2 |
| Dividend | No interim in the records | No dividend found in the reports | Unchanged |
Cite this table: PositionalCalls, “Tata Steel Q2 FY27 Preview-to-Result Table, as of 8 November 2026”.
The sensitivity table was arithmetic, not a forecast, and the actual result beat all four rows. India EBITDA at Rs 10,634 crore is Rs 390 crore above the Rs 10,244 crore of rows B and D (my calculation), because both volume and per-tonne EBITDA came in a little better than assumed, and the non-India gap did better than the minus Rs 538 crore that was held constant. The preview also warned that Q2 profit growth would be harder than EBITDA growth because the base was high; in the event profit to owners grew 18.2% against EBITDA growth of 17.1%, so that warning did not bind.
Tata Steel net debt Q2 FY27: Rs 91,423 crore, up Rs 7,250 crore
Net debt was Rs 91,423 crore at 30 September 2026, up Rs 7,250 crore (8.6%) from Rs 84,173 crore on 30 June and up Rs 4,383 crore on year (my calculation), and net debt to EBITDA was 2.4x against 2.3x in Q1.
| Balance sheet line | 30 Sep 2026 | 30 Jun 2026 | 30 Sep 2025 | Note |
|---|---|---|---|---|
| Net debt | Rs 91,423 crore | Rs 84,173 crore | Rs 87,040 crore | +8.6% on Q1, +5.0% on year (my calculation) |
| Net debt to EBITDA | 2.4x | 2.3x | Not shown | As reported |
| Group liquidity | Rs 40,076 crore | Not shown | Not shown | ANI |
| Capex, quarter | Rs 3,280 crore | About Rs 3,580 crore | Not shown | Q1 is H1 less Q2 (my calculation) |
| Capex, half-year | Rs 6,860 crore | Not applicable | Not shown | ANI, Business Standard |
| Gross debt and cash | About Rs 1.02 lakh crore; cash above Rs 10,000 crore | Not shown | Not shown | NewsBytes only |
Cite this table: PositionalCalls, “Tata Steel Net Debt Q2 FY27 Table, as of 8 November 2026”.
In the Tata Steel Q2 results FY27, Tata Steel net debt Q2 FY27 rose even though EBITDA rose Rs 1,295 crore on Q1 (my calculation), and the reports I read do not explain the increase. Capex of Rs 3,280 crore explains only part of it, and working capital, tax, dividends, interest and currency translation of the Europe debt are all candidates that I cannot size from these sources. The preview showed net debt falling Rs 2,867 crore in Q1, so the direction has reversed.
The single-source gross debt and cash figures hang together: about Rs 1.02 lakh crore of gross debt less cash of just over Rs 10,000 crore is close to the reported net debt, but NewsBytes is the only source, so treat it as approximate. The cash-flow statement and the management call should explain it.
The last price I found is Rs 181.20 on 6 November, before the results; HDFC Securities (Buy, Rs 210) and HSBC (Buy, Rs 260) were reported before the numbers, undated, and I found no post-result target. These are brokerages’ views, not PositionalCalls targets.
| Item | Level or view | Source and note |
|---|---|---|
| Price, 6 November | Rs 181.20, -0.44% | Business Today; market cap about Rs 2.26 lakh crore |
| Price after results | Not available | Results came on a Saturday; no session has traded |
| HDFC Securities | Buy; target Rs 210; buy range Rs 168 to 175 | Business Today; undated; 25% upside implies an older price |
| HSBC | Buy; target Rs 260 | Business Today; undated; says the discount to peers is unwarranted |
| Nuvama | Listed among top picks; no target given | Business Today |
| Gap to Rs 181.20 (my calculation) | HDFC +15.9%; HSBC +43.5% | Arithmetic on the pre-result price, not a forecast |
Cite this table: PositionalCalls, “Tata Steel Share Price and Brokerage Views After Q2 FY27, as of 8 November 2026”.
After the Tata Steel Q2 results FY27, the Street picture is incomplete, and I would rather say so than invent one. The Tata Steel share price after Q2 is also unknown, because no session has traded since the filing. The two targets are from before the numbers and carry no dates in Business Today’s story; HDFC’s “about 25% upside” against a Rs 168 to 175 buy range implies a share price well below the Rs 181.20 of 6 November, so that note looks older than the page. Against Rs 181.20 the same target is about 15.9% higher (my calculation). The pre-result estimates were Revenue Rs 64,152 crore (Bloomberg) and consolidated adjusted EBITDA of Rs 10,400 crore from Nuvama, which makes actual revenue 2.0% higher and EBITDA 2.5% higher (my calculation). Nuvama had also expected India EBITDA per tonne of Rs 16,594 on a standalone adjusted basis, against Rs 17,790 reported for the India business; the bases differ, so I do not compute a gap. See the Muhurat trading 2026 guide for the Sunday session and how the first reaction will be read.
Management commentary, dividend and Noel Tata’s retirement
CEO T V Narendran said the company delivered strong growth in deliveries and earnings and that India remained the cornerstone; I found no dividend in the reports, and Noel Tata retires as vice-chairman on 11 or 12 November depending on the source.
- Management: “India continued to be the cornerstone of our performance” and “We delivered strong growth in deliveries and earnings this quarter” (T V Narendran, as reported by ANI). CFO Koushik Chatterjee called it a resilient performance in a volatile environment.
- Automotive: best-ever Q2 volumes of 1.1 million tonnes in Automotive and Special Products, with high-end sales growth of 26% (ANI; the report prints “Rs” before the tonnes, which I treat as a typo).
- NINL: EBITDA of Rs 318 crore; the amalgamation is on track for this financial year, subject to final NCLT approval (ANI).
- Dividend: none of the reports I opened mentions an interim dividend. The preview recorded a pattern of one final dividend a year, so confirm on the BSE or NSE page.
- Governance: Business Standard and NewsBytes say Noel Tata retires as non-executive vice-chairman at the close of business on 11 November; National Herald, from 28 October, says he steps down on 12 November, when he turns 70. The dates differ by a day and I cannot settle it.
The commentary supports the India story in the Tata Steel Q2 results FY27. What it leaves open is the Europe guidance and the cash flow behind the higher net debt. For how another metals company reported, read Hindalco Q2 results FY27, and for a different cyclical business see Coal India Q2 results FY27.
What ties and what does not in the Tata Steel Q2 results FY27
Eleven checks tie, and four do not: the revenue figure in one report, the profit headline, the India profit bridge and the one-off content of profit.
Because of these gaps, any number you quote from the Tata Steel Q2 results FY27 should carry its definition. The filing’s results statement and the press release settle most of them, and both are free on the BSE, NSE and company pages. Treat any message promising a sure-shot call on Tata Steel as unreliable.
Risks to read with the Tata Steel Q2 results FY27
Analyst’s note on the Tata Steel Q2 results FY27
The quarter is a strong operating beat with a balance-sheet question attached, which is exactly the split the preview told readers to look for.
- What stands out: EBITDA beat every row of the preview table and profit beat the consensus by about 12.7%.
- Easy to miss: net debt rose Rs 7,250 crore and deliveries were flat on year, so the beat came from realisation, cost and Europe.
- What would change the view: an exceptional gain in the filing, a restated Europe line or a cash-flow explanation of the debt rise.
- Caution: one quarter does not fix a long-term value, and the two targets I found predate the result.
- Reader action: read the exceptional items and the cash-flow statement before the profit headline.
Bottom line
The Tata Steel Q2 results FY27 show profit to owners of Rs 3,666 crore (+18.2%), about 12.7% above the consensus, and EBITDA of Rs 10,665 crore, above every row of the preview table, led by India at Rs 17,790 a tonne. Net debt rose Rs 7,250 crore to Rs 91,423 crore and the UK loss widened. No brokerage target after the results was found. Read the exceptional items and the cash-flow statement in the filing and speak to a registered adviser before acting.
Next read: the preview post for the marks set before the results.
Part of the Earnings series.
PositionalCalls WhatsApp channel
Never miss a results update
- Same-day decoders with the numbers sourced
- Corrections posted openly when a number changes
- Plain-language risk notes
Tata Steel Q2 results FY27: frequently asked questions
What are the Tata Steel Q2 results FY27?
Tata Steel reported consolidated revenue of Rs 65,436 crore (+11.5%), EBITDA of Rs 10,665 crore (+17.1%) and net profit to owners of Rs 3,666 crore (+18.2%) for the quarter ended 30 September 2026. The board met on Saturday, 7 November 2026.
What is Tata Steel’s Q2 FY27 net profit, Rs 3,666 crore or Rs 3,700 crore?
Rs 3,666.41 crore is net profit attributable to owners. Rs 3,700 crore is reported profit after tax including minority interest, rounded; last year’s comparable figure was Rs 3,183 crore. Always label which one you quote.
Did Tata Steel beat Q2 estimates?
Profit to owners of Rs 3,666 crore was about 12.7% above the Rs 3,253.7 crore Bloomberg consensus of 12 analysts as cited by TradingView (my calculation). Revenue was about 2.0% above the Rs 64,152 crore estimate.
What was Tata Steel India’s EBITDA per tonne in Q2 FY27?
India EBITDA was Rs 17,790 per tonne, down Rs 1,372 from Rs 19,162 in Q1, on EBITDA of Rs 10,634 crore and a 25% margin. Consolidated EBITDA per tonne was about Rs 13,466 (my calculation).
How did the Netherlands and UK do in Q2 FY27?
Netherlands EBITDA was about Rs 790 crore (€72 million) after the Direct Sheet Plant restarted in August, against €4 million in Q1. The UK lost about Rs 719 crore (£56 million), wider than £27 million in Q1.
What is Tata Steel’s net debt after Q2 FY27?
Net debt was Rs 91,423 crore, up Rs 7,250 crore from Rs 84,173 crore at 30 June (my calculation), and net debt to EBITDA was 2.4x. The reports I read do not explain the increase.
The results came on Saturday, 7 November, so no regular session has traded. The last price I found is Rs 181.20 on 6 November, before the results. The first chances are the Sunday Muhurat session and Monday, 9 November.
What are the brokerage targets for Tata Steel?
As reported by Business Today on 6 November, before the results: HDFC Securities Buy with a target of Rs 210 and HSBC Buy with Rs 260, both undated. I found no post-result target. These are brokerages’ views, not PositionalCalls targets.
Did Tata Steel declare a dividend with Q2 FY27 results?
None of the reports I opened mentions a dividend. Tata Steel’s recorded pattern is one final dividend a year, with Rs 4 per share for FY26. Confirm on the BSE or NSE announcement page.
When does Noel Tata retire from the Tata Steel board?
Business Standard and NewsBytes report the close of business on 11 November 2026; National Herald reports 12 November, when he turns 70. He is vice-chairman and a non-executive director. Confirm in the company’s filing.
Sources
- Business Standard, 7 November 2026 (consolidated, India, Netherlands, UK lines)
- ANI via The Tribune, 7 November 2026, 6:32 PM (India, Europe in currency, balance sheet)
- Investywise, 7 November 2026 (consolidated table, half-year, volumes)
- TradingView News, 7 November 2026 (Bloomberg consensus, Investec comment)
- Business Today, 6 November 2026 (estimates, brokerage views, price)
- NewsBytes, 7 November 2026 (gross debt, cash; revenue differs)
- Free Press Journal, 8 October 2026 (India volumes update of 7 October)
- National Herald, 28 October 2026 (Noel Tata retirement)
- Tata Steel press release, quarter ended 30 June 2026 (Q1 FY27 base)
- Tata Steel press release, quarter and half-year ended 30 September 2025 (Q2 FY26 base)
- BSE and NSE announcement pages and the Tata Steel press release: where the filing is published (I did not open them).
Disclosure: PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent Indian stock market research and education site founded by Shubham Chaudhary. This page is results analysis and not a recommendation, target or investment advice. How I researched this: I compared five press and data-platform reports of the filing, tied the half-year, India, currency and growth figures, recomputed every derived number, and listed the conflicts openly. I did not open the filing.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive