Earnings · TVS Motor
TVS Motor reported its September quarter on 28 October 2026 with record volumes, revenue and profit. Standalone profit grew faster than group profit, and several pages print half-year figures as quarterly ones. Here is what the numbers show and what to check.
Quick answer
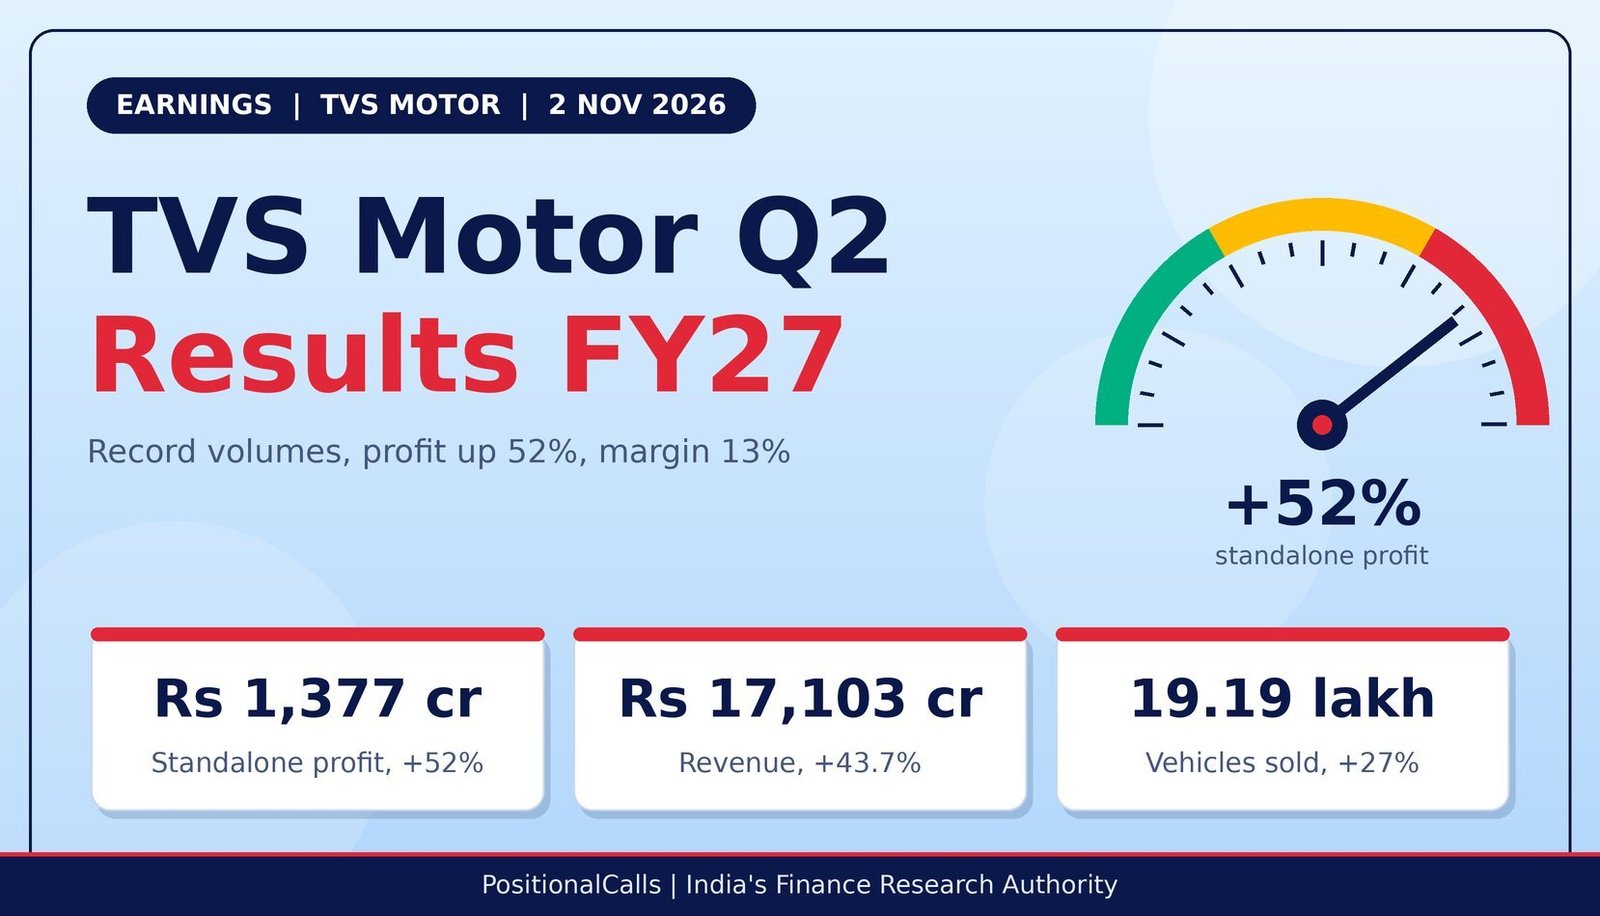
TVS Motor Q2 results FY27 show standalone net profit of Rs 1,377 crore, up 52.3%, on revenue of Rs 17,103 crore, up 43.7%, and a record 19.19 lakh vehicles. Consolidated profit rose 46.4% to Rs 1,219.45 crore. EBITDA margin was 13.0%. Profit was about in line with a Rs 1,370 crore poll. Results came on 28 October 2026.
Latest update (2 November 2026, 6:30 PM IST): TVS Motor’s results and earnings call took place on Wednesday, 28 October 2026. Reports differ on consolidated profit (Rs 1,219.45 crore against a provisional Rs 1,194.5 crore) and one results article prints half-year profit and EBITDA next to the quarterly headline.
Key takeaways
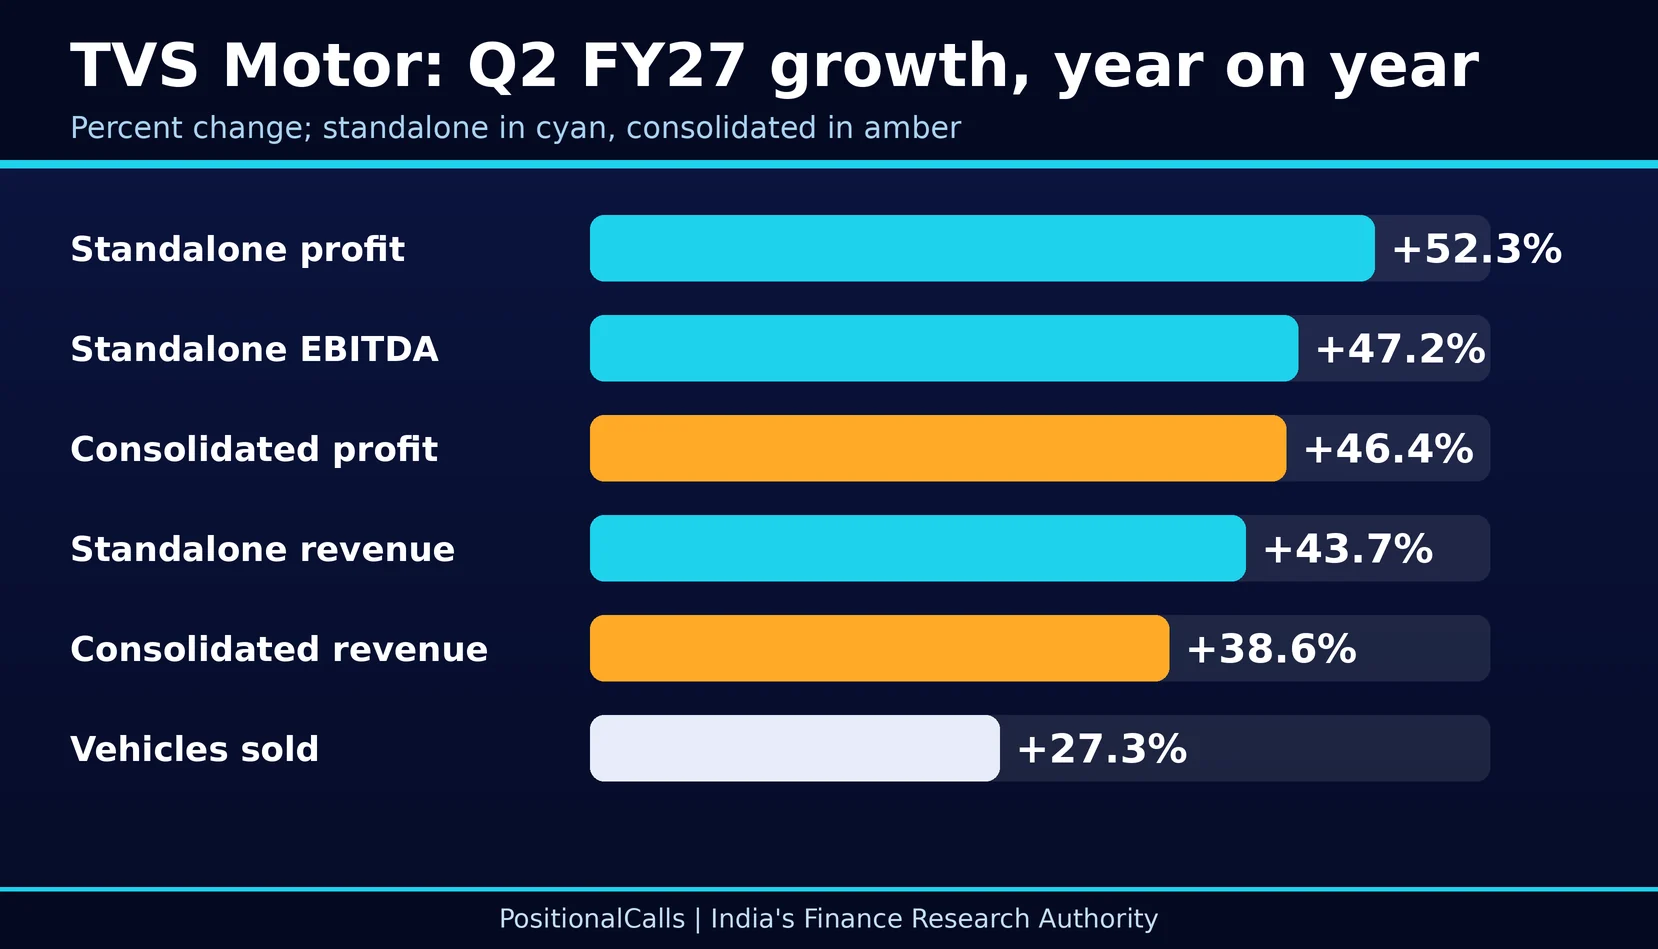
- Standalone: revenue Rs 17,103 crore (+43.7%); EBITDA Rs 2,219 crore (+47.2%); net profit Rs 1,377 crore (+52.3%).
- Consolidated: revenue Rs 19,474.44 crore (+38.6%); net profit Rs 1,219.45 crore (+46.4%).
- Volumes: 19.19 lakh vehicles (+27%), a record; international 5.39 lakh (+35%).
- Margin: EBITDA margin 13.0% against 12.7% a year earlier; the poll expected 13.2%.
- Trap: Rs 2,551 crore profit and Rs 3,998 crore EBITDA are half-year figures, not Q2.
In plain words: TVS Motor makes scooters, motorcycles, mopeds and three-wheelers and sells in India and abroad. “Standalone” is TVS Motor Company alone; “consolidated” adds subsidiaries such as its finance arm and overseas units. EBITDA is operating profit before interest, tax, depreciation and amortisation.
Data note: as of 2 November 2026, 6:30 PM IST. Figures follow TVS Motor’s results as carried by AutoCar Pro, CNBC-TV18, InCred Money, The People’s Board and Zee Business on 28 to 29 October 2026; I have not opened the exchange filing. Standalone and consolidated numbers are labelled. Derived numbers are marked “my calculation”.
What did TVS Motor report in the Q2 results FY27?
TVS Motor reported standalone revenue of Rs 17,103 crore, up 43.7%, EBITDA of Rs 2,219 crore, up 47.2%, and net profit of Rs 1,377 crore, up 52.3%, for the quarter ended 30 September 2026.
| Rs crore | Q2 FY27 | Q2 FY26 | Change | Scope |
|---|---|---|---|---|
| Revenue from operations | 17,103 | 11,905 | +43.7% | Standalone |
| EBITDA | 2,219 | 1,507 | +47.2% | Standalone |
| Profit before tax | 1,865 | 1,224 | +52.4% (my calculation) | Standalone |
| Net profit | 1,377 | 904 | +52.3% | Standalone |
| Revenue from operations | 19,474.44 | 14,051.22 | +38.6% | Consolidated |
| Net profit | 1,219.45 | 832.76 | +46.4% | Consolidated |
Cite this table: PositionalCalls, “TVS Motor Q2 FY27 Results Table, as of 2 November 2026”.
Every line grew by more than a third, which is unusual for a vehicle maker with a large base. The numbers are record highs for the company, as the earnings call summary puts it. Volumes grew about 27%, so revenue grew much faster than units, which is covered below. Always attach the scope, standalone or consolidated, to any TVS Motor figure.
Why is TVS Motor consolidated profit growth lower than standalone?
Because the gap between standalone and consolidated profit widened from about Rs 71 crore to about Rs 158 crore, so subsidiaries and associates took more out of group profit this year (my calculation).
| Rs crore | Q2 FY27 | Q2 FY26 | How derived |
|---|---|---|---|
| Standalone net profit | 1,377 | 904 | Reported |
| Consolidated net profit | 1,219.45 | 832.76 | Reported |
| Standalone less consolidated (my calculation) | about 158 | about 71 | Rounded reported figures |
| Standalone profit before tax | 1,865 | 1,224 | Reported |
| Consolidated profit before tax | 1,791 | 1,223 | Reported |
| Consolidated less standalone, PBT (my calculation) | −74 | −1 | Rounded reported figures |
| Growth: standalone / consolidated profit | +52.3% / +46.4% | Reported |
Cite this table: PositionalCalls, “TVS Motor Consolidated Versus Standalone Table, as of 2 November 2026”.
A year ago group profit before tax was almost identical to the parent’s. This quarter it was about Rs 74 crore lower, so the subsidiaries together reduced group profit before tax. The sources I saw do not say which subsidiary caused it. The earnings-call summary’s headline also mentions a consumer-finance demerger, but I did not find the details and do not describe it here. Check the filing’s segment and subsidiary notes.
Which TVS Motor numbers are quarterly and which are half-yearly? The definitions trap
One results article prints Rs 2,551 crore profit and Rs 3,998 crore EBITDA beside the Q2 headline; those are half-year totals, while the Q2 figures are Rs 1,377 crore and Rs 2,219 crore.
| Figure | Quarter (Q2 FY27) | Often shown as Q2 but actually | Source note |
|---|---|---|---|
| Net profit | Rs 1,377 crore (standalone) | Rs 2,551 crore (+52%), the H1 figure | H1 = Q1 about 1,174 + Q2 1,377 (my calculation) |
| EBITDA | Rs 2,219 crore (+47.2%) | Rs 3,998 crore (+44%), the H1 figure | H1 total |
| Revenue | Rs 17,103 crore (standalone) | Rs 30,999 crore (+41%), the H1 figure | H1 total |
| Consolidated profit | Rs 1,219.45 crore | Rs 1,194.5 crore, described as provisional | Use the higher, final-looking figure; check the filing |
| Profit growth | +52.3% (standalone) | +46.4% (consolidated) | Name the scope |
| Margin | 13.0% | 13.2% (previous quarter, as reported) | My derived Q1 margin is 12.8%; see below |
Cite this table: PositionalCalls, “TVS Motor Quarter Versus Half-Year Definitions Table, as of 2 November 2026”.
If you read the half-year profit of Rs 2,551 crore as the quarter, you will think profit nearly doubled the poll estimate. It did not. Q2 profit of Rs 1,377 crore was about in line with the Rs 1,370 crore poll. The same applies to the Rs 3,998 crore EBITDA figure, which is the half-year total. Before comparing any number with an estimate, check that both are for the same period.
Did TVS Motor beat estimates in Q2 FY27?
TVS Motor beat a CNBC-TV18 poll modestly: profit by 0.5%, revenue by 1.9% and EBITDA by 0.9%, while the 13.0% margin was 0.2 point below the 13.2% expected (my calculations).
| Item | Poll estimate (CNBC-TV18) | Reported (standalone) | Gap (my calculation) |
|---|---|---|---|
| Revenue | Rs 16,790 crore | Rs 17,103 crore | +1.9% |
| EBITDA | Rs 2,200 crore | Rs 2,219 crore | +0.9% |
| EBITDA margin | 13.2% | 13.0% | −0.2 point |
| Net profit | Rs 1,370 crore | Rs 1,377 crore | +0.5% |
Cite this table: PositionalCalls, “TVS Motor Estimate Versus Actual Table, as of 2 November 2026”.
The result was largely in line. It beat on volume-led revenue but not on margin. The poll is one source, not a verified consensus. Because standalone profit rose 52% against an estimate that already expected about 52%, the market was not surprised on profit; the debate is about margin and the consolidated line.
Was TVS Motor’s growth driven by volume or by price?
Both: units rose about 27.3% to 19.19 lakh and revenue per vehicle rose about 12.8% to roughly Rs 89,100, so price and mix added about as much as an extra third of volume growth (my calculations).
| Per-vehicle view (my calculation) | Q2 FY27 | Q2 FY26 | Change |
|---|---|---|---|
| Vehicles sold (lakh units) | 19.19 | 15.07 | +27.3% |
| Revenue per vehicle (Rs) | about 89,100 | about 79,000 | +12.8% |
| Standalone revenue (Rs crore) | 17,103 | 11,905 | +43.7% |
| Check: 1.273 × 1.128 | about 1.436 |
Cite this table: PositionalCalls, “TVS Motor Volume and Price Table, as of 2 November 2026”.
Revenue per vehicle is standalone revenue divided by total units, so it includes spares and other income and is an approximation. International sales were a record 5.39 lakh units, up 35%, as reported. The call summary says domestic electric two-wheelers grew about 129% against an industry rate of about 84%, and domestic scooters, motorcycles and three-wheelers all outgrew the industry. I did not verify the segment shares from the filing.
How did TVS Motor’s costs move?
Materials cost rose 45% to Rs 12,494 crore, slightly faster than revenue, while staff cost rose about 33% to Rs 806 crore, so margin gained only about 0.3 point.
| Cost line, standalone | Q2 FY27 | Share of revenue (my calculation) | Q2 FY26 share (my calculation) |
|---|---|---|---|
| Materials | Rs 12,494 crore (+45%) | 73.1% | 72.5% (Rs 8,627 crore) |
| Staff cost | Rs 806 crore (+33%) | 4.7% | 5.1% (about Rs 607 crore) |
| Other expenses | Rs 1,597 crore (+20%) | 9.3% | not computed |
| EBITDA | Rs 2,219 crore | 13.0% | 12.7% |
Cite this table: PositionalCalls, “TVS Motor Cost Table, as of 2 November 2026”.
The three cost lines add to about Rs 14,897 crore, which leaves Rs 2,206 crore against reported revenue; the remaining Rs 13 crore is other operating income (my calculation). Materials took a slightly larger share of revenue than a year ago, so the margin gain came from staff cost and other expenses growing more slowly than revenue. Each point of margin on Rs 17,103 crore is worth about Rs 171 crore, so the 0.3-point gain is worth about Rs 51 crore (my calculation).
PositionalCalls WhatsApp channel
Auto results, decoded in plain words
- TVS Motor and Bajaj Auto side by side
- Standalone and consolidated kept apart
- Quarter and half-year figures never mixed
What do the H1 FY27 numbers show?
H1 FY27 standalone revenue was Rs 30,999 crore, up 41%, EBITDA Rs 3,998 crore, up 44%, and net profit Rs 2,551 crore, up 52%, which implies Q1 profit of about Rs 1,174 crore (my calculation).
| Standalone, Rs crore | H1 FY27 | H1 FY26 | Change |
|---|---|---|---|
| Revenue from operations | 30,999 | 21,986 | +41.0% |
| EBITDA | 3,998 | not captured | +44% as reported |
| Net profit | 2,551 | 1,679 | +51.9% (my calculation) |
| Implied Q1 FY27 revenue (my calculation) | 13,896 | 30,999 less 17,103 | |
| Implied Q1 FY27 net profit (my calculation) | about 1,174 | 2,551 less 1,377 | |
| Implied Q1 FY27 EBITDA margin (my calculation) | about 12.8% | (3,998 less 2,219) / 13,896 |
Cite this table: PositionalCalls, “TVS Motor H1 FY27 Table, as of 2 November 2026”.
Q2 revenue was about 23% above the implied Q1 and net profit about 17% above (my calculations: 17,103 / 13,896 and 1,377 / 1,174). My implied Q1 margin of 12.8% is lower than the 13.2% that one report gives for the previous quarter, so either the half-year EBITDA uses a different basis or the report rounds differently. I flag the gap rather than choose one. Check the Q1 filing before quoting the margin trend.
One report says the shares rose as much as 4% on results day, and another shows Rs 4,241.90 at 10:38 AM on 29 October 2026; I have not verified closing prices.
These are intraday figures from third-party reports, not exchange closing records. The results were announced on 28 October and the call followed. A gain of up to 4% after a profit result that was in line with a poll shows how the market looked past profit to volumes and margin. Check the exchange for verified closes before drawing a conclusion.
How do TVS Motor’s results compare with Bajaj Auto’s?
TVS Motor grew faster than Bajaj Auto in revenue and profit, while Bajaj Auto earned a much higher EBITDA margin, 20.9% against 13.0%.
| Standalone, Q2 FY27 | TVS Motor | Bajaj Auto |
|---|---|---|
| Revenue from operations | Rs 17,103 crore (+43.7%) | Rs 20,003 crore (+34.1%) |
| EBITDA margin | 13.0% (12.7% a year earlier) | 20.9% (20.5% a year earlier) |
| Net profit | Rs 1,377 crore (+52.3%) | Rs 3,354 crore (+35.3%) |
| Vehicles sold | 19.19 lakh (+27%) | 15.49 lakh (+20%) |
| Consolidated profit growth | +46.4% | +62% |
| Our page | This page | Bajaj Auto Q2 results FY27 |
The comparison shows two different models: TVS sells more vehicles at a lower margin, Bajaj sells fewer at a higher margin. For other auto results see Maruti Suzuki Q2 results FY27, M&M Q2 results FY27 (5 November 2026), Eicher Motors Q3 results and the auto category.
What should you check in the TVS Motor filing?
Read the subsidiary and segment notes first, then the consolidated profit line, then the quarterly margin trend, then the volumes split, because reports are thin on each.
| What to read | Reported mark | Question to ask |
|---|---|---|
| Subsidiary and associate contribution | Gap about Rs 158 crore vs Rs 71 crore | Which unit caused the drag? |
| Consolidated profit | Rs 1,219.45 crore (one page: Rs 1,194.5 crore) | Which figure is final? |
| Quarterly EBITDA margin | 13.0% against 13.2% reported for Q1 (my Q1: 12.8%) | What is the correct Q1 base? |
| Domestic versus international volumes | International 5.39 lakh, +35% | What is the split by product? |
| Cost lines | Materials +45%; staff +33% | Is the materials share a trend? |
| Exceptional items | None seen | Any one-off in the notes? |
Cite this table: PositionalCalls, “TVS Motor Filing Checklist, as of 2 November 2026”.
What do most people miss about the TVS Motor Q2 results FY27?
Most miss that half-year figures are printed as quarterly ones, that group profit grew slower than the parent’s, and that profit was only in line with the poll.
- Name the scope, standalone or consolidated, with every number.
- Match the period: quarter with quarter, never with the half-year.
- Compare Q2 FY27 with Q2 FY26 first, then with Q1 FY27.
- Check the subsidiary notes for the consolidated gap.
- Verify closing prices on the exchange before quoting a share-price move.
What do you need to know about costs, tax and safety?
Trading costs and your holding period matter more than one quarter’s headline; never pay anyone for results alerts or tips.
- What you need: a demat and trading account; settlement is T+1.
- Costs: check your broker’s current charge schedule for brokerage, securities transaction tax, GST and stamp duty on each trade.
- Tax angle: gains on shares are taxed by holding period; see capital gains tax on shares and ask a tax adviser if unsure.
- NRI note: see NRI investment in the Indian stock market.
- Scam warning: fake results alerts, paid “sure-shot” tips and KYC links on messaging apps are common. Never share an OTP.
Analyst’s note
- What stands out: in the TVS Motor Q2 results FY27, revenue grew 43.7% on 27% more vehicles, so price and mix did a lot of the work.
- Easy to miss: the drag between standalone and consolidated profit more than doubled, so the group lagged the parent for the first time in this comparison.
- What would change the view: a quarterly margin below 13% with the subsidiary drag persisting would show the group story weakening.
- Caution: this is reasoning from reported numbers, not a forecast or advice. No outcome is assured.
- Reader action: read the subsidiary notes and match the period before quoting a number.
Bottom line
TVS Motor Q2 results FY27: standalone profit Rs 1,377 crore (+52.3%) on revenue of Rs 17,103 crore (+43.7%), consolidated profit Rs 1,219.45 crore (+46.4%), a record 19.19 lakh vehicles and a 13.0% margin. Results were about in line with a poll. Confirm the figures and the subsidiary drivers in the filing.
Next read: Bajaj Auto Q2 results FY27: profit, margin and exports
Part of the Auto earnings series. See also the Maruti Suzuki Q2 results FY27 page.
PositionalCalls WhatsApp channel
Auto results, without the noise
- TVS Motor, Bajaj Auto and M&M side by side
- Plain-language summaries of each filing
- Corrections flagged the moment numbers change
Frequently asked questions
What are the TVS Motor Q2 results FY27?
TVS Motor reported standalone revenue of Rs 17,103 crore (+43.7%), EBITDA of Rs 2,219 crore (+47.2%) and net profit of Rs 1,377 crore (+52.3%) for Q2 FY27, on 28 October 2026. Consolidated net profit was Rs 1,219.45 crore (+46.4%).
Why is TVS Motor consolidated profit growth lower than standalone?
Consolidated profit rose 46.4% against 52.3% standalone because the gap between the two widened from about Rs 71 crore to about Rs 158 crore (my calculation). The reasons are in the subsidiary notes of the filing.
Is Rs 2,551 crore the TVS Motor Q2 profit?
No. Rs 2,551 crore is the H1 FY27 profit, up 52%, and Rs 3,998 crore is the H1 EBITDA. The Q2 figures are Rs 1,377 crore and Rs 2,219 crore. One results article prints the half-year figures beside the quarterly headline.
Did TVS Motor beat Q2 estimates?
Only modestly. Against a CNBC-TV18 poll, profit was 0.5% above Rs 1,370 crore, revenue 1.9% above and EBITDA 0.9% above, while the 13.0% margin was below the 13.2% expected (my calculations). The poll is not a verified consensus.
What was TVS Motor EBITDA margin in Q2 FY27?
The standalone EBITDA margin was 13.0%, against 12.7% a year earlier. One report gives 13.2% for the previous quarter, but my half-year calculation implies about 12.8%, so check the Q1 filing before comparing.
How many vehicles did TVS Motor sell in Q2 FY27?
TVS Motor sold 19.19 lakh vehicles, up about 27% from 15.07 lakh, a record. International sales were 5.39 lakh units, up 35%. Revenue per vehicle rose about 12.8% (my calculation).
How did TVS Motor compare with Bajaj Auto in Q2 FY27?
TVS grew faster (revenue +43.7%, profit +52.3%) but earned a lower margin (13.0% against 20.9%). Bajaj Auto’s standalone profit was Rs 3,354 crore and its consolidated profit rose about 62%.
One report says the shares rose as much as 4% on results day and another shows Rs 4,241.90 at 10:38 AM on 29 October 2026. These are intraday figures; check the exchange for verified closing prices.
What drove TVS Motor costs in Q2 FY27?
Materials cost rose 45% to Rs 12,494 crore, slightly faster than revenue, while staff cost rose about 33% to Rs 806 crore. Together with other expenses these leave EBITDA of about Rs 2,206 crore (my calculation), close to the reported Rs 2,219 crore.
Where do I check the official TVS Motor results?
Open the NSE or BSE announcements for TVSMOTOR or the investor page at tvsmotor.com. Reports mix standalone, consolidated and half-year figures, so use the filing as the final source.
Sources
- TVS Motor Company Limited results announcement and board outcome, 28 October 2026 (NSE and BSE)
- AutoCar Pro, CNBC-TV18, InCred Money, The People’s Board, GuruFocus call summary and Zee Business reports, 28 to 29 October 2026 (secondary, not linked)
Editorial disclosure. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. This page is educational, is independent and was written by Shubham Chaudhary, founder of PositionalCalls. How I researched this: I compared results reports of the company filing, separated quarterly and half-year figures, recomputed every derived number and labelled conflicting figures. Corrections are published in the Data note.
Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive