
Earnings · Commercial vehicles
Looking for Ashok Leyland Q2 results FY27? The board met on Saturday 14 November 2026. This page sets out what was reported, which profit figure belongs to which basis, why margin fell while volume and revenue jumped, what the finance subsidiary and the audit disclaimer mean, and what the dividend is. It gives no rating, target or price view.
Quick answer
Ashok Leyland Q2 results FY27 show consolidated profit of Rs 891.45 crore, up 8.8%, and standalone profit of Rs 869.02 crore, up 12.7%, on revenue up 35% to 39%. Standalone EBITDA margin fell to 10.1% from 12.1%. A Re 1 interim dividend was declared. Auditors disclaimed a conclusion on the consolidated results. This page names no stock.
Latest update (Sunday, 15 November 2026, 6:49 AM IST): Built from press reports of the 14 November filing (Autocar Professional, Multibagg, Investywise, NewsBytes). I did not open the exchange filing. Press reports differ on the year-ago consolidated profit (Rs 819.70 crore or Rs 820 crore) and on how margin is defined. No share price reaction, because the first trading session after the result is Monday 16 November. The earlier date page is linked at the end.
Key takeaways
- Two profits, two bases: consolidated profit was Rs 891.45 crore (+8.8% from Rs 819.70 crore) and standalone profit was Rs 869.02 crore (+12.7% from Rs 771.06 crore), so the headline depends on which one a report quotes.
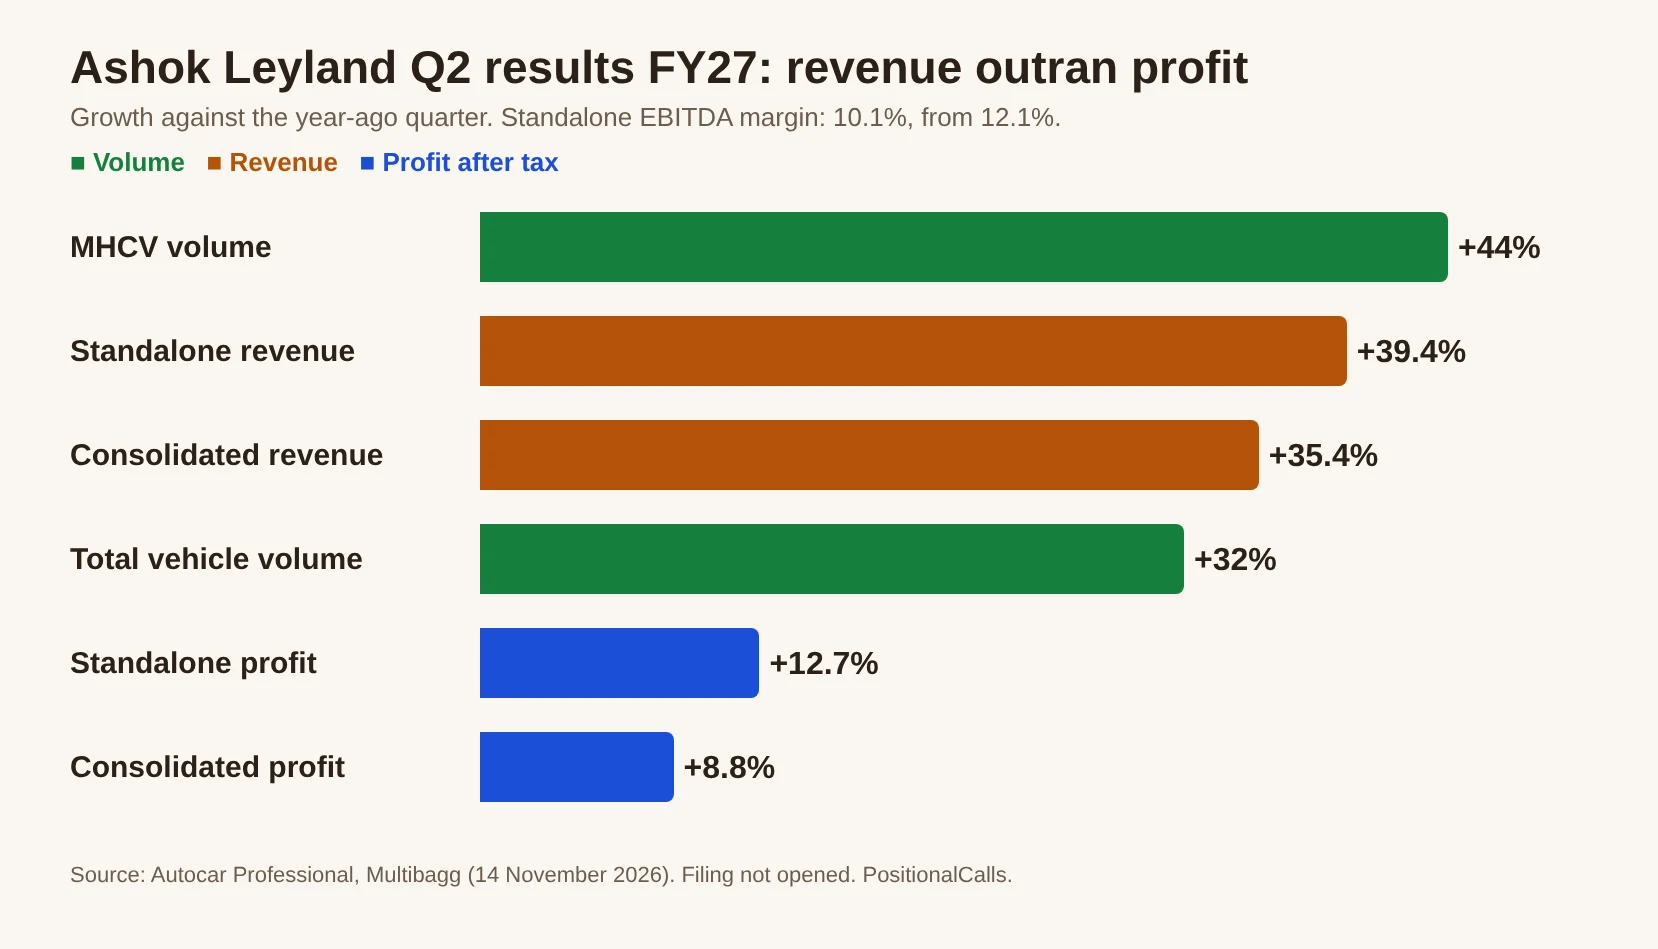
- Revenue and volume jumped: standalone revenue was Rs 13,364.28 crore (+39.4%), consolidated revenue Rs 17,029.87 crore (+35.4%), and commercial vehicle volume 64,677 units (+32%).
- Margin fell: standalone EBITDA margin was 10.1% against 12.1% a year earlier, because materials cost rose 46.6% against revenue up 39.4%.
- Finance arm weaker: Hinduja Leyland Finance segment profit fell 28.1% to Rs 153.27 crore, with impairment charges up 34.2% to Rs 463.48 crore.
- Audit caveat: auditors gave an unmodified conclusion on standalone results but disclaimed a conclusion on consolidated results because of unresolved loan-balance differences at the subsidiary; the impact is not yet determined.
- Dividend: Re 1 interim per share, record date 20 November, payment on or before 13 December. By my calculation it is about Rs 587 crore, about 68% of standalone quarterly profit.
In plain words: Ashok Leyland sold far more trucks and vans, so revenue rose about 35% to 39%, but its profit grew only 9% to 13% because materials cost more. Its loan arm earned less, and the auditors could not give a clean opinion on the group figures. The company declared a Re 1 dividend.
Data note: Figures are for the quarter ended 30 September 2026, per Autocar Professional (14 November), Multibagg, Investywise and NewsBytes. I did not open the exchange filing. Derived numbers are my calculation. Consolidated and standalone figures are labelled. No consensus estimate, order book or numeric guidance was found.
1. What did Ashok Leyland report in its Q2 results FY27?
Ashok Leyland Q2 results FY27 reported consolidated revenue of Rs 17,029.87 crore (+35.4%), consolidated profit of Rs 891.45 crore (+8.8%), standalone profit of Rs 869.02 crore (+12.7%), 64,677 vehicles sold (+32%) and a Re 1 interim dividend.
| Item | Consolidated | Standalone |
|---|---|---|
| Revenue from operations | Rs 17,029.87 crore (+35.4% from Rs 12,576.86 crore) | Rs 13,364.28 crore (+39.4% from Rs 9,588.18 crore) |
| Profit before tax | Rs 1,287.16 crore (+14.5%) | Rs 1,187.27 crore (+13.9%) |
| Profit after tax | Rs 891.45 crore (+8.8% from Rs 819.70 crore) | Rs 869.02 crore (+12.7% from Rs 771.06 crore) |
| Earnings per share | Rs 1.43 (+10.9% from Rs 1.29) | Rs 1.48 (+13%) |
| Operating margin | 6.5% against 8.1% (Multibagg; operating profit Rs 1,114.3 crore, +9.1%) | EBITDA about Rs 1,350 crore (+about 16%); 10.1% against 12.1% |
| Auditor conclusion | Disclaimed | Unmodified |
Cite this table: Ashok Leyland Q2 FY27 per Autocar Professional (14 November 2026) and Multibagg; the filing was not opened; the consolidated margin definition differs from the standalone EBITDA margin.
The board approved the results on Saturday 14 November 2026. The earlier earlier Ashok Leyland date page held the date and the year-ago base. This page holds the result. For how Ashok Leyland compares with other makers, see my auto sector earnings page.
Ashok Leyland Q2 results FY27 against the year-ago base
The year-ago standalone base is revenue of Rs 9,588.18 crore and profit of Rs 771.06 crore, which matches the figures on my date page. The consolidated year-ago profit is Rs 819.70 crore in Autocar Professional and about Rs 820 crore in Multibagg, which is rounding. Press reports of last year’s results gave other profit figures, such as Rs 755.77 crore from a results table, so I use the figures quoted in this year’s reports and say which basis I used.
2. Why Ashok Leyland Q2 results FY27 show two profit figures
Ashok Leyland Q2 results FY27 give two profit figures because standalone covers the parent company and consolidated adds subsidiaries such as Hinduja Leyland Finance, so Rs 869.02 crore (+12.7%) and Rs 891.45 crore (+8.8%) are both correct on their own bases.
| Basis | Profit after tax | Year-ago | Change | What it covers |
|---|---|---|---|---|
| Standalone | Rs 869.02 crore | Rs 771.06 crore | +12.7% | The parent company; vehicles business |
| Consolidated | Rs 891.45 crore | Rs 819.70 crore | +8.8% | Parent plus subsidiaries, including the finance arm |
Cite this table: Per Autocar Professional and Multibagg; filing not opened.
Revenue growth also differs: standalone revenue rose 39.4% and consolidated revenue 35.4%, because the finance arm grew more slowly (revenue +15.7%). One press report gave the standalone profit as Rs 869 crore, up 13%, without saying which basis; another headline described the profit as Rs 891 crore. Use the basis that matches what you are comparing. The auditors’ conclusion also differs by basis, which section 5 covers.
Where the sources disagree on this result
- Consolidated profit growth: +8.8% from Rs 819.70 crore (Autocar Professional) against +8.7% from about Rs 820 crore (Multibagg), a rounding gap.
- Year-ago volume: 49,116 units in the result against 48,788 in my date page, which I summed from product lines; I use 49,116.
- Margin: standalone EBITDA margin of 10.1% against a consolidated operating margin of 6.5%, which are different measures on different bases, not a conflict.
- Volume total: MHCV 37,958, LCV 21,371 and exports 5,102 sum to 64,431, which is 246 units short of the 64,677 total; I could not identify the remaining category (my calculation).
3. Revenue and volume in Ashok Leyland Q2 results FY27
Ashok Leyland Q2 results FY27 show commercial vehicle volume up 32% to 64,677 units, with medium and heavy vehicles up 44% against an industry rise of 39%, and a domestic truck market share of 31.5%, up 1.5 percentage points.
| Segment | Q2 FY27 | Change | Comparison |
|---|---|---|---|
| Total commercial vehicles | 64,677 units | +32% | 49,116 a year earlier |
| Medium and heavy (MHCV) | 37,958 units | +44% | Industry +39% |
| Domestic MHCV trucks | Not stated | +48% | Industry +41% |
| Light commercial (LCV) | 21,371 units | +21% | 17,697 a year earlier |
| Exports | 5,102 units | +7% | About 4,784 a year earlier |
| Domestic truck market share (excluding defence) | 31.5% | +1.5 points | Company figure |
| LCV share (VAHAN, addressable segments) | 13.6% | +0.3 points | Company figure |
| Buses | Market share held | Not stated | Excluding electric buses |
Cite this table: Volumes and market shares per Autocar Professional and Multibagg, quoting the company; filing not opened; the year-ago exports figure is from my date page.
Volume rose faster than the industry in medium and heavy trucks, which is the company’s core segment. Standalone revenue grew faster than volume (39.4% against 32%), which suggests a richer mix or higher realisations, but I found no average realisation or mix figure to confirm it. Exports were the slowest line at 7%. September sales had been strong, as my date page recorded, so the quarter’s volume was not a surprise to anyone tracking monthly data. For the previous year’s results, see my Ashok Leyland Q3 results.
4. Margin and costs in Ashok Leyland Q2 results FY27
Ashok Leyland Q2 results FY27 show standalone EBITDA of about Rs 1,350 crore, up about 16%, but margin fell to 10.1% from 12.1% because materials cost rose 46.6% while standalone revenue rose 39.4%.
| Standalone cost line | Q2 FY27 change | Comparison |
|---|---|---|
| Revenue from operations | +39.4% | Rs 13,364.28 crore |
| Cost of materials consumed | +46.6% | Faster than revenue |
| Other expenses | +35.8% | Slower than revenue |
| Employee costs | +9.5% | Slower than revenue |
| Other income | -51.8% | Rs 64.94 crore |
| EBITDA | About +16% | About Rs 1,350 crore |
| EBITDA margin | 10.1% | 12.1% a year earlier (-2.0 points) |
Cite this table: Cost changes per Autocar Professional; materials share of sales for Q2 not found; filing not opened.
| Standalone quarter | Revenue | EBITDA margin | Profit after tax |
|---|---|---|---|
| Q2 FY26 | Rs 9,588.18 crore | 12.1% | Rs 771.06 crore |
| Q1 FY27 | Rs 9,634.35 crore | 10.1% | Rs 609.11 crore |
| Q2 FY27 | Rs 13,364.28 crore | 10.1% | Rs 869.02 crore |
Cite this table: Q2 FY26 and Q1 FY27 per my date page and Autocar Professional/Kotak Neo as recorded there; Q2 FY27 per Autocar Professional; filing not opened.
Compared with the previous quarter, standalone revenue rose about 38.7% and profit about 42.7% (my calculation), while the margin was flat at 10.1%. So the year-on-year margin fall had already happened in Q1 and did not widen in Q2. The company says it has recorded double-digit EBITDA margins for 15 consecutive quarters, which holds at 10.1%. Other income more than halved, which cut profit growth below the EBITDA growth. I found no company explanation of the materials cost rise and no raw-material price breakdown, so I do not say why costs moved. For the same cost pressure elsewhere in autos, see the auto sector earnings page and the Eicher Motors Q2 results FY27.
5. The finance arm and the audit caveat in Ashok Leyland Q2 results FY27
Ashok Leyland Q2 results FY27 include a finance arm whose segment profit fell 28.1% to Rs 153.27 crore, and the auditors disclaimed a conclusion on the consolidated results because of unresolved loan-balance differences at Hinduja Leyland Finance.
| Consolidated segment or line | Q2 FY27 | Change |
|---|---|---|
| Commercial vehicles: revenue | Rs 14,746.97 crore | +39.1% |
| Commercial vehicles: segment profit before interest and tax | Rs 1,084.26 crore | +18.8% |
| Financial services: revenue | Rs 2,283.74 crore | +15.7% |
| Financial services: segment profit | Rs 153.27 crore | -28.1% |
| Finance costs (consolidated) | Rs 1,343.64 crore | +16.6% |
| Impairment loss allowance and write-offs (financing) | Rs 463.48 crore | +34.2% |
| Profit before tax (consolidated) | Rs 1,287.16 crore | +14.5%; +10.6% before a Rs 40 crore year-ago exceptional charge |
Cite this table: Segment and cost data per Autocar Professional; filing not opened; the effect of the exceptional charge on growth is as stated by the source.
What the auditors said about the consolidated Ashok Leyland Q2 results
Per Autocar Professional and Multibagg, the auditors gave an unmodified conclusion on the standalone results and disclaimed a conclusion on the consolidated results. The reason given is unresolved loan-balance reconciliation differences at Hinduja Leyland Finance. The financial impact is yet to be determined. The company says the differences are unlikely to materially affect the subsidiary’s financial health or its ability to service debt. That statement is the company’s, and the amounts of the differences were not in the reports I read.
PositionalCalls WhatsApp channel
Follow auto results plainly
- Result summaries without tips
- Margin and volume checks
- A message when this page is updated
This matters for how to read the page. The standalone figures, which carry the clean conclusion, are the safer basis for the vehicles business. The consolidated profit of Rs 891.45 crore includes the finance arm, and the auditors could not conclude on it. A disclaimer is not the same as saying the numbers are wrong, and I do not say they are. It means the auditors could not gather enough evidence to give a view. Read the notes in the exchange filing, which I did not open, for the size of the differences and the next steps. I also do not infer a link between the weaker finance profit and the audit matter, because no source made one.
6. Cash and the dividend in Ashok Leyland Q2 results FY27
Ashok Leyland Q2 results FY27 declared a Re 1 interim dividend per share with a record date of 20 November 2026 and payment on or before 13 December, and standalone net cash was Rs 3,546 crore against Rs 990 crore a year earlier.
| Item | Detail | Note |
|---|---|---|
| Interim dividend | Re 1 per share (100% of Re 1 face value) | Per Autocar Professional and Investywise |
| Record date | 20 November 2026 | Per the same reports |
| Payment | On or before 13 December 2026 | Per the same reports |
| Estimated outgo | About Rs 587 crore | My calculation: standalone profit Rs 869.02 crore divided by EPS Rs 1.48 gives about 587 crore shares |
| Share of standalone Q2 profit | About 68% | My calculation; EPS is rounded, so approximate |
| Net cash (standalone) | Rs 3,546 crore against Rs 990 crore a year earlier | Q1 FY27: Rs 2,252 crore; March 2026: Rs 5,899 crore per my date page |
| Last year | Re 1 interim for Q2 FY26 (paid by December 2025) | Per my date page |
Cite this table: Dividend and cash data per Autocar Professional, Investywise and my date page; the share count is inferred from EPS and is approximate; filing not opened.
The interim dividend is the same Re 1 as a year earlier. Net cash rose from Q1 (Rs 2,252 crore) to Rs 3,546 crore, but it is below the Rs 5,899 crore at March 2026, so cash has moved within a wide range. I found no explanation for the swings, so I do not give one. The record date decides who receives the dividend, and dividends are taxed in the shareholder’s hands; see my dividend tax in India guide. If you sell shares, see my capital gains tax on shares guide.
7. Half-year and quarterly view of Ashok Leyland Q2 results FY27
In the first half of FY27, Ashok Leyland standalone revenue rose 25.6% and profit 8.3% to Rs 1,478.12 crore, while consolidated revenue rose 23.9% to Rs 30,099.46 crore and profit 5.5% to Rs 1,559.22 crore.
| H1 FY27 | Standalone | Consolidated |
|---|---|---|
| Revenue | +25.6% | Rs 30,099.46 crore (+23.9%) |
| Profit before tax | Not stated | Rs 2,236.88 crore (+11%) |
| Profit after tax | Rs 1,478.12 crore (+8.3%) | Rs 1,559.22 crore (+5.5%) |
Cite this table: Half-year data per Autocar Professional; filing not opened.
The half-year shows the same pattern as the quarter: revenue growth of about a quarter and profit growth well below it. Q2 was the stronger quarter, since Q1 profit growth was only 2.5% standalone, per my date page. The comparison year-ago base for Q2 FY26 is a stronger base than the one a year earlier.
The preview figures against the Q2 FY27 result
| Item | Held on the earlier date page | Q2 FY27 result | Change (my calculation) |
|---|---|---|---|
| Standalone revenue, year-ago base | Rs 9,588.18 crore | Rs 13,364.28 crore | +39.4%, as reported |
| Standalone profit, year-ago base | Rs 771 crore | Rs 869.02 crore | +12.7%, as reported |
| Previous quarter (Q1 FY27) revenue | Rs 9,634.35 crore | Rs 13,364.28 crore | +38.7% on the quarter |
| Previous quarter (Q1 FY27) profit | Rs 609.11 crore | Rs 869.02 crore | +42.7% on the quarter |
| Previous quarter volume | 48,763 units | 64,677 units | +32.6% on the quarter |
| Previous quarter margin | 10.1% | 10.1% | Flat |
| September 2026 sales (one source) | About 21,105 units, +30.17%; domestic MHCV 12,724 (+44%) | 64,677 for the quarter | September alone was about a third of the quarter |
Cite this table: Preview figures per my earlier date page, which cited Autocar Professional, Kotak Neo and TractorJunction; result per Autocar Professional; the September figure is a single source and may not tie to the quarter; the filing was not opened.
Two points stand out. Volume and revenue rose by about a third from the previous quarter, which is a large step for a single quarter, while margin did not change. That means the extra revenue brought extra profit at the same margin. The September monthly data had already pointed to strong demand, with medium and heavy trucks up 44% in the domestic market, which matches the 44% quarterly rise in that segment. I did not find a company explanation for why the quarter stepped up so sharply, such as festive demand or pre-buying, so I do not give one.
8. What is not known about Ashok Leyland Q2 results FY27
The reports do not give a consensus estimate, an order book, numeric guidance, the size of the Hinduja Leyland Finance differences, a materials cost breakdown or any share price reaction, so those cannot be assessed from this page.
| Missing item | Why it matters | When it may appear |
|---|---|---|
| Share price reaction | Shows how the market read the margin and the audit caveat | Monday 16 November is the first session after the result; I will not guess it |
| Size of loan-balance differences | Decides whether the consolidated profit changes | In the filing notes or later disclosures; I did not open the filing |
| Consensus estimate | Needed to say if the result beat or missed | Not found; no analyst target is used |
| Materials cost explanation | Explains the 2-point margin fall | Possibly on the earnings call; no transcript found |
| Guidance or order commentary | Shows what management expects next | Not in the reports I read |
| Electric bus and Switch Mobility numbers | The chairman said they are progressing well, with no figures | Not found |
Cite this table: Gap list by PositionalCalls; nothing here is a forecast.
Per Autocar Professional, management cited market share gains, new products in tippers, buses, haulage and LCVs, and distribution expansion ahead of plan. Those are the company’s statements, not findings. For the price context before the result, see my earlier Ashok Leyland date page.
9. What are the risks around Ashok Leyland Q2 results FY27?
The main risks around Ashok Leyland Q2 results FY27 are the audit disclaimer on the consolidated results, the lower finance profit with higher impairment, a margin below last year, and the cyclical nature of commercial vehicle demand.
10. What most people miss in Ashok Leyland Q2 results FY27, and how to check
- What stands out: revenue rose 35% to 39% and volume 32%, but profit rose only 8.8% to 12.7%.
- Easy to miss: the auditors disclaimed a conclusion on the consolidated results, so the Rs 891 crore headline is on a basis they could not conclude on.
- Also easy to miss: the margin was 10.1% in both Q1 and Q2, so the year-on-year fall came from a strong year-ago base.
- Caution: this page does not say whether the result is good for the share price, and no price reaction is available.
- Choose the basis: compare standalone with standalone and consolidated with consolidated.
- Read the audit report: open the exchange filing and read the disclaimer and its notes.
- Check volume against revenue: revenue +39.4% on volume +32% suggests mix or price, which the reports do not break out.
- Check the margin trend: compare Q2 FY26 (12.1%), Q1 FY27 (10.1%) and Q2 FY27 (10.1%).
- Check the finance arm: segment profit, impairment and finance costs.
- Check the dividend dates: record date 20 November, payment by 13 December.
- Check the price separately: use exchange prices after the Monday session; this page has none.
- Plan the tax: see my dividend tax in India guide and capital gains tax on shares guide.
For the wider picture see my auto sector outlook 2026 and auto sector earnings page.
Bottom line
The Q2 FY27 result shows revenue up 35% to 39% and volume up 32%, but profit up only 8.8% (consolidated) and 12.7% (standalone) as margin fell to 10.1%. The finance arm earned 28.1% less, the auditors disclaimed a conclusion on the consolidated results, and a Re 1 interim dividend was declared. Read the filing, and check the price after Monday.
Next read: see the earlier Ashok Leyland date page.
Part of the Earnings series on PositionalCalls.
PositionalCalls WhatsApp channel
Keep the Ashok Leyland data in one place
- Updates after the price reaction
- Dividend and record dates
- Updates when new filings are out
FAQs on Ashok Leyland Q2 results FY27
What were the Ashok Leyland Q2 results FY27?
Consolidated revenue was Rs 17,029.87 crore, up 35.4%, and consolidated profit was Rs 891.45 crore, up 8.8%. Standalone revenue was Rs 13,364.28 crore, up 39.4%, and standalone profit Rs 869.02 crore, up 12.7%. Commercial vehicle volume was 64,677 units, up 32%. A Re 1 interim dividend was declared. Figures are per press reports; the filing was not opened.
What was Ashok Leyland standalone and consolidated profit in Q2 FY27?
Standalone profit was Rs 869.02 crore against Rs 771.06 crore, up 12.7%. Consolidated profit was Rs 891.45 crore against Rs 819.70 crore, up 8.8%. Consolidated includes subsidiaries such as Hinduja Leyland Finance. Press reports sometimes quote one without naming the basis, so check which one a headline uses when you compare them.
Why did Ashok Leyland margin fall in Q2 FY27?
Standalone EBITDA margin was 10.1% against 12.1% a year earlier. Materials cost rose 46.6% while revenue rose 39.4%, and other income fell 51.8%. The margin was also 10.1% in Q1 FY27, so the fall came against a stronger year-ago base. I found no company explanation of the materials cost, so I do not state a cause.
How many vehicles did Ashok Leyland sell in Q2 FY27?
Total commercial vehicle sales were 64,677 units, up 32% from 49,116. Medium and heavy vehicles were 37,958 units, up 44% against an industry rise of 39%. Light commercial vehicles were 21,371, up 21%, and exports 5,102, up 7%. The three lines sum to 64,431, so about 246 units sit in a category I could not identify.
What did auditors say about the Ashok Leyland Q2 results?
The auditors gave an unmodified conclusion on the standalone results and disclaimed a conclusion on the consolidated results, because of unresolved loan-balance reconciliation differences at Hinduja Leyland Finance. The financial impact is yet to be determined, and the company says the differences are unlikely to affect the subsidiary’s financial health materially. I did not open the filing, so I cannot give the size.
What is the Ashok Leyland dividend for Q2 FY27?
The board declared an interim dividend of Re 1 per share, 100% of the Re 1 face value. The record date is 20 November 2026, and payment is on or before 13 December 2026. By my calculation the outgo is about Rs 587 crore, roughly 68% of standalone quarterly profit. The share count is inferred from EPS, so the figure is approximate.
How did the Hinduja Leyland Finance arm do in Ashok Leyland Q2 results?
Financial services revenue rose 15.7% to Rs 2,283.74 crore, but segment profit fell 28.1% to Rs 153.27 crore. Consolidated finance costs rose 16.6% to Rs 1,343.64 crore, and impairment charges and write-offs on financing rose 34.2% to Rs 463.48 crore. I found no source linking these changes to the audit matter, so I do not make that link.
How did Ashok Leyland do in the first half of FY27?
Standalone revenue rose 25.6% and profit rose 8.3% to Rs 1,478.12 crore. Consolidated revenue rose 23.9% to Rs 30,099.46 crore, profit before tax rose 11% to Rs 2,236.88 crore, and profit after tax rose 5.5% to Rs 1,559.22 crore. These are press figures, and the filing was not opened. The Q2 profit growth was stronger than Q1’s.
Did the Ashok Leyland Q2 results beat estimates?
I cannot say. I found no consensus estimate, and I do not use analyst targets. The result can be compared only with the year-ago base: revenue and volume rose sharply, and profit rose less because margin fell. The share price reaction is not available, since Monday 16 November is the first trading session after the Saturday result.
What should I check next on the Ashok Leyland Q2 results?
Read the exchange filing for the audit disclaimer and the size of the loan-balance differences, check the margin trend over three quarters, and look at the finance arm’s impairment charges. Check the dividend dates before 20 November. This page gives no rating or target, and a registered adviser can advise on your own position.
Sources
- Autocar Professional: Ashok Leyland Q2 consolidated revenue jumps 35% to Rs 17,030 crore; main source for results, segments, volumes and the audit caveat, 14 November 2026.
- Multibagg: Ashok Leyland Q2 FY27 profit rises 8.7% to Rs 891 crore; consolidated and standalone figures, operating margin.
- Investywise: Ashok Leyland announces results and interim dividend; dividend, record and payment dates.
- NewsBytes: Ashok Leyland posts Rs 869 crore Q2 FY27 profit; standalone profit and volumes.
- PositionalCalls: earlier Ashok Leyland date page (date, year-ago base, Q1 FY27 data).
- PositionalCalls: Auto sector earnings Q2 FY27 (other makers).
- BSE India: exchange filings; the filing for this result was not opened.
- NSE India: exchange announcements and corporate filings.
- I opened no BSE or NSE filing, no earnings call transcript and no analyst report for this page.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive