Earnings · Building materials · Astral
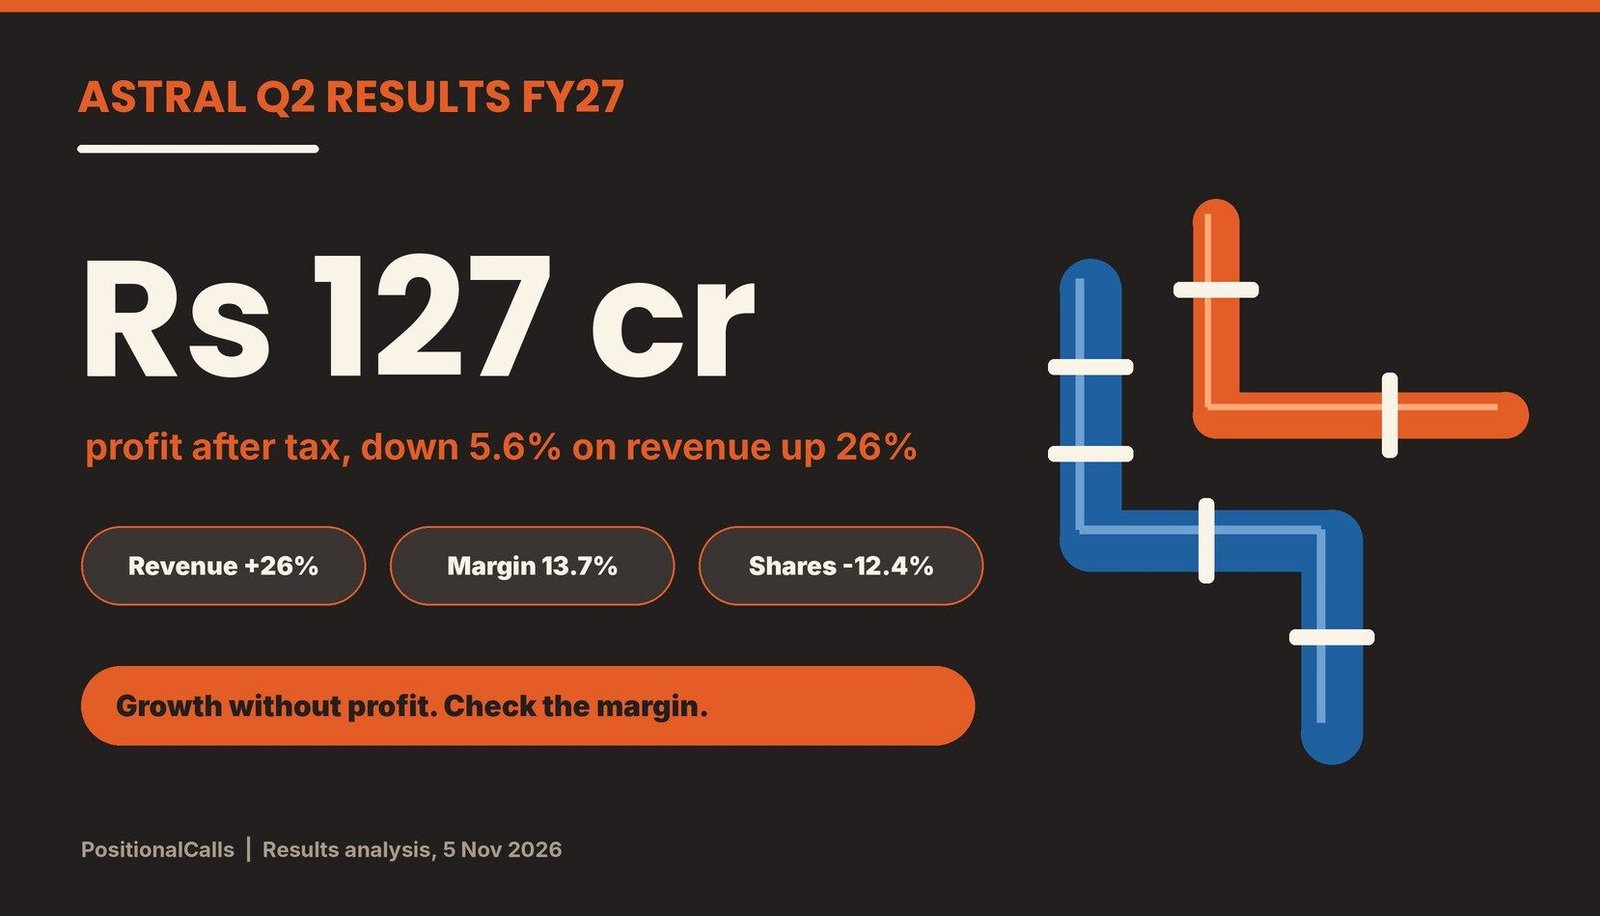
Astral grew revenue 26% and plumbing volume 19%, yet profit fell 5.6% and the shares dropped as much as 12.4%. This page shows where the margin went, how the two segments compare, and what the dividend, guidance and brokerages said.
Quick answer
Astral Q2 results FY27 were reported on Thursday, 5 November 2026: revenue rose 26% to Rs 1,988.3 crore, but profit after tax fell 5.6% to Rs 127.3 crore because EBITDA margin dropped to 13.7% from 17.0%. The shares fell as much as 12.4% on Friday, 6 November.
Latest update (Friday, 6 November 2026, 3:00 PM IST): Astral published results after market hours on Thursday, 5 November 2026 (Kotak Neo timestamps the summary 6:53 PM IST), so the 5 November close of about Rs 1,388 is a pre-results price. On Friday, 6 November the stock opened near Rs 1,368 and reached a 52-week low of Rs 1,215.50, per Business Standard and Business Upturn. I could not find the official 6 November close, so I will add the NSE close and the filing’s tax and other-income lines after the session.
Key takeaways
- Headline: Consolidated revenue was Rs 1,988.3 crore (+26.0%) and profit after tax Rs 127.3 crore (-5.6%); EBITDA grew only 1.5% to Rs 272.3 crore.
- Margin: EBITDA margin fell to 13.7% from 17.0%; plumbing margin was 16.3% (from 19.0%) and paints and adhesives 7.6% (from 12.1%).
- Volume: Plumbing volume rose 19.1% to 72,934 tonnes and plumbing revenue rose 25.0% to Rs 1,398.3 crore, so growth was real; the cost was margin.
- Incremental margin: Revenue rose Rs 410.9 crore but EBITDA only Rs 4.1 crore, an incremental margin near 1.0% (my calculation).
- Dividend: An interim dividend of Rs 1.50 per share has a record date of Friday, 13 November 2026, per Whalesbook.
- Share price: On 6 November the stock hit a 52-week low of Rs 1,215.50, down 12.4% at the low, against a previous close of about Rs 1,386.
In plain words: Astral makes plastic pipes and fittings (the plumbing business, including CPVC pipes and bathware) and also adhesives and paints. EBITDA is operating profit before depreciation, interest and tax; margin is EBITDA divided by revenue. “PAT before OCI” is profit after tax before other comprehensive income, the line reports call net profit. A bps (basis point) is one hundredth of a percentage point.
Data note: as of Friday, 6 November 2026, 3:00 PM IST. Figures come from press and data-platform summaries of the 5 November filing (Kotak Neo, InvestyWise, Multibagg AI and Whalesbook) and from 6 November market reports (Business Standard, Indian Opinion, Business Upturn); I did not open the filing or the investor presentation. EBITDA appears as Rs 272.3 crore (13.7% margin) in the filing summaries and as about Rs 260 crore (13.1%) in market reports; both are shown where they apply. Derived numbers are marked “my calculation”.
Astral Q2 results FY27: key numbers at a glance
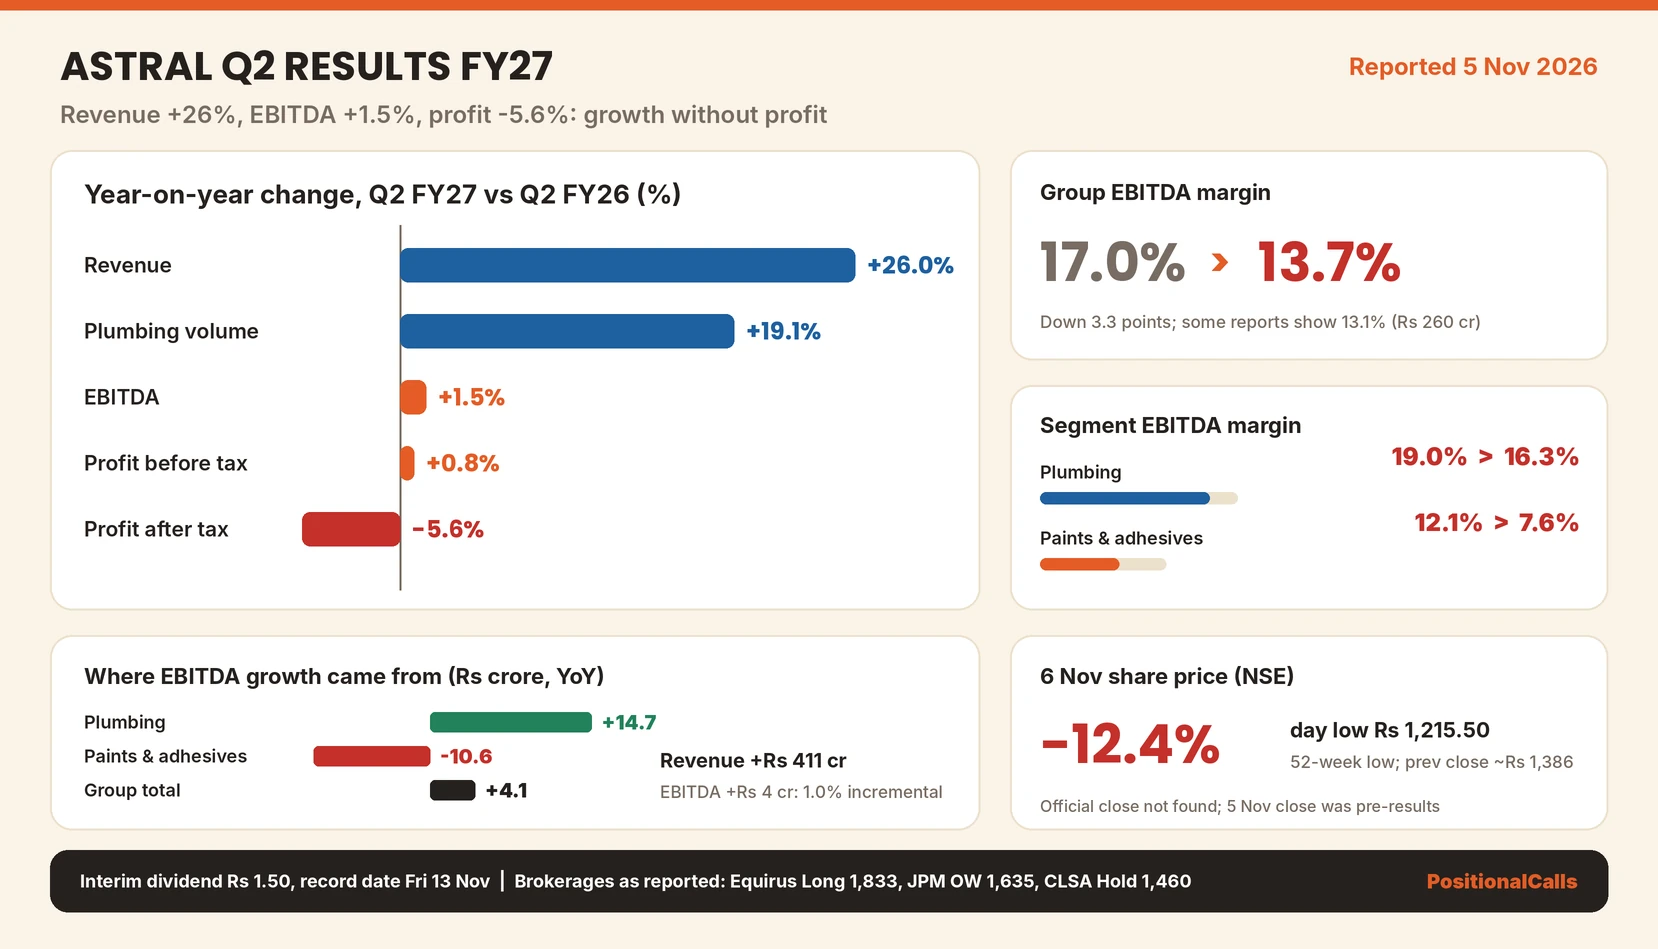
Astral Q2 results FY27 show consolidated revenue of Rs 1,988.3 crore (+26.0%), EBITDA of Rs 272.3 crore (+1.5%), profit before tax of Rs 181.4 crore (+0.8%) and profit after tax of Rs 127.3 crore (-5.6%), with EPS of Rs 4.73 against Rs 5.02.
| Rs crore | Q2 FY27 | Q2 FY26 | Change | Basis and note |
|---|---|---|---|---|
| Revenue from operations | 1,988.3 | 1,577.4 | +26.0% | Kotak Neo; Multibagg AI |
| EBITDA | 272.3 | 268.2 | +1.5% | Margin 13.7% against 17.0% |
| Profit before tax | 181.4 | 179.9 | +0.8% | PBT margin 9.1% against 11.4% |
| Profit after tax (before OCI) | 127.3 | 134.8 | -5.6% | PAT margin 6.4% against 8.5% |
| Cash profit | 206.0 | 207.1 | -0.5% | Company measure, as reported |
| EPS (basic and diluted), Rs | 4.73 | 5.02 | -5.8% | Face value Re 1 |
Cite this table: PositionalCalls, “Astral Q2 Results FY27 Key Numbers Table, as of 6 November 2026”.
Astral Q2 results FY27 cover the quarter ended 30 September 2026. Astral Q2 net profit FY27 is the Rs 127.3 crore line; half-year revenue was Rs 3,566.3 crore (+21.4%), EBITDA Rs 516.3 crore (+11.7%) and profit after tax Rs 247.5 crore (+15.7%), so the first half still grew profit even though the second quarter did not. Confirm every figure on the BSE or NSE page and see the Q2 results calendar for other companies.
When were the Astral Q2 results FY27 announced?
Astral’s Q2 FY27 results were published on Thursday, 5 November 2026, after market hours, and the first trading reaction came on Friday, 6 November 2026, when the shares hit a 52-week low of Rs 1,215.50.
Kotak Neo timestamps its summary 6:53 PM IST on 5 November. I have not opened the board notice, so confirm the exact filing time on the exchange page; the legal deadline for Q2 filings is 14 November 2026. Because the numbers came after the close, the Rs 1,388 close on 5 November, down 2.51% per Kotak Neo, carries no information about the results.
Astral EBITDA margin Q2 FY27: EBITDA flat on 26% more revenue
In the Astral Q2 results FY27, revenue rose Rs 410.9 crore but EBITDA rose only Rs 4.1 crore, an incremental margin of about 1.0% against a base margin of 17.0%; profit before tax rose 0.8% and profit after tax fell 5.6% because the implied tax share rose (my calculation).
| Rs crore | Q2 FY27 | Q2 FY26 | Change | Note |
|---|---|---|---|---|
| Revenue from operations | 1,988.3 | 1,577.4 | +410.9 | +26.0% |
| EBITDA | 272.3 | 268.2 | +4.1 | Incremental margin 1.0% (my calculation) |
| EBITDA margin | 13.7% | 17.0% | -3.3 pts | Kotak Neo and Multibagg basis |
| Items between EBITDA and PBT (EBITDA less PBT) | 90.9 | 88.3 | +2.6 | Net of depreciation, finance cost and other income; my calculation |
| Profit before tax | 181.4 | 179.9 | +1.5 | +0.8% |
| Implied tax and other items (PBT less PAT) | 54.1 | 45.1 | +9.0 | 29.8% against 25.1% of PBT (my calculation) |
| Profit after tax | 127.3 | 134.8 | -7.5 | -5.6% |
Cite this table: PositionalCalls, “Astral EBITDA to Profit Bridge Table, as of 6 November 2026”.
Two features explain the headline. First, growth in revenue did not turn into growth in operating profit: roughly Rs 10 of every Rs 1,000 of extra revenue reached EBITDA. Second, below EBITDA the gap between EBITDA and pre-tax profit stayed near Rs 91 crore, so pre-tax profit rose only Rs 1.5 crore. The step from pre-tax to after-tax profit then widened from Rs 45.1 crore to Rs 54.1 crore, about 30% of pre-tax profit against 25%. The reports do not state a tax rate or a minority share, and the difference may include other items, so treat the tax reading as my inference and check the tax note in the filing.
What a steady margin would have meant. As an illustration and not a forecast, had the group held last year’s 17.0% margin on Rs 1,988.3 crore of revenue, EBITDA would have been about Rs 338 crore, roughly Rs 66 crore more than reported (my calculation). That gap, and not the revenue growth, is what separates this quarter from a normal growth quarter, and it is the number to watch in the next result.
Two EBITDA figures. Market reports on 6 November (Indian Opinion, Whalesbook, Business Upturn) quote EBITDA of about Rs 260 crore and a margin of 13.1% against 16.2% or 16.3%, a fall of 310 bps. The filing summaries (Kotak Neo, Multibagg AI, InvestyWise) show Rs 272.3 crore and 13.7% against 17.0%, a fall of 330 bps. The segment EBITDA figures, Rs 227.6 crore for plumbing and Rs 44.7 crore for paints and adhesives, add to exactly Rs 272.3 crore, so that is the basis used on this page. The roughly Rs 12 crore gap is not explained in the reports; it may reflect other income or a different definition, which I could not verify.
Astral plumbing volume Q2 FY27: +19% volume, but margin slipped to 16.3%
Astral’s plumbing segment grew revenue 25.0% to Rs 1,398.3 crore on a 19.1% rise in volume to 72,934 tonnes, but segment EBITDA rose only 6.9% to Rs 227.6 crore and its margin fell to 16.3% from 19.0%.
| Plumbing | Q2 FY27 | Q2 FY26 | Change | Note |
|---|---|---|---|---|
| Revenue, Rs crore | 1,398.3 | 1,118.6 | +25.0% | Pipes, fittings and bathware |
| Volume, tonnes | 72,934 | 61,224 | +19.1% | Pipes and fittings |
| Segment EBITDA, Rs crore | 227.6 | 212.9 | +6.9% | Kotak Neo; Multibagg AI |
| Segment EBITDA margin | 16.3% | 19.0% | -2.8 pts | Reported 16.3% against 19.0% |
| Revenue per tonne, Rs (revenue divided by volume) | 191,721 | 182,706 | +4.9% | Rough: revenue includes bathware (my calculation) |
| Bathware sales | +26.8% | – | – | Growth rate as reported |
Cite this table: PositionalCalls, “Astral Plumbing Segment Table, as of 6 November 2026”.
Volume grew faster than the price-linked revenue per tonne, which my rough calculation puts up about 5%; because revenue includes bathware and other items, this is an indication and not a reported price. If selling prices rose little while input and freight costs rose, the margin squeeze in plumbing follows, and Whalesbook’s 6 November report points to elevated input and freight costs. Had plumbing held last year’s 19.0% margin on Rs 1,398.3 crore, its EBITDA would have been about Rs 266 crore, Rs 39 crore above the reported figure (my illustration, not a forecast). Plumbing added Rs 14.7 crore of EBITDA year on year, so it carried the whole of the group’s EBITDA growth and more. Half-year plumbing volume was 129,080 tonnes (+10.0%) and half-year plumbing revenue Rs 2,448.8 crore (+18.2%), which puts Q1 plumbing volume near 56,146 tonnes by subtraction (my calculation); the second quarter was about 30% higher than the first.
PositionalCalls WhatsApp channel
Consumer and building-materials results on WhatsApp
- Same-day results notes with the margin basis named
- Segment profit separated from the group number
- Price moves the day they appear
Astral paints and adhesives Q2 FY27: revenue +28.6%, EBITDA down 19%
In the Astral Q2 results FY27, paints and adhesives revenue rose 28.6% to Rs 590 crore, but segment EBITDA fell 19.2% to Rs 44.7 crore from Rs 55.3 crore, a margin of 7.6% against 12.1%, and the segment took away Rs 10.6 crore of EBITDA while plumbing added Rs 14.7 crore (my calculation).
| Paints and adhesives | Q2 FY27 | Q2 FY26 | Change | Note |
|---|---|---|---|---|
| Revenue, Rs crore | 590.0 | 458.8 | +28.6% | Year-ago is group revenue less plumbing (my calculation) |
| Segment EBITDA, Rs crore | 44.7 | 55.3 | -19.2% | Multibagg AI |
| Segment EBITDA margin | 7.6% | 12.1% | -4.5 pts | Reported 7.6% against 12.1% |
| Paint sales growth | +39.9% | – | – | H1 growth 44.0% |
| India adhesives sales growth | +25.3% | – | – | EBITDA margin 10.9% |
| Overseas adhesives sales growth | +30.1% | – | – | EBITDA margin 6.3% |
Cite this table: PositionalCalls, “Astral Paints and Adhesives Segment Table, as of 6 November 2026”.
Paints are growing quickly from a small base, and this page does not show a separate paints profit because the reports do not give one. The segment margin of 7.6% blends India adhesives at 10.9% and overseas adhesives at 6.3% with the paint business, so the low blended margin points to overseas adhesives and paint start-up costs being the drag, which is my reading of the margin split and not a reported cause. Management told analysts it is focused on market share despite raw-material price pressure (InvestyWise). For how other paint makers fared in the same quarter, see the Berger Paints Q2 FY27 results and the Asian Paints Q2 FY27 results.
Astral Q2 FY27 against Q1: the quarter-on-quarter view
For the Astral Q2 results FY27 against Q1, subtracting Q1 from the half-year totals gives a Q1 FY27 of revenue Rs 1,578.0 crore, EBITDA Rs 244.0 crore (15.5% margin) and profit Rs 120.2 crore, so Q2 revenue rose 26.0% and EBITDA 11.6% on the quarter while the margin fell 1.8 points (my calculation).
| Rs crore | Q2 FY27 | Q1 FY27 (derived) | H1 FY27 | QoQ |
|---|---|---|---|---|
| Revenue from operations | 1,988.3 | 1,578.0 | 3,566.3 | +26.0% |
| EBITDA | 272.3 | 244.0 | 516.3 | +11.6% |
| EBITDA margin | 13.7% | 15.5% | 14.5% | -1.8 pts |
| Profit after tax | 127.3 | 120.2 | 247.5 | +5.9% |
Cite this table: PositionalCalls, “Astral Q2 vs Q1 FY27 Table, as of 6 November 2026”.
The derived Q1 profit of Rs 120.2 crore matches the roughly Rs 120 crore Astral reported for Q1 FY27 (+52% year on year, per earlier reports), which is a useful tie-out of the half-year figures. The Astral Q2 results FY27 sequential picture is mixed: Q2 is bigger than Q1 on revenue, EBITDA and profit, yet the margin is lower, so volume growth and seasonality helped the totals while costs and mix reduced the margin. Management said it expects double-digit volume growth in FY27 and cited “unprecedented growth in October”, per Indian Opinion, which is a company statement and not a result.
The Astral share price after Q2 results opened near Rs 1,368 on Friday, 6 November 2026, fell to Rs 1,237 (-10.6%) by 10:20 AM and touched a 52-week low of Rs 1,215.50, down 12.4% on the day, against a previous close of about Rs 1,386.
| Astral on NSE | Price (Rs) | Change | Source and time |
|---|---|---|---|
| Close, Thursday 5 November | 1,388 (or 1,386.25) | -2.51% | Kotak Neo; Business Upturn (previous close) |
| Open, Friday 6 November | 1,368.05 | – | Business Upturn, 9:36 AM |
| Low at 9:36 AM | 1,247.65 | -10.0% | Business Upturn (52-week low then) |
| Price at 10:20 AM | 1,237 | -10.6% | Business Standard |
| Day low | 1,215.50 | -12.4% | Business Standard; Indian Opinion (52-week low) |
| 52-week high (11 March 2026) | 1,768.70 | – | Low is 31.3% below it (my calculation) |
| Official 6 November close | Not found | – | Not available at the time of writing |
Cite this table: PositionalCalls, “Astral Share Price After Q2 Results Table, as of 6 November 2026”.
Reports disagree slightly on the base: Business Upturn gives a previous close of Rs 1,386.25 while Kotak Neo’s Rs 1,388 close and its 2.51% fall imply about Rs 1,388, a gap of Rs 1.75; against Rs 1,386.25 the day low is a fall of 12.3% (my calculation), which matches the reported 12.4% only roughly. Business Standard counted about 27 lakh shares traded on BSE and NSE by the time of its report and described this as heavy volume, with the Sensex up 0.7% and the Nifty up 0.5%, so the fall was specific to the stock. Whalesbook reports an 11% fall during the session and ties it to margin contraction and elevated input and freight costs. This is price history, not a price target or a call to buy or sell.
What brokerages said after the Astral Q2 results FY27 (as reported)
After the Astral Q2 results FY27, Equirus Securities kept a Long rating with a Rs 1,833 target and cut its FY27 and FY28 EBITDA estimates by 5% and 3%; Indian Opinion also lists JPMorgan at Overweight with Rs 1,635 and CLSA at Hold with Rs 1,460, without dates, so treat all three as reported views and not as my advice.
| Brokerage | Rating | Target (Rs) | What was reported |
|---|---|---|---|
| Equirus Securities | Long | 1,833 | Post Q2; FY27E EBITDA cut 5%, FY28E cut 3% on near-term margin pressure; sees recovery from pricing, UK adhesives, CPVC backward integration and new products (Business Standard) |
| JPMorgan | Overweight | 1,635 | Listed by Indian Opinion; date not stated |
| CLSA | Hold | 1,460 | Listed by Indian Opinion; date not stated |
Cite this table: PositionalCalls, “Astral Brokerage Views Table (as reported), as of 6 November 2026”.
The three targets span Rs 1,460 to Rs 1,833. Measured against the 6 November low of Rs 1,215.50, all three sit above the market price (my calculation: Rs 1,460 is 20% above and Rs 1,833 is 51% above), but the reports do not say whether the JPMorgan and CLSA targets were set before or after the results, so they may predate the margin miss. I found no consensus estimate for the quarter, so I cannot say whether the result missed or beat; Equirus’s estimate cuts suggest the margin was weaker than that broker expected. These are other firms’ opinions, shown for context. PositionalCalls does not give targets or buy, sell or hold views.
Astral dividend, guidance, CPVC resin plant and the DSS stake
Astral declared an interim dividend of Rs 1.50 per share on a Re 1 face value with a record date of Friday, 13 November 2026, about 32% of Q2 EPS and roughly Rs 40 crore in all (my calculation), while reiterating double-digit FY27 volume growth.
| Item | Detail | Source and note |
|---|---|---|
| Interim dividend | Rs 1.50 per share (150% of face value Re 1) | Whalesbook; payment date not found |
| Record date | Friday, 13 November 2026 | Whalesbook; Kotak Neo gives no date |
| Dividend outlay | About Rs 40 crore on about 26.9 crore shares | My calculation from profit divided by EPS |
| Cash and bank balance (30 September 2026) | Rs 459 crore | Kotak Neo; InvestyWise shows Rs 4,590 million, the same figure |
| FY27 volume guidance | Double-digit growth | InvestyWise; Indian Opinion |
| Margin guidance | 16% to 18% (as reported) | Indian Opinion; basis not stated, may be a different margin definition |
| CPVC resin plant | 40,000 tonnes; ready for commercial use by Q4 FY27, full benefit from FY28 | Kotak Neo |
| Price increases | PVC and CPVC price pass-through completed in Q3 FY27 | Kotak Neo; Indian Opinion |
| Aluminium PEX launch | Planned for Q3 FY27 | Kotak Neo; InvestyWise |
| DSS acquisition | 60% of Differentiated & Sustainable Solutions LLP for Rs 39.1 crore | Whalesbook; agreement June 2026, effective 1 April 2026 |
Cite this table: PositionalCalls, “Astral Dividend, Guidance and Projects Table, as of 6 November 2026”.
The margin guidance matters for how to read this quarter. If a 16% to 18% margin is the full-year aim, a 13.7% second quarter and a 14.5% first half (14.5%, my calculation) mean the remaining months would need a much higher margin, but the reports do not say which margin the company guided on, so I do not draw that conclusion. Dividends are taxed in the hands of the shareholder; see the dividend tax in India guide for the TDS threshold and how Form 121 works.
Astral Q2 FY27: five checks to make in the filing
Five items decide how to read the Astral Q2 results FY27: which EBITDA definition the company uses, the tax and other-income lines, the paints and adhesives split, the raw-material cost trend, and the cash flow and capex in the half-year statements.
- EBITDA basis. Check whether Rs 272.3 crore or about Rs 260 crore is the company’s own figure and what sits in the roughly Rs 12 crore gap.
- Tax and other items. Pre-tax profit rose 0.8% but after-tax profit fell 5.6%; the tax note should show whether the rate rose or a one-off sits in the line.
- Segment profit. Paints and adhesives EBITDA is Rs 44.7 crore; the filing’s segment note should separate adhesives from paints, which the press summaries do not.
- Input costs. Whalesbook cites elevated input and freight costs; the cost-of-materials line against revenue shows how much of the margin loss was materials and how much was other expenses.
- Working capital and capex. I found no cash flow or capex figures for the half year; they matter because a CPVC resin plant and capacity additions are under way.
Meeting expectations also depends on a consensus I could not find, so a beat or miss claim is left open here. A wide gap between revenue growth and profit growth is common when a company is adding capacity, launching products or absorbing cost spikes, but each case needs the filing to confirm.
Astral Q2 results FY27: what the numbers say and what they do not
The Astral Q2 results FY27 prove volume and revenue growth are strong, and they show profit did not follow because margin fell in both segments, but they do not show whether the fall is temporary, because management’s statements are guidance and the filing was not opened.
What the numbers show: revenue +26.0%, plumbing volume +19.1%, EBITDA +1.5%, profit after tax -5.6%, margin down about 3.3 points, and a half-year profit still up 15.7%. What they do not show: why the tax share rose, which EBITDA definition applies, whether the margin guidance covers the group or a segment, and what the 6 November closing price was. Use the table captions on this page when citing a number, and confirm each line against the exchange filing.
Bottom line
Astral Q2 results FY27 show revenue up 26% to Rs 1,988 crore and plumbing volume up 19%, but profit after tax down 5.6% to Rs 127 crore as EBITDA margin fell to 13.7%, with both segments squeezed and the shares down as much as 12.4% on 6 November. Name the EBITDA basis you quote, remember the 5 November close was before the results, and confirm the tax and segment lines in the filing.
Next read: the Q2 results calendar.
Part of the Earnings series.
PositionalCalls WhatsApp channel
Never miss a results-day update
- Same-day decoders for the biggest companies reporting
- One-offs separated from the underlying number
- Corrections posted openly when a figure changes
FAQs on Astral Q2 results FY27
When were the Astral Q2 results FY27 announced?
Astral published the Q2 FY27 results for the quarter ended 30 September 2026 on Thursday, 5 November 2026, after market hours. The first trading reaction was on Friday, 6 November. Confirm the filing time on the exchange page.
What was the Astral Q2 net profit FY27?
Consolidated profit after tax (before OCI) was Rs 127.3 crore, down 5.6% from Rs 134.8 crore a year earlier. Profit before tax was Rs 181.4 crore (+0.8%) and EPS was Rs 4.73 against Rs 5.02.
What was Astral’s revenue in Q2 FY27?
Revenue from operations was Rs 1,988.3 crore, up 26.0% from Rs 1,577.4 crore. Plumbing contributed Rs 1,398.3 crore and paints and adhesives Rs 590 crore, which add to the total.
Why did Astral’s profit fall when revenue rose 26%?
EBITDA rose only 1.5% to Rs 272.3 crore, so the margin fell to 13.7% from 17.0%. Reports cite elevated input and freight costs and weaker paints and adhesives profit. Profit after tax also fell because the implied tax share rose, which is my inference.
What was Astral’s EBITDA margin in Q2 FY27?
The filing summaries show 13.7% (Rs 272.3 crore) against 17.0%. Some 6 November market reports show 13.1% against 16.2% or 16.3%. The page uses 13.7% because the segment EBITDA figures add to Rs 272.3 crore.
How did Astral’s plumbing segment do in Q2 FY27?
Plumbing revenue rose 25.0% to Rs 1,398.3 crore on volume of 72,934 tonnes (+19.1%). Segment EBITDA rose 6.9% to Rs 227.6 crore and its margin fell to 16.3% from 19.0%.
What is Astral’s interim dividend and record date?
Astral declared an interim dividend of Rs 1.50 per share with a record date of Friday, 13 November 2026, per Whalesbook. I did not find a payment date. See the dividend tax guide on this site for how it is taxed.
On 6 November the stock opened near Rs 1,368 and touched a 52-week low of Rs 1,215.50, down 12.4%, against a previous close of about Rs 1,386. I could not find the official close. This is not a price target.
What did brokerages say about Astral after Q2?
As reported, Equirus kept Long with a Rs 1,833 target and cut FY27 and FY28 EBITDA estimates by 5% and 3%; JPMorgan is listed at Overweight (Rs 1,635) and CLSA at Hold (Rs 1,460) without dates. These are their views, not mine.
Does this page give an Astral Q2 results FY27 buy or sell call?
No. This is research and education, not advice. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Use the numbers to frame questions and speak to a registered adviser before investing.
Sources
- Kotak Neo, 5 November 2026 (consolidated and segment figures, close)
- InvestyWise, November 2026 (H1 figures, segments, management points)
- Multibagg AI, 5 November 2026 (year-ago bases, margins; an AI summary)
- Whalesbook, 5 November 2026 (dividend record date, DSS stake)
- Business Standard, 6 November 2026 (share price, Equirus)
- Indian Opinion, 6 November 2026 (brokerages, guidance, 13.1% margin)
- Business Upturn, 6 November 2026 (previous close, opening price)
- Whalesbook, 6 November 2026 (11% fall, cost reasons)
- BSE and NSE announcement pages: where the filing appears (I did not open it).
PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent Indian stock market research and education site founded by Shubham Chaudhary. This page is education and results analysis, not a recommendation to buy, sell or hold any security. How I researched this: I read press and data-platform summaries of the filing, tied the two segments to group revenue and EBITDA, tied half-year profit to Q1 plus Q2, compared the two EBITDA definitions, recomputed every derived number and listed conflicts openly. I have not opened the filing.
Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive