Learning · NRI Investing
How an NRI can invest in Indian shares in 2026: accounts, the new holding limits, trading rules, repatriation and tax.
Quick answer
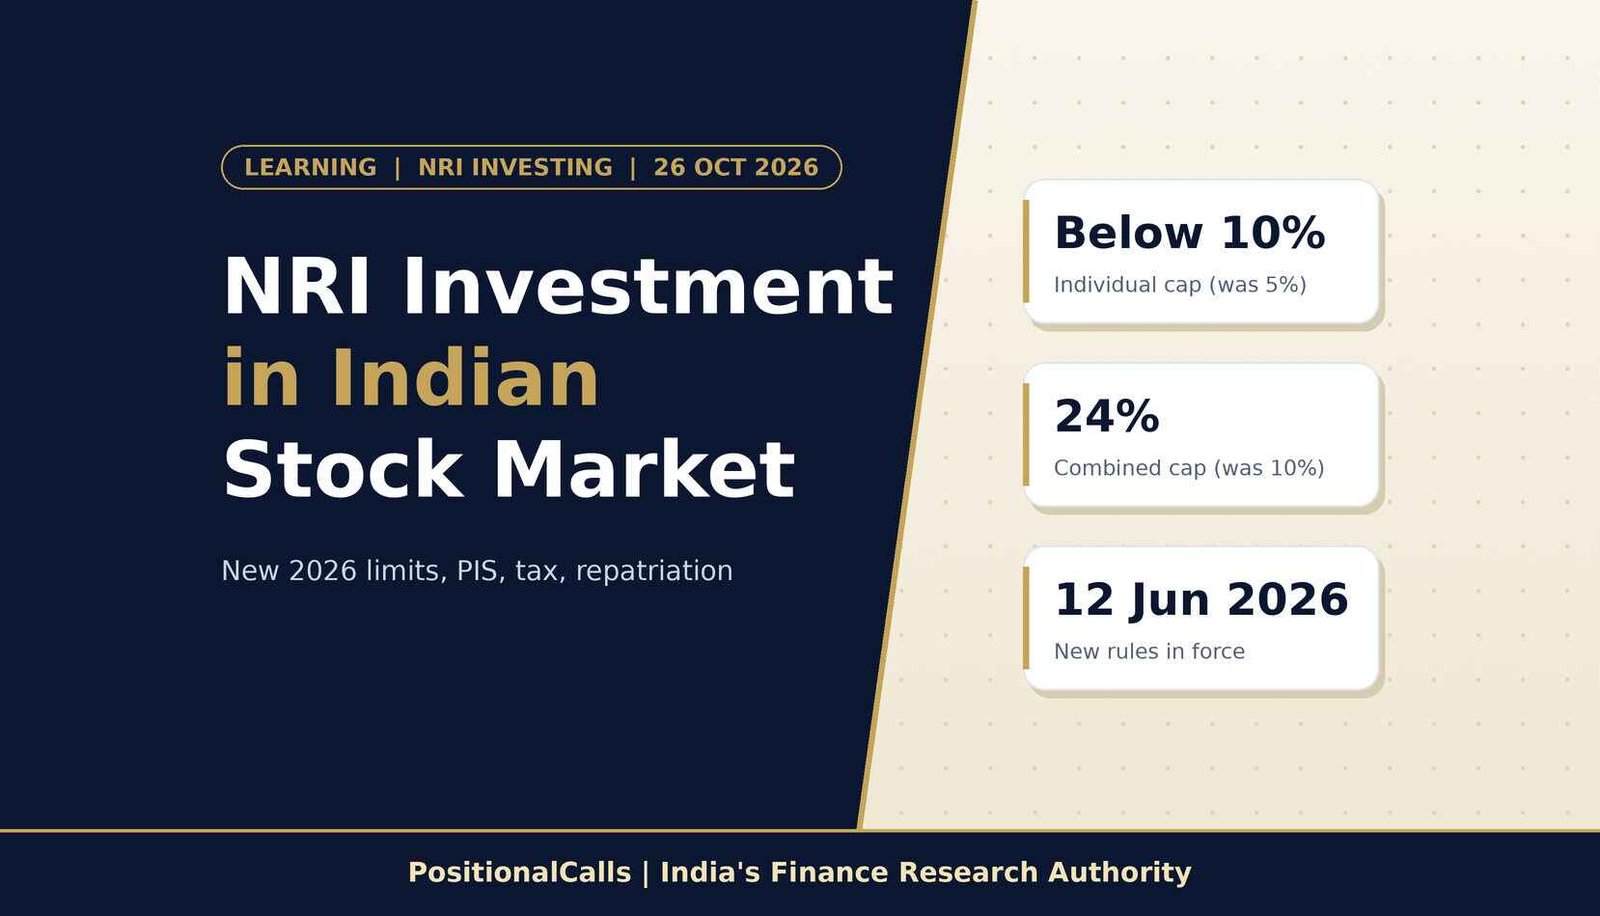
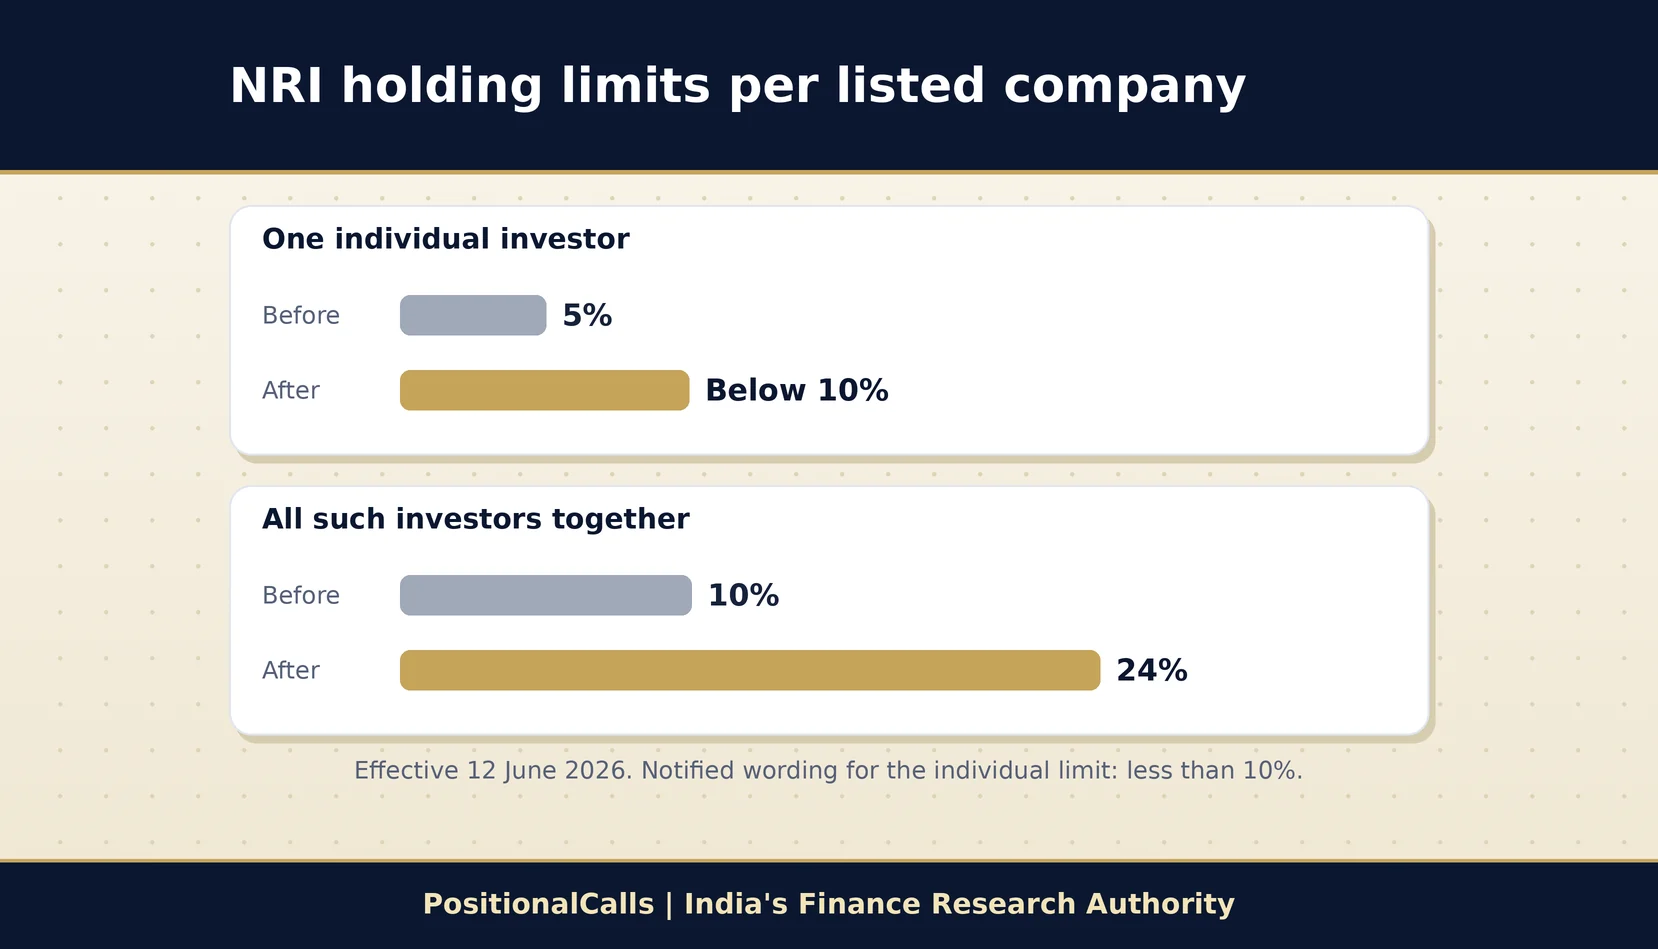
NRI investment in Indian stock market works through an NRE or NRO account, an NRI demat and trading account, and the RBI Portfolio Investment Scheme (PIS). From 12 June 2026, an individual may hold up to just under 10% of a listed company (earlier 5%), and all such investors together up to 24% (earlier 10%). Only delivery trades are allowed.
Latest update (26 October 2026, 11:00 AM IST): The Foreign Exchange Management (Non-debt Instruments) Third Amendment Rules, 2026 took effect on 12 June 2026. Many older guides still show the 5% and 10% limits. Next: update if RBI or SEBI issue operating circulars for brokers and banks.
Key takeaways
- New limits: individual holding below 10% of a listed company, all such individuals together 24%, effective 12 June 2026.
- Wider eligibility: the PIS route now covers all individuals resident outside India, not only NRIs and OCIs.
- Accounts: NRE-linked PIS is repatriable; NRO-linked PIS is non-repatriable; an NRO non-PIS account is the simplest route.
- Trading rules: delivery only. No intraday, short selling or futures and options.
- Tax: NRI investment in Indian stock market gains on listed equity are taxed at 20% short-term and 12.5% long-term above Rs 1.25 lakh; TDS is deducted at source.
- Repatriation: NRO proceeds are generally capped at USD 1 million a financial year, with Forms 15CA and 15CB.
In plain words: an NRI cannot use a normal resident demat account. You open NRI accounts, route every trade through a bank that reports to the RBI, and pay Indian tax on gains.
Data note: as of 26 October 2026, 11:00 AM IST. Limits come from the rules notified on 12 June 2026, as reported by law firms and legal publishers; I could not open the Gazette text itself. Tax rates are cross-checked across several publishers. Check with your bank and a chartered accountant before NRI investment in Indian stock market begins.
1. Can an NRI invest in the Indian stock market?
Yes. An NRI can invest in the Indian stock market by buying listed shares, ETFs, mutual funds and IPOs through NRI bank and demat accounts, subject to RBI and SEBI rules. NRI investment in Indian stock market is regulated by the Foreign Exchange Management Act (FEMA), the RBI, and SEBI, and taxed under Indian income tax law.
The core rule is that you must route purchases and sales through accounts that tell the RBI what you did. The main tool for NRI investment in Indian stock market is the Portfolio Investment Scheme (PIS). A PIS bank account links your NRE or NRO account to your NRI demat and trading accounts, and the bank reports each trade to the RBI.
Who counts as an NRI, OCI or PROI?
| Term | Meaning | Why it matters |
|---|---|---|
| NRI | An Indian citizen who lives outside India under FEMA tests (not the same as the income tax residency test) | Eligible for NRE and NRO accounts and PIS |
| OCI | Overseas Citizen of India cardholder | Treated like an NRI for the PIS route |
| PROI | Person resident outside India, a wider group that includes foreign nationals | From 12 June 2026, individual PROIs can also use the repatriation route for listed equity |
Your FEMA residential status and your income tax residential status can differ. A person can be an NRI for one and a resident for the other. Check both before you open accounts.
Yes. Under FEMA a person can continue to hold securities bought as a resident after becoming an NRI, on a non-repatriable basis. Banks usually ask you to move the shares into an NRO demat account. Once moved, they can be sold in the market without PIS permission, as bank pages explain.
If you are new to demat accounts, read our guide on demat account charges in India before you compare NRI broker plans.
2. How does NRI investment in Indian stock market differ from resident investing?
An NRI uses separate NRI accounts, trades only on a delivery basis, has bank-reported transactions, and faces TDS and repatriation rules that residents do not. The shares and the exchanges are the same. The plumbing is different.
| Area | Resident investor | NRI |
|---|---|---|
| Demat and bank account | Resident accounts | NRI-tagged demat; NRE or NRO bank account |
| Intraday, short selling, F&O | Allowed | Not allowed |
| Trade reporting | None beyond exchange rules | Bank reports each trade to the RBI under PIS |
| TDS on equity gains | Generally none at the time of sale | Deducted at source by the broker |
| Taking money abroad | Not applicable | Repatriation rules and forms apply |
| Holding limit per company | Not applicable | Below 10% individually from 12 June 2026 |
Because of these differences, NRI investment in Indian stock market needs a plan for taxes and exits before a plan for stocks. A resident can often sell and spend. An NRI must also think about the account the money lands in.
Does the 182-day or 183-day rule decide NRI status?
The days-of-stay tests differ between FEMA and income tax, and they have exceptions. Do not rely on a single number. Ask a chartered accountant to confirm your status for both purposes each year, especially if you return to India often.
3. What changed for NRI investment in Indian stock market in June 2026?
Two limits changed. An individual may now hold just under 10% of a listed company (earlier 5%), and all such individuals together may hold up to 24% (earlier 10%), effective 12 June 2026. The change was announced in the Union Budget for FY 2026-27, confirmed by a Finance Ministry statement on 5 June 2026, and notified on 12 June 2026 as S.O. 3030(E).
| Item | Before 12 June 2026 | From 12 June 2026 | Source type |
|---|---|---|---|
| Who can use the PIS route for listed equity | NRIs and OCIs | All individuals resident outside India, including NRIs and OCIs | Law-firm and legal-publisher summaries |
| Individual holding in one listed company | Up to 5% of paid-up equity | Below 10% (notified wording: less than 10%) | Legal summaries; media often write 10% |
| All such individuals combined | 10%, raise to 24% only by special resolution | 24% of paid-up equity on a fully diluted basis | Legal summaries |
| Effective date | Not applicable | 12 June 2026 | Gazette notification, as reported |
For the full legal reading, see this law-firm note on the Third Amendment Rules, 2026 and the SCC Online explainer of the Third Amendment Rules, 2026. Both describe the same changes in rules 9, 12 and 13 and in Schedule III.
What does the new limit mean in rupees?
My calculation for a listed company with Rs 300 crore of paid-up equity: the old 5% individual limit allowed up to Rs 15 crore; the new limit is just under 10%, so below Rs 30 crore; and all such individuals combined can hold up to 24%, which is Rs 72 crore. For most retail NRI investment in Indian stock market, this will not change anything, because few NRIs hold even 1% of a listed company.
Why do many websites still show 5% and 10%?
Bank and broker pages are often written once and not revised. Several still publish the old limits, even though the amended rules took effect on 12 June 2026. The old numbers are therefore the most common mistake in articles on NRI investment in Indian stock market. Always check the date on a page and the rule it cites.
4. Can foreign nationals now use the same route?
Yes, in principle. Since 12 June 2026 the repatriation route for listed equity is open to individual persons resident outside India, not only NRIs and OCIs. Legal summaries say the change replaces the words “non-resident Indian or overseas citizen of India” with “an individual” in the relevant rules.
The scope is still limited. Reports say citizens of some neighbouring countries remain excluded, and investments are channelled through a designated authorised dealer bank branch. Banks and brokers must update their onboarding before they can open such accounts, so availability may vary.
Does this affect an NRI?
Directly, it affects the limits. The 24% aggregate cap now covers all individual investors in this group. If more foreign individuals invest, a popular company could reach the cap sooner. Check the RBI list before you build a large position.
Foreign portfolio investors registered with SEBI follow a different route and different limits, so do not mix the two. This guide covers only individual investors.
5. Which account route suits NRI investment in Indian stock market: NRE PIS, NRO PIS or NRO non-PIS?
Use an NRE PIS account for repatriable investing from foreign income, an NRO PIS account for non-repatriable investing from Indian income, and an NRO non-PIS account for a simpler non-repatriable route. The choice affects how you take money out, so decide before your first trade.
| Route | Funds come from | Repatriation | RBI reporting | Best for |
|---|---|---|---|---|
| NRE PIS | Foreign income sent to your NRE account | Principal and gains repatriable, after tax | Each trade reported through the bank | Investors who may move money back abroad |
| NRO PIS | Indian income in your NRO account | Non-repatriable on the investment; NRO limit applies to sale proceeds | Each trade reported | Using Indian income for repatriation-free investing |
| NRO non-PIS | Your NRO account | Non-repatriable; limited by the NRO cap | No PIS permission needed | Simple long-term holding with no RBI approval step |
Sources differ slightly on details such as which account can use which route, so confirm the exact setup with your bank and broker. A common feature is that an NRE-funded PIS account allows full repatriation of principal and gains after tax, while NRO routes are limited.
Do you need a separate NRI demat account?
Yes. A resident demat account cannot be used for NRI investing. Your demat account is tagged as an NRI account at the depository, and it is linked to your NRE or NRO account. Costs follow normal demat rules; see our guide to demat account charges for how AMC and DP charges work.
Can you hold both an NRE and an NRO route?
Yes. Many NRIs open both with the same designated bank, so they can choose a route for each investment. Keep the money trails separate. Mixing funds makes repatriation and tax records harder.
6. How do you start NRI investment in Indian stock market, step by step?
Open an NRE or NRO bank account, add PIS if needed, open the NRI demat and trading accounts, link them, then place delivery orders. Banks and brokers say the process often takes about one to two weeks, but this varies.
- Check your status: confirm you are an NRI or OCI under FEMA and keep your passport, visa or residence proof ready.
- Open an NRE or NRO account: pick a bank that offers PIS, since only designated branches can give the permission.
- Apply for PIS if you want a PIS route: the bank issues a permission letter to you.
- Open an NRI demat and trading account: use a SEBI-registered broker and link it to your bank account.
- Get a PAN: you need a PAN to trade and to file Indian tax returns.
- Place delivery orders: buy or sell, and the bank reports the trade to the RBI.
What documents do you usually need?
- Passport and a valid visa or residence permit.
- Overseas address proof.
- PAN card.
- Photographs and signatures.
- Bank account details.
- A tax residency certificate, if you plan to claim treaty benefits.
Documents may need attestation by an Indian embassy, a notary, or an authorised person, depending on the broker. Ask before you start so that you do not repeat the process.
The Indian market also has holiday schedules and special sessions. Our Muhurat trading 2026 guide lists the 8 November 2026 session timings, which NRIs can trade only as delivery orders.
7. What is allowed and not allowed in NRI investment in Indian stock market?
In NRI investment in Indian stock market, an NRI can buy and sell listed shares and ETFs on a delivery basis, apply for IPOs, and invest in mutual funds, but cannot do intraday trading, short selling or futures and options.
| Product | Allowed? | Key condition |
|---|---|---|
| Listed shares on NSE or BSE | Yes | Delivery basis only, through a PIS or non-PIS route |
| ETFs | Yes | Listed ETFs, subject to the same delivery rule |
| IPOs | Yes | NRIs can apply on a non-repatriation basis through NRE or NRO accounts, as banks explain; check the issue’s own terms |
| Mutual funds | Yes | No PIS needed; NRE or NRO account is enough. Some fund houses restrict US and Canada residents because of FATCA |
| Intraday and short selling | No | Not permitted for NRIs |
| Futures and options | No | Not permitted for NRIs in the PIS route |
| Listed company shares above the holding limit | No | Banned once the limit is reached; the limit is now below 10% individually and 24% in aggregate |
How do NRIs apply for an IPO?
NRIs usually apply with money from an NRE or NRO account, or from an inward remittance, and the allotment is held in the NRI demat account. The listing and allotment process is the same as for residents. See our IPO allotment status guide and the Jio Platforms IPO allotment guide for how allotment works, and the EAAA India Alternatives IPO guide for a mid-size issue. NRIs should check whether a given issue allows them to apply and on which basis.
Does the new rule make NRI investment in Indian stock market riskier?
The rule changes limits for NRI investment in Indian stock market, not risk. A higher cap lets you hold more of one company, which adds concentration risk. Most retail investors stay far below any cap.
PositionalCalls WhatsApp channel
Track NRI investing rule changes
- Alerts on RBI and FEMA changes for NRI investors
- Plain-language explainers on PIS, NRE and NRO
- A message when this guide is updated
8. How does repatriation work for NRI investment in Indian stock market?
Gains and principal from an NRE-funded repatriable investment can be sent abroad after tax, while NRO proceeds are generally capped at USD 1 million a financial year and need Forms 15CA and 15CB. Sources differ on whether the cap is per financial year or per calendar year, so confirm the period with your bank.
| Question | NRE route | NRO route |
|---|---|---|
| Can you send principal abroad? | Yes, after tax on gains | Only within the USD 1 million cap |
| Which forms? | Bank forms, plus tax proof as asked | Form 15CA and, where required, 15CB from a chartered accountant |
| Who deducts tax first? | Broker or bank deducts TDS on gains | Same |
| Typical delay | Days to weeks, depending on the bank | Longer, because of the CA certificate |
What is the process to repatriate sale proceeds from an NRO account?
- Sell and receive proceeds in the linked NRO account after TDS.
- Pay or confirm tax on the gain.
- Get a CA certificate (Form 15CB) where required.
- File Form 15CA on the income tax portal.
- Submit to the bank with your instruction and the documents it asks for.
Keep the contract notes, TDS certificates and the CA certificate for at least the period the bank states. They are your proof if the tax department or the bank asks later.
9. How is NRI investment in Indian stock market taxed?
Listed equity gains are taxed at 20% for short-term and 12.5% for long-term gains above Rs 1.25 lakh a year, plus surcharge and 4% cess, with TDS deducted at source. The rates match those for residents. For the full rate table and examples, read our capital gains tax on shares guide.
| Income | Rate for an NRI | Source type |
|---|---|---|
| Short-term gains on listed shares and equity funds (held 12 months or less) | 20% plus surcharge and cess | Income Tax Department pages and publishers |
| Long-term gains on listed shares and equity funds (held over 12 months) | 12.5% on gains above Rs 1.25 lakh, plus surcharge and cess | Income Tax Department page |
| Dividends | 20% base TDS, or a lower treaty rate where claimed | Tax publishers |
| NRO interest | 30% base TDS, lower with a treaty | Tax publishers |
| NRE interest | Not taxable in India for a non-resident | Tax publishers |
Rate details come from the Income Tax Department page on long-term capital gains and the Income Tax Department page on short-term capital gains, and from cross-checked publishers as of 26 October 2026, 11:00 AM IST. Section numbers changed under the Income-tax Act, 2025, so older articles that cite section 111A or 112A describe the same rules under old numbering.
How much TDS does a broker deduct?
Brokers deduct TDS on NRI gains, often at a rate that includes the maximum surcharge. One broker’s published schedule shows about 14.95% on long-term and 23.92% on short-term gains. My calculation: 12.5% x 1.15 x 1.04 = 14.95%, and 20% x 1.15 x 1.04 = 23.92%. Your final tax can be lower, and the excess is recovered when you file your return. Check your broker’s contract note, because systems differ on whether the Rs 1.25 lakh exemption is allowed at the time of TDS.
Example: a long-term sale under an NRE PIS account
| Item | Amount | Working |
|---|---|---|
| Bought | Rs 10,00,000 | Delivery buy |
| Sold after 18 months | Rs 12,00,000 | Delivery sale |
| Long-term gain | Rs 2,00,000 | 12,00,000 minus 10,00,000 |
| TDS if deducted at 12.5% plus 4% cess on the full gain | Rs 26,000 | 2,00,000 x 13% |
| Final tax before surcharge | Rs 9,750 | (2,00,000 minus 1,25,000) x 12.5% = 9,375, plus 4% cess 375 |
| Possible refund when you file | Rs 16,250 | 26,000 minus 9,750 |
This is my illustration, ignoring surcharge, charges and treaty relief. It shows why filing an Indian return matters even if tax was deducted at source.
Must an NRI file an Indian tax return?
Publishers say an NRI with Indian capital gains must file a return, generally ITR-2, and that missing the deadline can bring penalties. Treaty benefits usually need a tax residency certificate and Form 10F. Confirm the form and deadline with a chartered accountant.
10. What do you need, what does it cost and what is the tax angle?
For NRI investment in Indian stock market you need NRI bank and demat accounts, a PAN and a PIS permission if you choose that route; the costs are the demat and trading charges, taxes and remittance fees; the tax angle is TDS and a return.
What you need
- NRE or NRO account with a bank that offers PIS.
- NRI demat and trading account with a SEBI-registered broker.
- PAN, passport, visa or residence proof, and overseas address proof.
- Tax residency certificate and Form 10F if you plan to claim a treaty.
What it costs
Broker plans for NRIs often differ from resident plans, so read the schedule. Typical items are an account opening fee, AMC, brokerage, DP charges, STT of 0.1% on delivery, stamp duty, exchange charges, GST, bank PIS fees and remittance fees. See our guide to demat account charges for how each is calculated. Check your bank’s and broker’s current schedule.
Mutual funds do not need PIS and can be bought with an NRE or NRO account. Others use portfolio management services, which have a minimum investment set by SEBI. Neither is a recommendation. Insurance is separate; see our term insurance guide and health insurance guide if you are also reviewing cover for family in India.
Scam warning
Fake sites and messages promise guaranteed returns on Indian stocks for NRIs, or ask for a “PIS fee” through a link. Open accounts only through official bank and broker sites, check SEBI registration, never share an OTP, and never send money to a personal account.
11. What should you check before NRI investment in Indian stock market begins?
Check your FEMA status, your account route, the holding limit, the tax and TDS, and your repatriation plan before the first trade.
- Am I an NRI or OCI for FEMA purposes, and has my tax residency been checked?
- Which route suits me: NRE PIS, NRO PIS or NRO non-PIS?
- Does my bank have a designated PIS branch, and what are its fees?
- Is my broker SEBI-registered and does it support NRI accounts?
- Am I below the holding limit in the company, and is the company on the RBI ban list?
- Do I know the TDS rate and have I planned a tax return?
- Do I have a plan and the forms ready to repatriate funds?
- Have I kept contract notes and TDS certificates?
How do you track the limit?
The RBI publishes a list of companies where foreign holding limits are reached. Brokers show a restriction when you try to buy. If the cap is hit, new NRI purchases may be blocked, though selling is still allowed. With the new 24% aggregate ceiling, fewer companies are likely to hit it, but check the list before building a position.
12. How do you compare banks and brokers for NRI investment in Indian stock market?
Compare PIS support, fees, account setup time, trading platform access from abroad and customer support, using each provider’s published schedule. This is a checklist, not a ranking of any bank or broker.
| Criterion | What to ask | Why it matters |
|---|---|---|
| PIS support | Does the bank give PIS permission and for NRE, NRO or both? | Decides your repatriation route |
| Fees | Account opening, AMC, brokerage, DP charge, PIS fee, remittance fee | Costs accumulate on every trade and every remittance |
| Onboarding | Online or in person, attestation needs, expected days | Delays can miss a market event |
| Platform access | Can I log in from my country, with what authentication? | Some apps restrict access by location |
| Reports | Contract notes, TDS certificates, capital gains statements | Needed for your Indian return and home-country filing |
| Support | Help for NRIs in my time zone | Matters when a trade or remittance fails |
Read the fee schedule line by line, because NRI plans often have different rates than resident plans. For how each charge works, see our demat account charges guide.
13. What happens to NRI investment in Indian stock market if you return to India?
When you become a resident again, you generally need to open a resident demat account, transfer your securities from the NRI account, and close the NRI account. Bank pages describe this sequence, and your bank accounts also change status.
- Tell your bank and broker about the change in status.
- Convert NRE and NRO accounts as the bank instructs.
- Move shares to the resident demat account through the broker’s process.
- Update your tax status and file returns on the correct basis.
Your FEMA status and your income tax status may change on different dates. A chartered accountant can confirm both, and tell you how the holdings, TDS and any Indian tax already paid are treated in the transition year. Keep copies of every account closure letter, transfer confirmation and TDS certificate, because you may need them for later returns and for questions from the tax department or your bank.
14. How is NRI investment in Indian stock market taxed in your country of residence?
India taxes the gains, but your country of residence may also tax them, so check for a tax treaty and foreign tax credit rules. A tax residency certificate and Form 10F are the usual papers to claim treaty benefits in India. Your home country will have its own forms and reporting rules.
Many countries require residents to report foreign bank accounts, securities and income. Rules differ widely, and penalties for missing a report can be severe, so ask a qualified adviser in your country. Keep your Indian contract notes, TDS certificates and capital gains statements in one folder for both filings.
Why does this matter for NRI investment in Indian stock market?
A gain taxed in India at 12.5% may be taxed again at home, or may give you a credit. Which one applies depends on the treaty and on your home-country law. This guide cannot cover every country, so treat the Indian rates as only half of the tax picture.
15. What are the risks and common mistakes in NRI investment in Indian stock market?
What are the most common mistakes?
Treating a resident demat account as usable. It is not. You need an NRI-tagged account.
Assuming intraday and F&O are allowed. They are not for NRIs.
Mixing NRE and NRO funds. It confuses repatriation and tax records.
Ignoring treaty paperwork. Without a tax residency certificate and Form 10F, you may pay the higher domestic rate.
Forgetting FATCA limits on mutual funds. Some fund houses do not accept investors from the US and Canada.
Not keeping holding-period records. Shares bought in several lots and several accounts have different purchase dates, and the date decides whether a gain is taxed at 20% or 12.5%. Keep a simple sheet with the date, quantity and price of every buy.
Waiting too long to claim a TDS refund. Excess TDS comes back only after you file and the return is processed, so a late return delays your money and may add interest or penalties. File on time every year.
Following tips from messaging groups. Guaranteed return claims are a warning sign.
16. Analyst’s note and bottom line
- What stands out: the limit change is large on paper, but the practical effect on NRI investment in Indian stock market for retail investors is small. The wider eligibility for foreign individuals is the bigger structural change.
- Easy to miss: the notified individual limit reads “less than 10%”, which is not the same as exactly 10%. Many articles drop that detail.
- What would change the view: operating circulars from the RBI and SEBI, or banks restricting PIS accounts for the new class of investors.
- Caution: tax and repatriation rules are where mistakes cost money, not the holding limit.
- Action for the reader: fix your account route and tax plan before choosing any stock.
Bottom line
NRI investment in Indian stock market is open through NRE and NRO accounts, NRI demat accounts and the PIS route, on a delivery basis. Since 12 June 2026 an individual can hold just under 10% of a listed company and all such investors up to 24%. Equity gains are taxed at 20% and 12.5% with TDS, and NRO repatriation is capped at USD 1 million. This guide is educational and recommends no stock.
Next read: see how gains are taxed in our capital gains tax on shares guide.
Part of the Personal Finance and Tax series on PositionalCalls.
PositionalCalls WhatsApp channel
Plan your next NRI investment with clear rules
- Tax and TDS explainers for overseas investors
- IPO guides that show how NRIs can apply
- Updates when holding limits or forms change
FAQs on NRI investment in Indian stock market
Can an NRI invest in the Indian stock market?
Yes. NRI investment in Indian stock market is allowed in listed shares, ETFs, mutual funds and IPOs through NRE or NRO accounts linked to an NRI demat and trading account. Most direct share trades use the RBI Portfolio Investment Scheme, on a delivery basis only.
What is the limit for NRI investment in Indian stock market from 2026?
From 12 June 2026, an individual may hold below 10% of a listed company’s paid-up equity (earlier 5%), and all such individuals together up to 24% (earlier 10%). Check your bank for how it applies.
What is a PIS account for NRI investment in Indian stock market?
A PIS account is a bank account designated by the RBI to route and report NRI share trades. NRE PIS is repatriable; NRO PIS is non-repatriable. The bank issues a permission letter and reports every trade to the RBI.
Can an NRI do intraday trading in India?
No. NRI investment in Indian stock market is on a delivery basis only. Intraday, short selling and futures and options are not allowed for NRIs under the PIS route. Check your broker’s NRI product list before placing orders.
Do I need a PIS account to invest in mutual funds?
No. Mutual funds need only an NRE or NRO account, not PIS. Some fund houses restrict investors from the US and Canada because of FATCA, so check eligibility with the fund house before applying.
Gains from NRI investment in Indian stock market on listed equity are taxed at 20% if short-term and 12.5% above Rs 1.25 lakh if long-term, plus surcharge and 4% cess. TDS is deducted by the broker, and you claim any excess back by filing a return.
How much money can an NRI repatriate from India?
Proceeds from NRI investment in Indian stock market funded from an NRE account can generally be sent abroad after tax. From an NRO account, repatriation is capped at USD 1 million, with Forms 15CA and 15CB. Confirm whether your bank applies the cap per financial year.
Can an NRI apply for an IPO under NRI investment in Indian stock market rules?
Yes. NRIs can generally apply for IPOs from NRE or NRO accounts on a non-repatriation basis, subject to the issue’s terms. Shares are credited to your NRI demat account. See our IPO allotment guide for the process.
Is TDS deducted on dividends paid to an NRI?
Yes. Dividends paid to non-residents attract 20% base TDS, plus surcharge and cess, or a lower rate under a tax treaty if you provide a residency certificate and Form 10F. Check the company or broker notice.
Should an NRI invest in the Indian stock market now?
This site gives no buy or sell advice. Whether NRI investment in Indian stock market suits you depends on your goals, risk, tax in your country of residence and repatriation needs. Discuss it with a qualified adviser.
Sources
- law-firm note on the Third Amendment Rules, 2026 (law-firm analysis of the Gazette notification S.O. 3030(E), 12 June 2026)
- SCC Online explainer of the Third Amendment Rules, 2026 (legal publisher)
- Income Tax Department page on long-term capital gains (primary)
- Income Tax Department page on short-term capital gains (primary)
- Named, not linked: Taxguru and Vinod Kothari notes on the Third Amendment Rules; bank pages on PIS from Federal Bank, RBL Bank and IDFC FIRST Bank; broker TDS schedule; Motilal Oswal and DBS tax pages, as of 26 October 2026, 11:00 AM IST.
Editorial disclosure: PositionalCalls.com is an independent Indian stock market research and education site founded by Shubham Chaudhary. It is not SEBI registered. This guide is educational only and is not legal, tax or investment advice. It gives no targets, buy or sell calls or guarantees. How I researched this NRI investment in Indian stock market guide: I read law-firm and legal-publisher notes on the June 2026 amendment, Income Tax Department pages and bank PIS pages, and cross-checked tax rates across several publishers as of 26 October 2026, 11:00 AM IST. Rules for NRIs are detailed, so confirm with your bank and a chartered accountant.
Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive