
Sector Outlook · Paints
This paint sector outlook 2026 page tests India’s paint volumes, raw-material costs and the Q2 FY27 results of Asian Paints, Berger, Kansai Nerolac and Birla Opus against guidance, records where numbers disagree and gives no stock picks.
Quick answer
The paint sector outlook 2026 is recovering volumes with squeezed margins. Asian Paints’ decorative volume grew 6.4% in Q2 FY27, below its 8% to 10% guidance for the year, and its operating margin fell 2.02 points to 15.6% despite price hikes.
Key takeaways on the paint sector outlook 2026
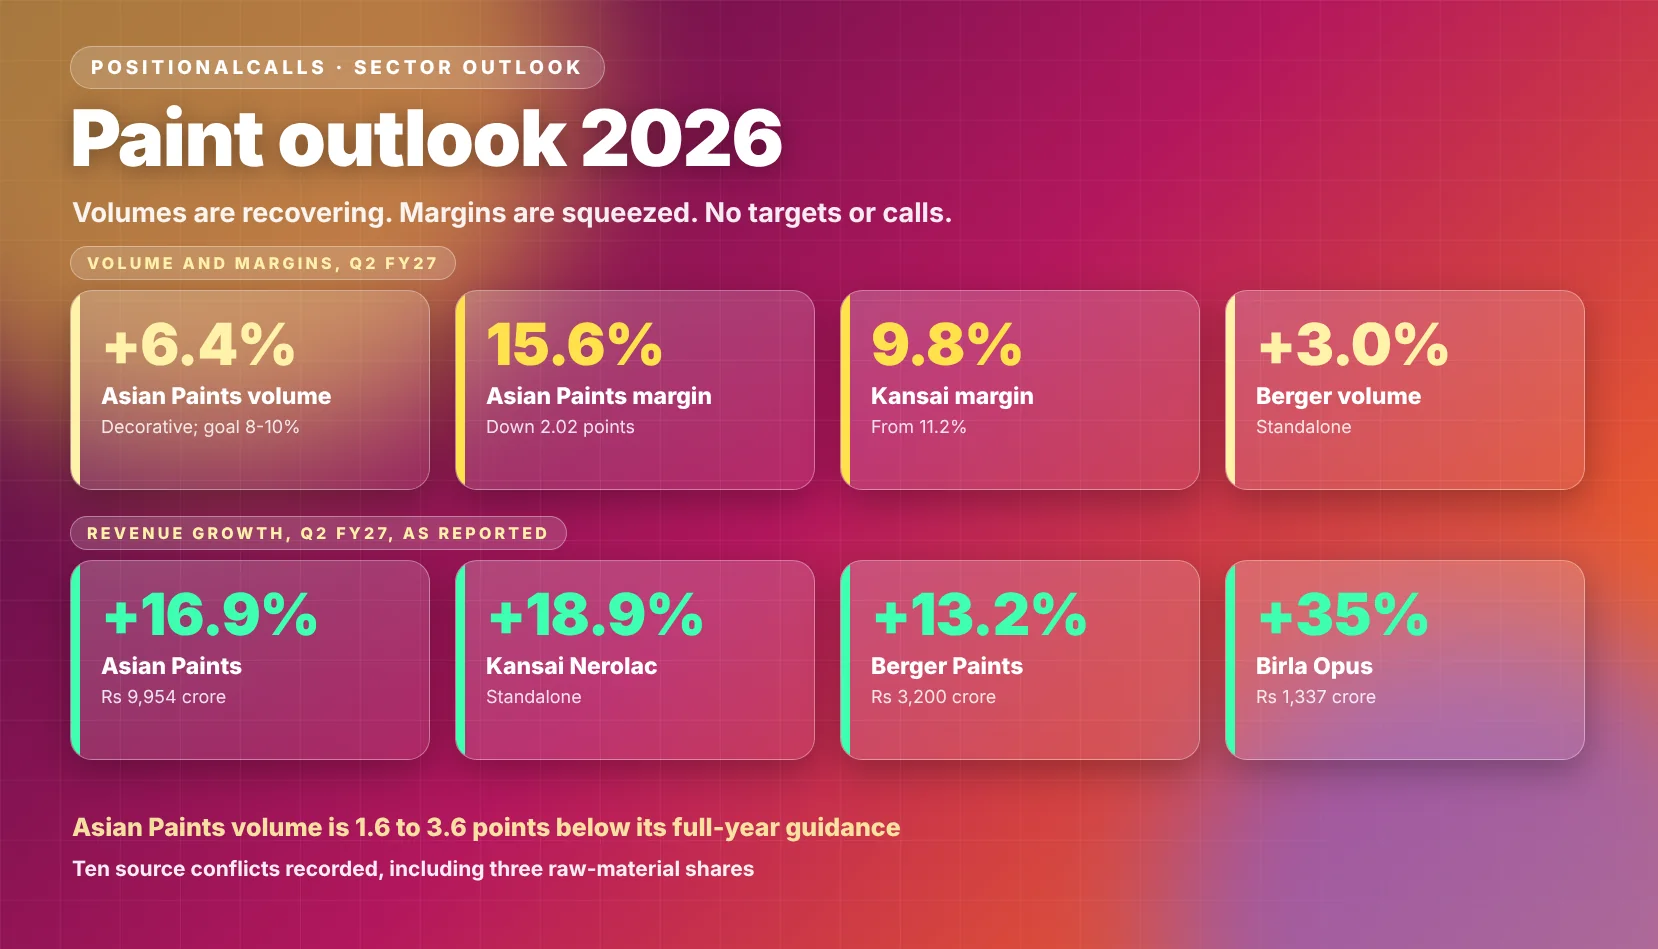
- Volumes: Asian Paints grew 6.4% in decorative volume and Berger 3.0% company-wide, while industry checks in October gave 2% to 6%.
- Revenue: Asian Paints grew 16.92%, Kansai Nerolac 18.9% and Berger 13.2%, helped by price increases.
- Margins: Asian Paints’ margin fell 2.02 points and Kansai Nerolac’s 1.4 points.
- Costs: crude derivatives and titanium dioxide are about half to over 60% of raw-material cost, by source.
- Doubt: ten source conflicts are recorded, including three versions of the raw-material share.
In plain words: People are buying more paint than a year ago, but not as much as the biggest company hoped, and the materials used to make paint cost more. Companies raised prices, so sales grew faster than volumes, yet profit margins still shrank. New rivals add pressure on prices.
Data note: as of Saturday, 21 November 2026, 1:45 PM IST. Company figures are for the quarter ended 30 September 2026, as relayed by the sources named, and industry checks are brokerage reports as relayed by the sources named. I did not open the exchange filings or company presentations, and two industry items are used as search snippets because their pages did not load. Lines marked as my calculation are my own arithmetic. Analysis only: no buy or sell calls, targets or price zones.
Latest update
- 21 November 2026, 1:45 PM IST: company results run to Asian Paints on 29 October, Kansai Nerolac on 4 November, Berger on 5 November and Grasim on 13 November.
Paint sector outlook 2026: where does the sector stand in November 2026?
The paint sector outlook 2026 shows revenue growth led by price increases, volume growth below guidance and margins under pressure. The table collects the latest dated figures this page uses.
| Measure | Latest figure | Period | Source named |
|---|---|---|---|
| Asian Paints revenue | Rs 9,953.89 crore, up 16.92% | Q2 FY27 | JM Financial, Multibagg |
| Asian Paints profit | Rs 1,067.6 crore, up 7.45% | Q2 FY27 | JM Financial |
| Asian Paints decorative volume | Up 6.4%, with value up 14.5% | Q2 FY27 | Indian Chemical News, Multibagg |
| Kansai Nerolac revenue | Standalone Rs 2,268.77 crore, up 18.9% | Q2 FY27 | Multibagg |
| Berger revenue | Consolidated Rs 3,200.37 crore, up 13.2% | Q2 FY27 | This site’s Berger page |
| Industry volume growth | 4% to 6% in October (Systematix); 2% to 4% in a 27 October channel check | October 2026 | Newkerala, search snippets |
Cite this table: Paint snapshot, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, figures as reported by the sources named.
Two readings of this paint sector outlook 2026 table are worth keeping apart. Revenue is growing at double digits, but most of it is price: Asian Paints’ decorative value grew 14.5% on 6.4% volume. Profit is growing far slower than revenue, which is where cost pressure shows.
The sector overlaps with other pages on this site. Household demand ties to the consumption sector outlook 2026, repainting and new-build demand to the real estate sector outlook 2026 and industrial coatings to the auto sector outlook 2026. This page stays on paint volumes, costs, pricing and competition.
How fast are paint volumes growing against guidance in the paint sector outlook 2026?
Reported volume growth sits between 2% and 6.4%, below the 8% to 10% that Asian Paints guided for FY27. The table lines up the forecasts, checks and reported figures by date.
| Date | Volume reading | Type | Source named |
|---|---|---|---|
| FY26 | Industry volume growth of 4% to 5% expected | CRISIL forecast | NBMCW |
| Q2 FY26 | Industry aggregate volume growth of 3.5% to 4% | Reported base | Business Standard |
| 6 to 7 September 2026 | Asian Paints guided 8% to 10% volume growth for FY27; Berger and JSW Dulux projected double-digit growth | Management guidance | PTI via HDFC Sky |
| 1 October 2026 | Industry volume growth of 4% to 6% in October | Systematix forecast | Newkerala, snippet |
| 27 October 2026 | Volumes up 2% to 4% across regions; festive boost yet to appear | Brokerage channel check | Newkerala, snippet |
| Q2 FY27 | Asian Paints decorative volume up 6.4% against a base of about 11%; domestic coatings up 6.8% | Reported | Indian Chemical News, Sovrenn |
| Q2 FY27 | Berger standalone volume up 3.0%, against 5.6% in H1 | Reported | Multibagg |
Cite this table: Paint volume path, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as reported; forecasts are tested against reported figures where they overlap.
Asian Paints’ Q2 volume is short of its full-year guidance range, which is not itself a miss because the guide covers the year. Berger said a later Diwali moved festive demand into Q3 and extended rain disrupted eastern markets, per Multibagg, so Q3 will say more than Q2. Berger did not disclose a decorative-only volume figure, so its 3.0% should not be read as one.
Did the industry volume forecast against reported figures hold?
Systematix’s 4% to 6% October view and the 2% to 4% channel check overlap only at the edges. The reported company volumes are above the channel check for Asian Paints and below it for Berger, so the two industry readings do not settle the picture. I could not open either Newkerala page and use only the search snippets.
What are raw-material costs and price hikes doing in the paint sector outlook 2026?
Crude derivatives and titanium dioxide are a large share of cost, and price hikes of about 3% are being taken to offset them. The table lists the cost evidence and the pricing response.
| Item | Evidence | Source named |
|---|---|---|
| Raw-material share | Crude derivatives and titanium dioxide with binders over 60% of raw-material cost; about 50% to 60% of production costs; roughly half | Business Standard, Whalesbook, Invezz |
| Titanium dioxide price | Rose from about Rs 300 a kg to Rs 370 a kg over the period described | Ventura Securities |
| Global pigment outlook | Cautious recovery in 2027; returning capacity and weak housing could limit price rises | PCI Magazine, 13 November 2026 |
| Supply | Availability of titanium dioxide, rutile and VAM remains a concern | Systematix via Newkerala, snippet |
| Asian Paints pricing | A hike of about 3% from 1 November 2026 | Sahi |
| Industry pricing | A further 2% to 3% increase possible after Diwali, by end 2026 or early 2027 | Systematix via Newkerala, snippet |
| Currency and logistics | Kansai Nerolac’s managing director cited rupee depreciation, higher import costs and supply-chain disruption as risks | PTI via HDFC Sky |
Cite this table: Paint costs and pricing, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as reported by the sources named.
The pass-through has lagged. Business Standard reported in March that price hikes did not fully compensate for rising raw-material costs, and the Q2 margins confirm it: Asian Paints’ operating margin fell 2.02 points and Kansai Nerolac’s fell from 11.2% to 9.8%. The remaining question is whether the 3% hike restores any of that.
Why does the raw-material share differ between sources?
The three figures appear to measure different things: one is a share of raw-material cost, one a share of production cost, and one a rough half. The conflicts table records them side by side, and this page does not pick one.
What did paint companies report for Q2 FY27 in the paint sector outlook 2026?
Revenue grew 13% to 19% at the three listed leaders, while profit grew 5% to 9% and margins fell. Figures are for the quarter ended 30 September 2026, as reported.
| Company | Q2 FY27 revenue | Q2 FY27 profit | Volume and margin | Source named |
|---|---|---|---|---|
| Asian Paints, consolidated | Rs 9,953.89 crore, up 16.92% | Rs 1,067.6 crore, up 7.45% from Rs 993.59 crore | Decorative volume 6.4%, value 14.5%; operating margin 15.6%, down 2.02 points | JM Financial, Multibagg |
| Berger Paints, consolidated | Rs 3,200.37 crore, up 13.2% | Rs 217.10 crore, up 5.2% | Standalone volume 3.0%; decorative value up 10% | This site’s Berger page, Multibagg |
| Kansai Nerolac, standalone | Rs 2,268.77 crore, up 18.9% | Rs 148.64 crore, up 8.8%; consolidated Rs 143.99 crore | Operating margin 9.8% against 11.2% | Multibagg |
| Birla Opus, within Grasim | Rs 1,337 crore, up 35% | Not shown separately | Not disclosed here | This site’s Grasim page |
Cite this table: Paint company results, Q2 FY27, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as reported; this page does not rank the companies.
Each line needs a qualifier. Kansai Nerolac’s figures retrospectively include the Nerofix amalgamation from 1 April 2025, per Multibagg, so growth is on a restated base. Berger’s profit rose 5.2% consolidated but fell 7.3% standalone on this site’s page. Asian Paints’ international business grew 29.5%, per Indian Chemical News, which is a segment and not the company figure. The site’s Asian Paints Q2 results and Berger Paints Q2 results pages carry the company detail.
How do margins and segments compare in the paint sector outlook 2026?
| Company | Segment and margin detail | Source named |
|---|---|---|
| Asian Paints | Domestic coatings value up 16.4% and volume up 6.8%; industrial coatings value up 31.8%; international business up 29.5%; interim dividend Rs 5.75 | Indian Chemical News, Multibagg |
| Berger Paints | H1 revenue Rs 6,784.1 crore, up 12.5%; Q2 operating margin about 11.6% against 12.4%, this site’s derivation | This site’s Berger page |
| Kansai Nerolac | H1 revenue Rs 4,601.60 crore, up 14.2%; growth across decorative and industrial; management cites input-cost pressure | Indian Chemical News, Multibagg |
| Asian Paints, Q1 comparison | Q1 revenue Rs 10,542 crore and profit Rs 1,559 crore, single source | Construction World |
Cite this table: Paint segment and margin detail, Q2 FY27, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as reported.
Industrial and international growth supported Asian Paints’ revenue while its core decorative volume lagged guidance. Kansai Nerolac’s industrial business is a larger part of its mix, which is a reason its revenue growth outran Berger’s. The wider consumer demand picture sits in the consumption sector outlook 2026.
How is competition shaping the paint sector outlook 2026?
The three listed leaders still hold over three-fourths of the market, but new entrants are growing quickly. The table lists the players and the evidence.
| Player | Evidence | Source named |
|---|---|---|
| Asian Paints, Berger, Kansai Nerolac | Together hold over three-fourths of India’s paint market | PTI via Millennium Post |
| Birla Opus (Grasim) | Quarterly run-rate of Rs 900 crore to Rs 1,050 crore over three quarters to late 2025; Rs 1,337 crore in Q2 FY27 | Business Standard, this site’s Grasim page |
| JSW Paints | Acquired a majority stake in Akzo Nobel India (Dulux), with approval to take up to 75% | Business Standard |
| Pidilite | Advancing under the Haisha brand | Business Standard |
| Berger response | Ramped up expansion to fend off Birla Opus and JSW Dulux | Business Standard topic page, 22 September 2026 |
| Regulation | An antitrust probe involving Asian Paints is noted as a pressure | Whalesbook |
Cite this table: Paint competition, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as reported by the sources named.
Birla Opus’ Rs 1,337 crore is above the earlier run-rate, which suggests growth resumed after the plateau Nuvama described. Early in the cycle, Asian Paints lost ground to it, per Business Standard in November 2025, but regained some share in Q2 FY26. The Q2 FY27 data in this page do not include market-share figures, so the share effect is not measured here.
What do the derived numbers show in the paint sector outlook 2026?
Ten checks tie reported figures together and show how much of revenue growth is price. Every row in this table is my calculation from the sourced figures above.
PositionalCalls WhatsApp channel
Follow sector pages in one place
- New sector outlooks as they are posted
- Results summaries without tips
- A message when a page is updated
| Check | My calculation | Reading |
|---|---|---|
| Asian Paints volume against guidance | 8% to 10% guided less 6.4% reported = 1.6 to 3.6 points short | Q2 only; the guide is for the full year |
| Asian Paints revenue against profit | 16.92% less 7.45% = 9.5 points | Revenue grew more than twice as fast as profit |
| Asian Paints decorative price and mix | 1.145 / 1.064 = about 7.6% value gain per unit of volume | Price and mix explain more than half of value growth |
| Berger standalone price and mix | 1.119 / 1.03 = about 8.6%, if the 3.0% volume applies to all sales | Berger did not disclose a decorative-only volume |
| Asian Paints sequential change | Profit 1,067.6 / 1,559 = down 31.5%; revenue 9,953.89 / 10,542 = down 5.6% | Q1 figures rest on one source |
| Kansai Nerolac margin | 9.8% less 11.2% = 1.4 points; 223.23 / 2,268.77 = 9.84% | Ties to the reported 9.8% |
| Berger margin | 11.6% less 12.4% = 0.8 points | This site’s derived Q2 figures |
| Birla Opus against Asian Paints | 1,337 / 9,953.89 = 13.4% of Asian Paints’ consolidated revenue | Different scope: Asian Paints includes international and industrial |
| Birla Opus against its earlier run-rate | 1,337 against 900 to 1,050 = 27% to 49% higher | Run-rate from late 2025 reports |
| Kansai Nerolac Q2 against Q1 | H1 4,601.60 less Q2 2,268.77 = Q1 about 2,332.83; Q2 down 2.7% | Seasonal drop after the first quarter |
Cite this table: Derived paint numbers, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, my calculation from the sourced figures.
How much of paint revenue growth is price?
For Asian Paints’ decorative business, about 7.6% of the 14.5% value growth is price and mix on my calculation, and Berger’s implied gain is similar. That is why revenue grew faster than volume and why margins still fell: the gain did not cover the cost increase.
What do management and agencies say about paints, as reported?
Reported views are constructive on demand and cautious on costs and competition, and none of them is a stock call on this page. The table lists statements with dates and sources, and later results will test each forecast against reported figures.
| Source | Date | Reported view | Source named |
|---|---|---|---|
| Asian Paints chief executive | September 2026 | Demand decent through the quarter; FY27 volume growth of 8% to 10% expected | PTI via HDFC Sky |
| Berger and JSW Dulux | September 2026 | Projected double-digit growth for FY27 | PTI via HDFC Sky |
| Kansai Nerolac managing director | September 2026 | Geopolitics, crude, rupee and import costs remain the key risks | PTI via HDFC Sky |
| CRISIL | FY26 outlook | Volume to rise 4% to 5% on weak urban demand and tepid auto sales | NBMCW |
| Nomura Research | March 2026 | The sector is entering a consolidation phase with limited market share movement | Business Standard |
| Systematix | 1 October 2026 | October to see good growth; competition to stay high; raw-material availability a concern | Newkerala, snippet |
| JP Morgan | April 2026 | Demand holds up, with some moderation after mid-March | Upstox |
Cite this table: Management and agency views on paints, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as reported; each is a single-source item and none is a stock recommendation.
Do the views agree on timing of recovery?
They agree on direction and differ on pace: CRISIL’s 4% to 5% for FY26 and the 8% to 10% guided for FY27 are far apart, and Q2 delivered between. This page gives no call and does not repeat any broker’s stock names or price targets.
Where do sources disagree on the paint sector outlook 2026?
Ten conflicts appear in the data, and each changes how a number reads. The table shows both versions and the one this page uses.
| Item | Version A | Version B | How this page handles it |
|---|---|---|---|
| Asian Paints Q2 revenue | Rs 9,953.89 crore (JM Financial, Multibagg) | Rs 9,976.51 crore and about Rs 9,977 crore (InCred Money) | Uses Rs 9,953.89 crore |
| Asian Paints volume | Decorative 6.4% (Indian Chemical News) | Domestic coatings 6.8%; about 7% (Sovrenn AI summary) | Uses 6.4% for decorative and labels 6.8% |
| Industry volume in October | 4% to 6% (Systematix, 1 October) | 2% to 4% (channel check, 27 October) | Shows both with dates |
| Price headline | Prices rising 16% to 17% (headline of the 27 October item) | A further 2% to 3% hike after Diwali (Systematix) | Page not opened; does not use the headline |
| Raw-material share | Over 60% of raw-material cost (Business Standard) | About 50% to 60% of production costs (Whalesbook); roughly half (Invezz) | Shows all three |
| Kansai Nerolac profit | Standalone Rs 148.64 crore | Consolidated Rs 143.99 crore | Labels the basis |
| Berger volume | Standalone company-wide 3.0% | No decorative-only volume disclosed | Does not treat 3.0% as decorative |
| Berger profit | Consolidated Rs 217.10 crore, up 5.2% | Standalone Rs 163.31 crore, down 7.3% | Shows both |
| Asian Paints growth headline | 30% revenue growth to Rs 1,096 crore (Investywise) | Consolidated up 16.92%; the 30% line is the international business | Uses the consolidated figure |
| Asian Paints guidance year | 8% to 10% volume for FY26 (Business Standard, November 2025) | 8% to 10% for FY27 (PTI, September 2026) | Uses FY27 from PTI |
Cite this table: Source conflicts in paint data, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, as recorded from the sources named.
Which conflict matters most for comparing paint companies?
Most of these are definition gaps: standalone against consolidated, segment against company, and forecast against reported. The two that change the reading are the volume basis and the industry volume range, and the paint sector outlook 2026 on this page does not rest on either.
What are the risks to the paint sector outlook 2026?
Six risks could make the paint sector outlook 2026 wrong, and two are visible in reported numbers. Red marks risks that already show in data, amber marks measures to watch, and blue marks risks that depend on future events.
The risks feed each other: higher costs need price hikes, price hikes can weaken volume, and competition limits how much of a hike sticks.
Bottom line
The paint sector outlook 2026 is recovering on demand and weak on margins. Revenue grew at double digits, but volumes trail guidance and margins fell at Asian Paints and Kansai Nerolac, so price hikes alone do not settle the outlook.
What should you watch next in the paint sector outlook 2026?
Watch Q3 volumes, the November price hike and raw-material prices. The table gives each item and the figure to compare it against.
| Item to watch | Why it matters | Compare against |
|---|---|---|
| Q3 FY27 results, January and February 2027 | Tests whether festive demand shifted into Q3 | Asian Paints decorative volume 6.4%; Berger standalone 3.0% |
| Effect of the November price hike | Tests margin recovery | Asian Paints operating margin 15.6%; Kansai Nerolac 9.8% |
| Titanium dioxide and crude prices | Tests cost pressure | Rs 370 a kg titanium dioxide level cited by Ventura |
| Birla Opus revenue in Grasim’s next result | Tests competitive intensity | Rs 1,337 crore in Q2 FY27 |
| Berger decorative volume disclosure | Allows a like-for-like volume comparison | Standalone 3.0% company-wide |
| Industry volume checks for November and December | Tests whether 2% to 6% widens or narrows | October readings of 2% to 4% and 4% to 6% |
Cite this table: Paint watch list, PositionalCalls, Saturday, 21 November 2026, 1:45 PM IST, dates as reported; later dates may move.
Industry checks say nothing about profit, so use the quarterly results and check which profit line is quoted.
Paint sector outlook 2026 in Hinglish: short summary
Paint companies ka revenue badh raha hai, lekin volume guidance se kam hai aur margin gir rahe hain. Asian Paints ka decorative volume Q2 FY27 mein 6.4% badha, jabki FY27 ke liye 8% se 10% ka guidance tha. Operating margin 2.02 points gir kar 15.6% par aa gaya.
Kansai Nerolac ka margin 9.8% raha aur Berger ka standalone volume 3.0% badha. Crude aur titanium dioxide ki costs ek bada risk hain, aur Birla Opus jaise naye players competition badha rahe hain. Yeh sirf jaankari hai: koi target, rating ya buy-sell salaah nahi.
What pages sit beside this paint page?
The company results pages and the other sector outlooks give the surrounding layer.
- Sector hub: sector outlook India, the sector pages
- Company results: Asian Paints Q2 results, Berger Paints Q2 results and Grasim Q2 results
- Related sector pages: consumption sector outlook 2026, real estate sector outlook 2026 and auto sector outlook 2026
- Scorecard: Q2 FY27 results scorecard
This page is the sector view. It does not rank companies or give targets. The results pages show the company figures, so use them for that job.
Sources for this paint page
Every figure comes from the sources below, read on 21 November 2026. I did not open exchange filings or company presentations for each figure, so use the links to reach the primary source. Two Newkerala pages did not load and are used only as search snippets. Berger, Grasim and Asian Paints’ dividend figures come from this site’s own result pages.
- NBMCW: CRISIL paint sector FY26
- Business Standard: Crude and competition vs margins
- Business Standard: Near-term margin pressure
- Business Standard: Nuvama on paints H2
- Business Standard: Asian Paints Q2 FY26
- Business Standard: Paint brands topic page
- Business Standard: Paint companies topic page
- HDFC Sky: Paint makers expect healthy FY27 demand
- Construction World: Paint makers FY27 demand
- Millennium Post: Paint makers expect uptick
- Newkerala: Paint demand October, snippet only
- Newkerala: Paint demand muted, snippet only
- Ventura: Paint stocks and crude
- Invezz: Paint stocks and crude
- Whalesbook: Paint firms price hike pressure
- PCI Magazine: Titanium dioxide recovery
- Sahi: Asian Paints 3% price hike
- Upstox: Sector watch paints
- JM Financial: Asian Paints Q2 PAT
- Indian Chemical News: Asian Paints Q2 FY27
- Multibagg: Asian Paints Q2 FY27
- InCred Money: Asian Paints Q2 FY27
- Sovrenn: Asian Paints Q2 FY27
- Investywise: Asian Paints Q2 FY27
- Indian Chemical News: Kansai Nerolac Q2 FY27
- Multibagg: Kansai Nerolac Q2 revenue
- Multibagg: Kansai Nerolac margins
- Multibagg: Berger Q2 FY27 decorative growth
Where a source is a news report on company or industry data, the report is named, not the company. If any figure differs from the primary release, the primary release governs.
PositionalCalls WhatsApp channel
Keep sector updates together
- Quarterly result summaries
- Budget and policy changes
- Links to new sector pages
paint sector outlook 2026: frequently asked questions
What is the paint sector outlook 2026 for India?
Demand is recovering but margins are under pressure. Asian Paints reported decorative volume growth of 6.4% in Q2 FY27 against a guided 8% to 10% for the year, and its operating margin fell 2.02 points to 15.6%. Price hikes, crude-linked costs and new competitors such as Birla Opus shape the outlook.
How fast are paint volumes growing in 2026?
Reports differ by source and date. Systematix saw 4% to 6% industry volume growth in October, while a brokerage channel check reported 2% to 4% on 27 October. Asian Paints decorative volume grew 6.4% in Q2 FY27 and Berger’s standalone volume grew 3.0%, so company figures sit across that range.
Why are paint company margins falling in 2026?
Raw-material costs rose faster than prices. Crude derivatives and titanium dioxide are a large share of cost, with sources putting it at roughly half to over 60%. Kansai Nerolac’s margin fell to 9.8% from 11.2%, and Asian Paints’ fell to 15.6%, even as prices rose, so hikes have not fully offset costs.
Did Q2 FY27 paint results meet the volume guidance in the paint sector outlook 2026?
Not on the headline figure. Asian Paints guided 8% to 10% volume growth for FY27 but reported 6.4% for decorative paints in Q2, which is 1.6 to 3.6 points short on my calculation. Berger’s 3.0% is a company-wide standalone figure, not decorative only, so it is not directly comparable.
Why do sources disagree on paint sector numbers?
They use different bases and dates. Asian Paints revenue appears as Rs 9,953.89 crore and Rs 9,976.51 crore, its volume growth as 6.4% for decorative and 6.8% for domestic coatings, and raw-material share as half or over 60%. The conflicts table records ten gaps and how this page handles each.
What are the main risks in the paint sector outlook 2026?
Six risks stand out: falling margins despite price hikes, volume below guidance, titanium dioxide and crude costs, competition from Birla Opus and JSW Dulux, weaker rural demand and a regulatory probe. Kansai Nerolac’s margin fell 1.4 points and Asian Paints’ fell 2.02 points, so cost pressure already shows in results.
Is the paint sector outlook 2026 a call to buy paint stocks?
No. This page gives no target, rating, entry or exit level and no buy or sell call, and it leaves out brokerage stock preferences. It reports industry, company and cost figures with sources and dates, and it shows which numbers conflict. Treat it as analysis only, and check each company’s filing before acting.
How is the paint sector different from the consumption sector?
Paints sell to households, builders and industry, and their demand follows housing, repainting cycles and vehicle output as well as consumer spending. The consumption sector covers a wider set of everyday goods and services. This page stays on paint volumes, costs, pricing and competition, with the broader view on the consumption page.
What price hikes are paint companies taking?
Asian Paints plans a hike of about 3% from 1 November 2026, per Sahi. Systematix expected another 2% to 3% increase after Diwali, possibly by the end of 2026 or in early 2027. Companies have already taken several rounds this year to offset crude-linked costs, and they remain cautious about further increases.
What should I watch next in the paint sector outlook 2026?
Watch Q3 FY27 volumes, the effect of the November price hike, titanium dioxide and crude prices, and Birla Opus revenue. Compare Asian Paints’ 6.4% decorative volume, its 15.6% margin and Kansai Nerolac’s 9.8%. A later Diwali shifted some festive demand into Q3, so the next results will test that.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive