Earnings · Titan Company · Q2 FY27
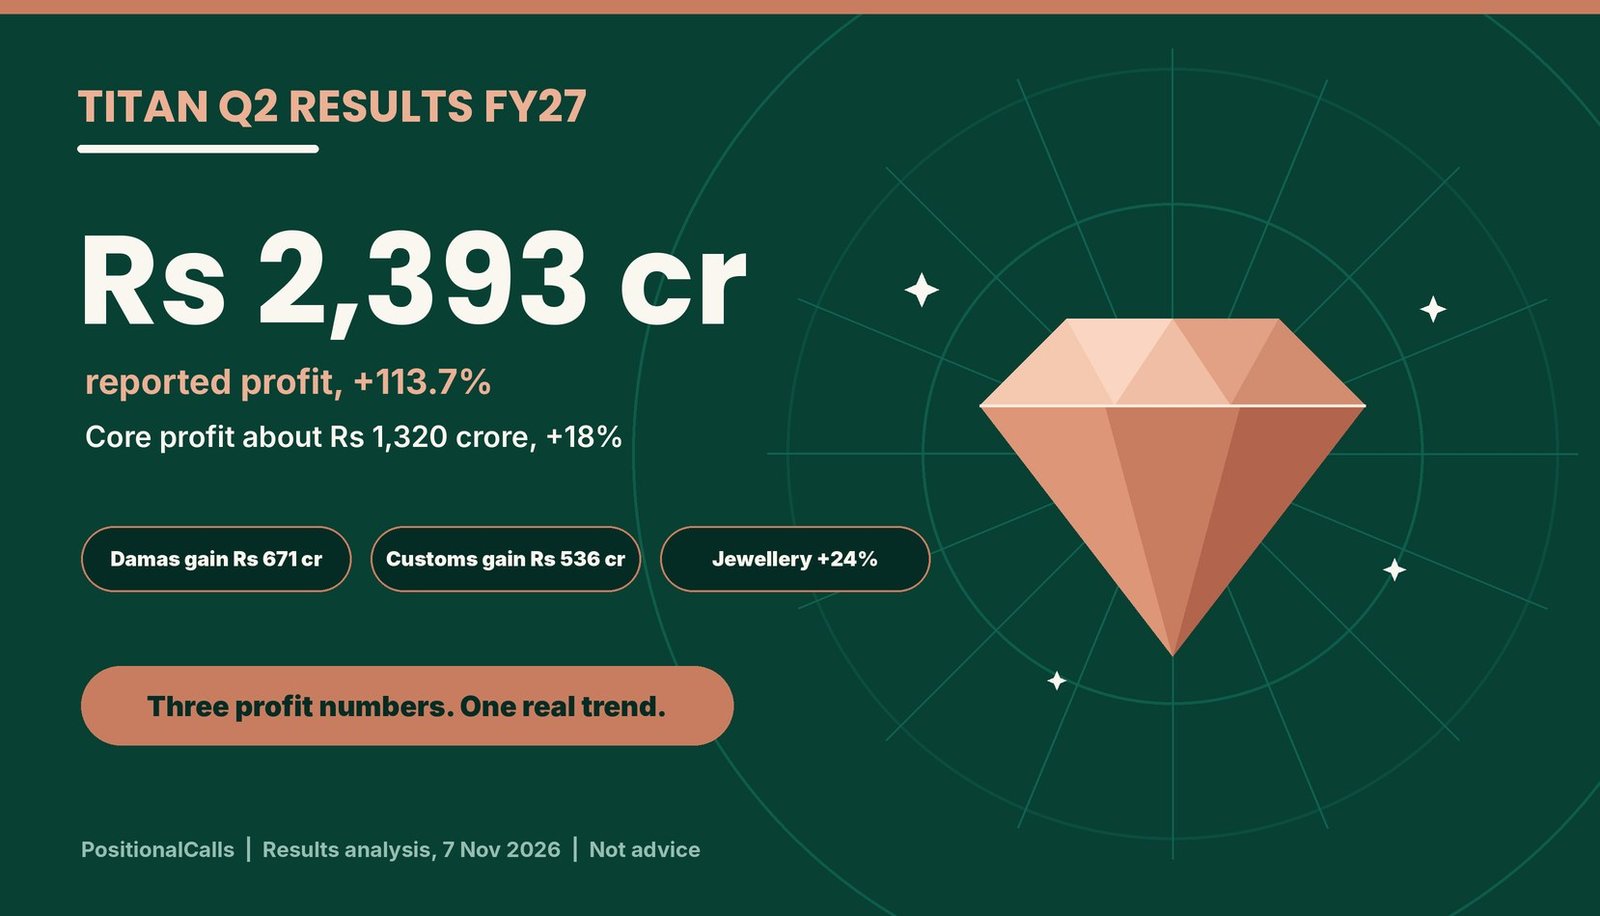
Titan reported a reported profit of Rs 2,393 crore, but two non-repeating items sit inside it. Here are the three profit numbers, the revenue conflicts, jewellery and margins, estimates, brokerage targets as reported and the price reaction.
Quick answer
Titan Q2 results FY27: Titan reported consolidated profit of Rs 2,393 crore on 5 November 2026, up 113.7%, but that includes a Rs 671 crore Damas gain. Without it profit was Rs 1,722 crore (+54%), which still holds a Rs 536 crore customs-duty gain. Core profit near Rs 1,320 crore rose about 18%.
Latest update (Saturday, 7 November 2026, 2:00 PM IST): Titan announced the Titan Q2 results FY27 after market hours on Thursday, 5 November (Business Today updated its report at 5:26 PM IST; the exact filing time was not found). On Friday, 6 November the stock rose about 3.4% to Rs 4,994, per Business Standard, after closing at Rs 4,831.55 on Thursday. Jefferies upgraded to Buy with a Rs 6,000 target and Nomura reported Rs 6,150, as reported on 6 November. I have not found any news after Friday night, and the next trading session is Monday, 9 November.
Key takeaways
- Three profit numbers: Reported Rs 2,393 crore (+113.7%); Rs 1,722 crore (+54%) without the Rs 671 crore Damas fair-value gain; about Rs 1,320 crore (+18%) core after also removing the Rs 536 crore customs gain (Business Standard).
- Revenue conflicts: Revenue from operations is Rs 20,610 crore (+10%) in one report and Rs 20,337 crore (+23.5%) in another; excluding bullion, growth is about 23% to 25%. Bases differ, shown openly below.
- Jewellery: Revenue Rs 17,495 crore (+24%), India +21% and international +105%; EBIT margin 13.1% with the customs gain and about 10.7% to 10.9% without it.
- Other businesses: Watches Rs 1,881 crore (+27%) at a 21.9% EBIT margin; EyeCare Rs 281 crore (+28%); CaratLane +31% with a 6.5% adjusted margin.
- Versus estimates: LSEG consensus was Rs 1,473 crore; Citi expected Rs 1,274 crore and Motilal Oswal Rs 1,419 crore. Whether those included the customs gain is not stated.
- Street and price: Targets as reported: Rs 5,330 to Rs 6,150 across six houses; shares rose 3.4% to about Rs 4,994 on 6 November (Business Standard).
Preview post, 30 October 2026Titan Q2 results preview: date, base to beat and key marks
- The 5 November board date and the Rs 1,120 crore base
- The Rs 407 crore Q1 customs gain and the scenario table
- The 7 October business update: consumer businesses +25%
Read the full preview post for the checklist and reading guide made before the numbers arrived.
This results analysis, 7 November 2026What the numbers showed
- Three profit figures and how they tie
- Revenue, jewellery and margin sources compared
- Estimates, brokerage targets as reported and the price reaction
A table further down grades each preview mark against the actual figure.
How to read this page: it is results analysis, not a recommendation. Brokerage ratings and targets are quoted as reported with their source and date; none is mine. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser.
In plain words: Titan made Rs 2,393 crore on paper, but Rs 671 crore of it is an accounting gain from revaluing a payment it may owe Damas’s minority owners, and Rs 536 crore of profit before tax came from higher customs duty on gold it already held. Neither repeats by itself. EBIT is operating profit before interest and tax, bps are hundredths of a percent, and LFL is like-for-like growth in the same stores.
Data note: as of Saturday, 7 November 2026, 2:00 PM IST. Figures come from press summaries of the filing (Kotak Neo, Business Today, Business Standard, Moneycontrol and Indian Opinion); I did not open the BSE or NSE filing. Sources disagree on revenue, EBITDA and some margins, and each conflict is shown openly. A Zeebiz headline gave profit as Rs 1,572 crore (+56%); that page could not be opened, so it is not used. Derived numbers are marked “my calculation”.
Titan Q2 results FY27: what Titan reported on 5 November
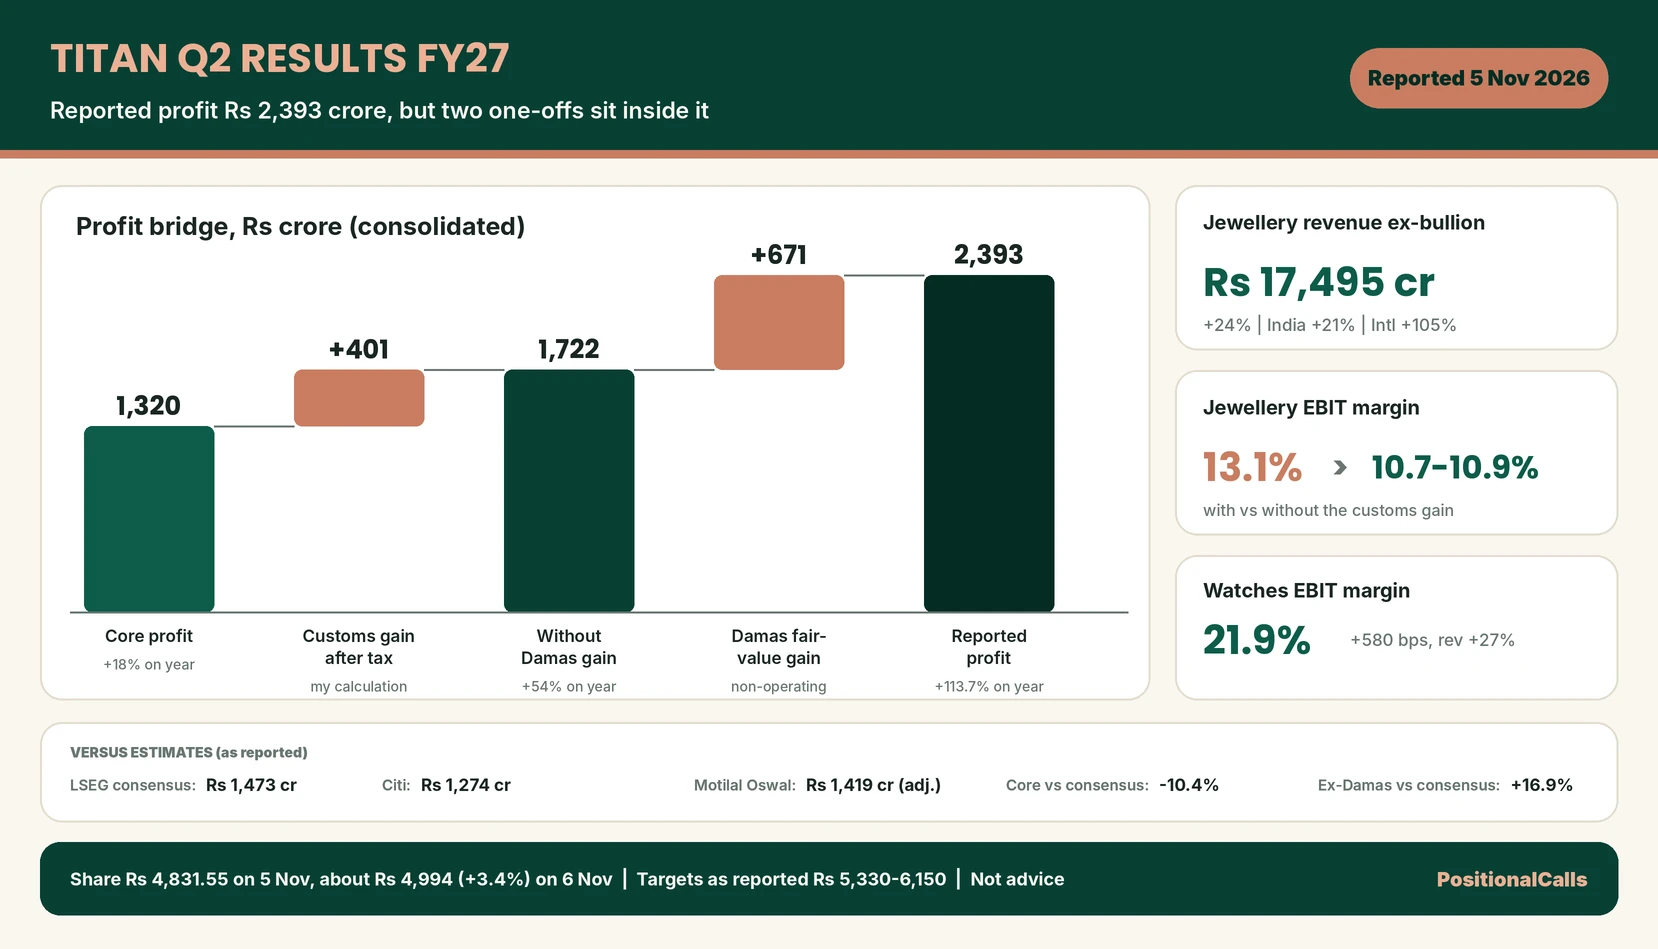
The Titan Q2 results FY27 show consolidated profit of Rs 2,393 crore (+113.7%) including a Rs 671 crore Damas gain, Rs 1,722 crore (+54%) without it, jewellery revenue of Rs 17,495 crore (+24%), and a board approval to raise up to Rs 2,500 crore through debentures.
| Measure (consolidated) | Q2 FY27 | Change on year | Source and note |
|---|---|---|---|
| Net profit as reported | Rs 2,393 crore | +113.7% | Moneycontrol; Indian Opinion; Business Standard says Rs 2,390 crore |
| Profit without the Damas fair-value gain | Rs 1,722 crore | +54% | Kotak Neo; Business Today; Moneycontrol |
| Core profit (also without the customs gain) | About Rs 1,320 crore | +18% | Business Standard; my calculation ties to it below |
| Profit before tax | Rs 2,329 crore | +53% | Kotak Neo; margin 11.3% of total income |
| Profit before tax without the customs gain | Rs 1,793 crore | +18% | Kotak Neo; margin 8.7% |
| EBIT | Rs 2,865 crore | +59% | Business Today; Rs 1,799 crore a year earlier |
| Jewellery revenue ex-bullion | Rs 17,495 crore | +24% | Kotak Neo; Business Today |
| Half-year profit without the Damas gain | Rs 3,499 crore | +58% | Kotak Neo; Q1 Rs 1,777 crore plus Q2 Rs 1,722 crore (my calculation) |
Cite this table: PositionalCalls, “Titan Q2 FY27 Results Table, as of 7 November 2026”.
The Titan Q2 results FY27 came with the company’s statement that growth was broad-based, quoted by Kotak Neo as “healthy, broad-based growth” from Ajoy Chawla. The headline number is easy to misread, because two non-repeating items sit inside it. The rest of this page separates them, compares the sources, and ties the figures to the preview post published on 30 October. The half-year line ties exactly: Rs 1,777 crore in Q1 FY27 plus Rs 1,722 crore in Q2 FY27 is Rs 3,499 crore (my calculation), which is the figure Kotak Neo gives for the half-year without the fair-value credit.
Titan Q2 results FY27 profit: Rs 2,393 crore, Rs 1,722 crore or Rs 1,320 crore?
The Titan Q2 FY27 profit has three correct values for different questions: Rs 2,393 crore is the statutory profit, Rs 1,722 crore removes the Rs 671 crore Damas liability gain, and about Rs 1,320 crore also removes the after-tax effect of the Rs 536 crore customs-duty gain.
| Step | Rs crore | What it is | Check |
|---|---|---|---|
| Reported consolidated profit | 2,393 | Statutory profit after tax | Moneycontrol; Indian Opinion (its analysis text says 2,391) |
| Less Damas fair-value gain | -671 | Remeasuring the put-option liability for Damas’s minority owners; Kotak Neo calls it non-operational | 2,393 minus 671 is 1,722 |
| Profit without the Damas gain | 1,722 | Includes the customs-duty gain | +54% on Rs 1,120 crore |
| Less customs gain after tax (my estimate) | -401 | Rs 536 crore at an assumed 25.17% tax rate | 536 times 0.7483 is 401 |
| Core profit | 1,321 | Business Standard gives about Rs 1,320 crore, +18% | 1,321 over 1,120 is +18% (my calculation) |
Cite this table: PositionalCalls, “Titan Q2 FY27 Profit Bridge, as of 7 November 2026”.
The bridge ties, which is the test I trust most. Rs 2,393 crore less Rs 671 crore equals Rs 1,722 crore, and Rs 1,722 crore less the after-tax customs gain lands within Rs 1 crore of Business Standard’s core figure. The tax rate of 25.17% is my assumption, the same one used in the preview post, not a rate Titan disclosed for this item. The Titan Damas fair value gain exists because Titan bought a 67% stake in Damas, and the value of the put option held by the minority owners fell, so the liability was written down by Rs 671 crore (Business Standard; Kotak Neo). That is a gain on paper that arrives without any jewellery being sold.
The Titan customs duty gain is different in kind. Business Standard says the customs duty on gold rose from 6% to 15%, which lifted the value of gold inventory by Rs 536 crore, of which Rs 490 crore was in standalone jewellery and Rs 46 crore in CaratLane (490 plus 46 is 536, my calculation). It is an operating gain, so Kotak Neo keeps it in Rs 1,722 crore, but it comes from a one-time rise in the gold price rather than from sales. Q1 FY27 also held a Rs 407 crore customs gain, so the Titan Q2 results FY27 are the second quarter in a row with this effect.
Which number should you compare?
For the Titan Q2 results FY27 trend, use core profit near Rs 1,320 crore, up about 18%. For what the company reported, use Rs 2,393 crore and say it includes Rs 671 crore of revaluation. For the profit that includes operating gains but not the Damas item, use Rs 1,722 crore. Mixing them is the most common error in headlines, and a headline of “profit more than doubles” and one of “profit up 18%” are both describing the same quarter.
Titan Q2 results FY27 revenue: why four reports show four numbers
Titan’s revenue appears as Rs 20,610 crore (+10%), Rs 20,614 crore (+10.1%), Rs 20,337 crore (+23.5%), Rs 20,533 crore (+25%) and Rs 17,830 crore, because the reports mix bullion, total income and different year-ago bases, and I could not open the filing to settle it.
| Report | Revenue figure | Growth | Likely basis |
|---|---|---|---|
| Business Standard, 6 Nov | Rs 20,610 crore | +10%; +23% ex-bullion | Revenue from operations incl. bullion |
| Indian Opinion, 6 Nov | Rs 20,614 crore | +10.1% | Same basis |
| Moneycontrol via TradingView, 6 Nov | Rs 20,337 crore revenue from operations; Rs 21,430 crore total income | +23.54%; +13.7% | A different basis; not reconciled in the report |
| Kotak Neo, 6 Nov | Rs 20,533 crore total income | +25% | Excludes bullion and digital-gold sales |
| Business Today, 5 Nov | Rs 17,830 crore (also total income Rs 20,533 crore) | About +8% on Rs 16,534 crore | Not reconciled in the article |
Cite this table: PositionalCalls, “Titan Q2 FY27 Revenue Conflict Table, as of 7 November 2026”.
I can tie two of these. Rs 20,614 crore over a year-ago base of Rs 18,725 crore (Motilal Oswal’s base) is 1.101, so the +10.1% matches (my calculation). Over the Rs 18,837 crore base in my preview post the same figure is +9.4%, so the year-ago bases differ and I cannot say which is restated. The Rs 20,337 crore and Rs 17,830 crore lines tie to neither.
For the Titan Q2 results FY27 I use Rs 20,610 crore (+10%) as revenue from operations and Rs 17,495 crore (+24%) as jewellery excluding bullion, because both state their basis and the jewellery line ties to its parts and to last year’s Rs 14,092 crore (17,495 over 14,092 is +24.1%, my calculation). The gap between +10% and +24% is the bullion effect.
Titan jewellery Q2 FY27: Rs 17,495 crore revenue and the margin question
Jewellery revenue ex-bullion was Rs 17,495 crore, up 24%, with India up 21% and international up 105%; the EBIT margin was 13.1% with the customs gain, and about 10.7% to 10.9% without it.
| Jewellery measure | Q2 FY27 | Source and basis |
|---|---|---|
| Revenue ex-bullion | Rs 17,495 crore, +24% | Kotak Neo; Business Today |
| India jewellery | Rs 16,343 crore, +21% | Kotak Neo; Moneycontrol |
| International jewellery | Rs 1,152 crore, +105% | Includes Damas core revenue of Rs 364 crore (Kotak Neo) |
| Segment EBIT with customs gain | Rs 2,300 crore, 13.1% | Kotak Neo; 2,300 over 17,495 is 13.1% |
| India jewellery EBIT without customs gain | Rs 1,745 crore, 10.7% | Kotak Neo; 1,745 over 16,343 is 10.7% |
| Standalone jewellery EBIT without Rs 490 crore gain | Rs 1,690 crore, 10.9%, flat | Business Standard; on like-for-like sales of Rs 15,550 crore |
| Segment EBIT less the full Rs 536 crore (my calculation) | Rs 1,764 crore, 10.1% | Mixes bases; shown for scale only |
| Citi view of the margin | About 11.7%, +60 bps | Moneycontrol; basis not stated |
| FY27 margin guidance | About 11% | Business Standard; Jefferies cites the same level |
Cite this table: PositionalCalls, “Titan Jewellery Q2 FY27 Table, as of 7 November 2026”.
The parts tie: Rs 16,343 crore for India plus Rs 1,152 crore for international is Rs 17,495 crore (my calculation). India growth came from spend per buyer: domestic like-for-like growth was 15%, buyer numbers were flat and the average ticket rose (Business Standard).
The margin figures use different bases: Kotak Neo’s 10.7% is India jewellery only, Business Standard’s 10.9% is standalone on like-for-like sales, and my 10.1% mixes bases and includes Damas and CaratLane. All sit near the 11% guidance. The Titan Q2 results FY27 therefore show jewellery growing well at a steady margin once the gold-duty gain is removed.
PositionalCalls WhatsApp channel
Titan results, explained on WhatsApp
- The profit basis and one-offs stated for each result
- Conflicts between sources shown, not hidden
- The next company on the results calendar
Watches, EyeCare, CaratLane and other businesses in the Titan Q2 results
Watches grew 27% to Rs 1,881 crore with a 21.9% EBIT margin, EyeCare grew 28% to Rs 281 crore with an 8.2% margin, CaratLane grew 31% with a lower 6.5% adjusted margin, and the emerging businesses lost Rs 6 crore.
| Business | Q2 FY27 revenue | Growth | EBIT and margin | Source |
|---|---|---|---|---|
| Watches and wearables | Rs 1,881 crore | +27% | Rs 412 crore, 21.9% (+580 bps) | Kotak Neo; Business Standard |
| EyeCare | Rs 281 crore | +28% | Rs 23 crore, 8.2% (+270 bps) | Kotak Neo; Business Standard |
| CaratLane | Not stated | +31% | 6.5% adjusted for a Rs 46 crore gain (-360 bps) | Business Standard |
| Emerging (SKINN, IRTH, Taneira) | Rs 171 crore | +21% | Combined loss of Rs 6 crore | Kotak Neo |
| Titan Engineering and Automation | Rs 36 crore | +53% | Not stated | Kotak Neo |
Cite this table: PositionalCalls, “Titan Other Businesses Q2 FY27 Table, as of 7 November 2026”.
Watches are the quiet strength of the quarter. Rs 412 crore of EBIT on Rs 1,881 crore of revenue is a 21.9% margin (my calculation), which ties to the reported figure, and Business Standard puts watch EBIT growth at 73%. EyeCare’s margin check also ties: Rs 23 crore over Rs 281 crore is 8.2%. CaratLane’s margin fell 360 bps even after removing its inventory gain, a reminder that its growth costs more to produce than Titan’s core jewellery.
Net store additions in jewellery were 43 (Tanishq 8, CaratLane 13, BeYon 4 and Mia 18, which adds to 43), and watches added 34 net stores in India. The 7 October update gave 78 net additions in total, which I could not reconcile to the filing’s store lines, so I do not repeat that count as final.
Titan Q2 results FY27 versus estimates: what the Street expected
Moneycontrol put the LSEG consensus at Rs 1,473 crore, so the Rs 1,722 crore figure was 16.9% above it and core profit of about Rs 1,320 crore was 10.4% below it (my calculation), but the reports do not say whether the estimates included the customs gain.
| Source | Profit estimate | Revenue estimate | EBITDA estimate | Against the reported figure (my calculation) |
|---|---|---|---|---|
| LSEG consensus (Moneycontrol) | Rs 1,473 crore | Not stated | Not stated | Rs 2,393 crore is +62.5%; Rs 1,722 crore is +16.9%; core Rs 1,320 crore is -10.4% |
| Citi (TradingView) | Rs 1,274.4 crore (+27%) | Rs 18,444.6 crore | Rs 1,990.9 crore; margin 10.8% | Core Rs 1,320 crore is +3.6% |
| Motilal Oswal (TradingView) | Rs 1,419.2 crore adjusted (+26.8%) | Rs 22,243.8 crore | Rs 2,324.7 crore; margin 10.5% | Rs 1,722 crore is +21.3%; core is -7.0% |
Cite this table: PositionalCalls, “Titan Q2 FY27 Estimate Table, as of 7 November 2026”.
Which comparison is fair depends on what each estimate left out. Motilal Oswal’s figure is described as adjusted, and its revenue estimate of Rs 22,244 crore is close to a growth rate near 19%, so it appears to be on a bullion-excluded basis. Citi’s revenue estimate of Rs 18,445 crore is much lower, which suggests a different revenue base, and neither source says how it treated the gold-duty gain. The honest reading is that the reported Rs 1,722 crore beat the estimates on any basis that includes the customs gain, and the core Rs 1,320 crore sat between Citi and Motilal Oswal.
EBITDA is a second place where bases split. Business Standard gives EBITDA of Rs 2,450 crore, up 31%, adjusted for the Rs 536 crore inventory gain. That growth rate implies a year-ago base near Rs 1,870 crore, which matches Motilal Oswal’s Rs 1,875 crore but not the Rs 1,987 crore in my preview table (Rs 2,450 crore over Rs 1,987 crore would be +23%, my calculation). I treat Rs 1,987 crore as a different EBITDA definition, not an error, and the filing should confirm it.
Titan Q2 results FY27 against the preview marks
Against the marks set in the 30 October preview, profit was stronger on the Rs 1,722 crore view, weaker on the core view, revenue was weaker on the headline line, and jewellery growth and margin were in line.
| Preview mark | What the preview said | What was reported | Reading |
|---|---|---|---|
| Profit base | Q2 FY26 profit Rs 1,120 crore | Rs 2,393 crore reported; Rs 1,722 crore (+54%); core Rs 1,320 crore (+18%) | Depends on the basis |
| Profit guide | Above Rs 1,648 crore stronger; Rs 1,401 to 1,648 crore in line; below Rs 1,401 crore weaker | Rs 1,722 crore is above 1,648; Rs 1,320 crore is below 1,401 | Stronger or weaker by basis |
| Revenue guide | Above Rs 23,546 crore stronger; below Rs 22,604 crore weaker | Rs 20,610 crore (+10%) incl. bullion; Rs 20,533 crore total income ex-bullion | Weaker on that line; bullion effect |
| Jewellery growth | 21% in the 6 October update (domestic) | India jewellery +21%; total +24% with international +105% | Matches the update |
| Jewellery EBIT margin | 11.6% or higher stronger; 10.6% to 11.5% in line | 10.7% to 10.9% without the customs gain; 13.1% with it | In line |
| Watches and EyeCare | +30% and +28% in the update | +27% and +28% | Watches slightly lower |
| One-off items | Rs 407 crore customs gain in Q1 | Rs 536 crore customs gain and Rs 671 crore Damas gain in Q2 | Two one-offs |
| Profit estimate | None found | LSEG consensus Rs 1,473 crore; Citi Rs 1,274 crore; Motilal Oswal Rs 1,419 crore | Now available |
Cite this table: PositionalCalls, “Titan Q2 FY27 Preview-to-Result Table, as of 7 November 2026”.
The preview’s cut-offs were built before any profit estimate existed, so they came from last year’s margin, and the table uses them as written. Two marks held: the 21% jewellery growth in the 7 October update was the India figure, and the filing shows India jewellery up 21% (Kotak Neo); and the margin sat at 10.7% to 10.9% against the preview’s 11.6% clean Q1 level.
The revenue mark is where the preview looks too high, and the reason is bullion. Revenue from operations rose about 10% because bullion and digital-gold sales fell, while jewellery excluding bullion rose 24% and total income excluding bullion rose 25% (Business Standard; Kotak Neo). Comparing only the headline line would call the quarter weak; comparing jewellery would call it strong.
Titan brokerage targets after the Q2 results, as reported
As reported on 6 November, Nomura has Buy with a Rs 6,150 target, Jefferies upgraded to Buy at Rs 6,000, Citi Buy at Rs 5,875, JPMorgan Neutral at Rs 5,540, Nuvama Hold at Rs 5,479 and PL Capital Accumulate at Rs 5,330, and Business Standard cites a Bloomberg average of Rs 5,465.
| Brokerage | Rating (as reported) | Target (Rs) | Gap to Rs 4,994 (my calculation) | Source |
|---|---|---|---|---|
| Nomura | Buy | 6,150 (raised) | +23.1% | Indian Opinion |
| Jefferies | Buy (upgraded) | 6,000 | +20.1% | Moneycontrol; Indian Opinion |
| Citi | Buy (maintained) | 5,875 | +17.6% | Moneycontrol |
| JPMorgan | Neutral (maintained) | 5,540 | +10.9% | Moneycontrol; Indian Opinion |
| Nuvama | Hold | 5,479 (raised) | +9.7% | Indian Opinion |
| PL Capital | Accumulate | 5,330 (revised) | +6.7% | Indian Opinion |
| UBS | Buy | Not stated | Not available | Indian Opinion |
| Bloomberg poll | 24 of 27 analysts bullish | 5,465 average, one-year | +9.4% | Business Standard |
Cite this table: PositionalCalls, “Titan Brokerage Views After Q2 FY27, as of 7 November 2026”.
After the Titan Q2 results FY27, these are brokerages’ own 12-month views, dated 6 November 2026 as reported, and they are not PositionalCalls targets or advice. The gap column is simple arithmetic from the Rs 4,994 level reported by Business Standard, and it is not a forecast of where the stock will go. The houses split on rating (Buy, Accumulate, Hold and Neutral), and Indian Opinion’s headline calls the views “split on target prices”. Targets move after results, so check the date on any figure you see quoted elsewhere.
Titan closed at Rs 4,831.55 on Thursday, 5 November, up 1.72% before the results came out, and rose about 3.4% to Rs 4,994 on Friday, 6 November, with an intraday high near Rs 5,002 to Rs 5,004 and an intraday low of Rs 4,694.40.
| Item | Level | Source and note |
|---|---|---|
| Thursday, 5 Nov close | Rs 4,831.55 (+1.72%) on a Rs 4,750 prior close | Business Today; Moneycontrol (BSE) |
| Market value at that close | About Rs 4.28 lakh crore | Business Today |
| Friday, 6 Nov open | Rs 4,799.90 | Kotak Neo (NSE) |
| Friday intraday range | Rs 4,694.40 low; Rs 5,003.90 high (NSE) or Rs 5,001.90 (BSE) | Kotak Neo; Moneycontrol |
| Friday level | About Rs 4,994, +3.4% | Business Standard |
| Two-day change from Rs 4,750 to Rs 4,994 | +5.1% | My calculation |
Cite this table: PositionalCalls, “Titan Share Price Around the Q2 Results, as of 7 November 2026”.
Around the Titan Q2 results FY27 the price figures have small conflicts. Kotak Neo lists a previous close of Rs 4,834.60 where Business Today and Moneycontrol give Rs 4,831.55, which is probably an exchange difference. On Kotak Neo’s base the 10:54 AM price of Rs 4,983.60 is +3.08% (4,983.60 over 4,834.60, my calculation), and on Business Standard’s Rs 4,831.55 base Rs 4,994 is +3.4%, so both tie to their own bases. Moneycontrol’s article says the stock rallied 4.2% to its high, but Rs 5,001.90 is about 3.5% above its prior close, so I do not use the 4.2% figure. I did not find an official NSE close for 6 November.
What Titan management said after the Q2 results
Management said it will put growth and customer acquisition ahead of margin expansion, that festive demand moved from Q2 FY26 into Q3 FY27, and that footfalls improved at the end of October, according to Business Standard.
- Margin stance: Titan “will prioritise growth and customer acquisition over margin expansion”, and the FY27 jewellery margin guidance stays near 11% (Business Standard).
- Festive timing: the festive season fell in Q3 FY27 this year against Q2 in FY26, which affects both quarters’ comparisons (Business Standard).
- Mark-to-market: gains and losses are expected at 40 to 60 bps of margin sequentially (Business Standard).
- Fundraise: the board approved raising up to Rs 2,500 crore through privately placed, unsecured, redeemable non-convertible debentures, mainly to refinance borrowings (Business Today; Business Standard).
- New product: Business Today notes the launch of Vetra, an in-house watch movement.
The festive shift matters for how the Titan Q2 results FY27 compare with the next quarter. If festive buying that fell in Q2 last year lands in Q3 this year, Q3 FY27 growth will look higher and the Q2 comparison was a harder base. The company’s own commentary says so, but it gave no quantified Q3 forecast in the sources I opened. For the earlier festive-quarter pattern, see my older Titan Q3 results analysis, which covers a different quarter and is not a forecast.
No dividend is mentioned in the reports I read for this quarter. The debenture approval is a borrowing plan and not a payout. Confirm any corporate action on the exchange announcement page.
What ties and what does not in the Titan Q2 results FY27
Seven checks tie within rounding, and four do not: revenue, the year-ago EBITDA base, jewellery margin bases and the profit figure in one headline.
This list is the reason the Titan Q2 results FY27 need a basis label on every figure. If you quote Titan’s profit anywhere, say which of the three you mean. The filing’s notes on exceptional items and the segment table settle most of the open points above, and they are free on the BSE and NSE announcement pages. Treat any message promising a sure-shot call on Titan as unreliable.
Risks to read with the Titan Q2 results FY27
Analyst’s note on the Titan Q2 results FY27
The quarter shows a healthy jewellery and watches business with steady margins, wrapped in two accounting and inventory gains that make the headline profit look far larger than the trend.
- What stands out: core profit growth of about 18% against jewellery growth of 24% means margins did not widen, even though the headline shows +114%.
- Easy to miss: the 21% India jewellery growth matched the 7 October update exactly, so the filing added no surprise on volume.
- What would change the view: a filing note that puts more of the Rs 536 crore customs gain in revenue or shows a different bullion figure.
- Caution: one quarter does not fix a long-term value, and brokerage targets differ by about Rs 800.
- Reader action: read the exceptional-items note and the segment table before quoting any Titan profit.
Bottom line
The Titan Q2 results FY27 show reported profit of Rs 2,393 crore, Rs 1,722 crore without the Damas gain and about Rs 1,320 crore at the core, up 18%. Jewellery grew 24% at a margin near 11% once the Rs 536 crore customs gain is removed. Brokerage targets range from Rs 5,330 to Rs 6,150 as reported, and the share price rose about 3.4% on 6 November. Read the exceptional-items note and speak to a registered adviser before acting.
Next read: the preview post for the marks set before the results.
Part of the Earnings series.
PositionalCalls WhatsApp channel
Never miss a results update
- Same-day decoders with the numbers sourced
- Corrections posted openly when a number changes
- Plain-language risk notes
Titan Q2 results FY27: frequently asked questions
What are the Titan Q2 results FY27?
Titan reported consolidated profit of Rs 2,393 crore (+113.7%) for the quarter ended 30 September 2026, including a Rs 671 crore Damas gain. Without it, profit was Rs 1,722 crore (+54%). Results came after market hours on 5 November 2026.
What is Titan’s core profit in Q2 FY27?
Business Standard puts adjusted profit, without the Damas change and the Rs 536 crore inventory gain, at about Rs 1,320 crore, up 18%. My bridge, using an assumed 25.17% tax rate, gives Rs 1,321 crore.
What is the Damas gain in Titan’s profit?
A Rs 671 crore fair-value gain from remeasuring the put-option liability to Damas’s minority owners. Kotak Neo calls it non-operational. It is in the Rs 2,393 crore reported profit and not in the Rs 1,722 crore figure.
What is the customs-duty gain in Titan’s Q2 results?
The customs duty on gold rose from 6% to 15%, lifting inventory value by Rs 536 crore before tax (Rs 490 crore in standalone jewellery and Rs 46 crore in CaratLane), per Business Standard. Q1 FY27 held a similar Rs 407 crore gain.
What was Titan’s revenue in Q2 FY27?
Reports differ: Rs 20,610 crore (+10%) for revenue from operations including bullion, Rs 20,533 crore (+25%) for total income excluding bullion, and Rs 20,337 crore (+23.5%) in another. Jewellery excluding bullion was Rs 17,495 crore (+24%).
How did Titan’s jewellery business do in Q2 FY27?
Revenue was Rs 17,495 crore, up 24%, with India up 21% and international up 105%. The EBIT margin was 13.1% with the customs gain and about 10.7% to 10.9% without it, near the 11% guidance.
Did Titan beat estimates in Q2 FY27?
Moneycontrol put the LSEG consensus at Rs 1,473 crore. The Rs 1,722 crore figure was about 17% above it and core profit about 10% below it (my calculation); the reports do not say whether estimates included the customs gain.
What are the brokerage targets for Titan after Q2?
As reported on 6 November: Nomura Rs 6,150, Jefferies Rs 6,000, Citi Rs 5,875, JPMorgan Rs 5,540, Nuvama Rs 5,479 and PL Capital Rs 5,330. These are brokerages’ views, not PositionalCalls targets or advice.
Titan closed at Rs 4,831.55 on 5 November and rose about 3.4% to Rs 4,994 on 6 November, per Business Standard. Kotak Neo shows an intraday range of Rs 4,694.40 to Rs 5,003.90.
Did Titan declare a dividend with the Q2 results?
None of the reports I opened mentions a dividend. The board approved raising up to Rs 2,500 crore through non-convertible debentures, which is a borrowing plan. Confirm any corporate action on the BSE or NSE announcement page.
Sources
- Business Today, 5 November 2026 (Titan Q2 earnings)
- Kotak Neo, 6 November 2026 (Titan Q2 FY27 results)
- Business Standard, 6 November 2026 (Street on Titan after Q2)
- Moneycontrol via TradingView, 6 November 2026 (results vs estimates, brokerages)
- Indian Opinion, 6 November 2026 (brokerage targets)
- TradingView, November 2026 (Citi and Motilal Oswal estimates)
- Kotak Neo, 7 October 2026 (Q2 business update)
- Upstox, 3 November 2025 (Q2 FY26 base)
- Angel One, August 2026 (Q1 FY27 results)
- BSE and NSE announcement pages: where the Titan filing is published (I did not open it).
Disclosure: PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent Indian stock market research and education site founded by Shubham Chaudhary. This page is results analysis and not a recommendation, target or investment advice. How I researched this: I compared five press and data-platform reports of the filing, tied the profit bridge, the half-year, the jewellery parts and the segment margins, recomputed every derived number, and listed the conflicts openly. I did not open the filing.
Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive