
Insurance · Insurance Stocks
Looking for the best insurance stocks in India 2026? This page compares five listed insurers on the metric each is judged by, using Q2 FY27 results as reported, and tracks the IRDAI distribution draft. It names no winner.
Quick answer
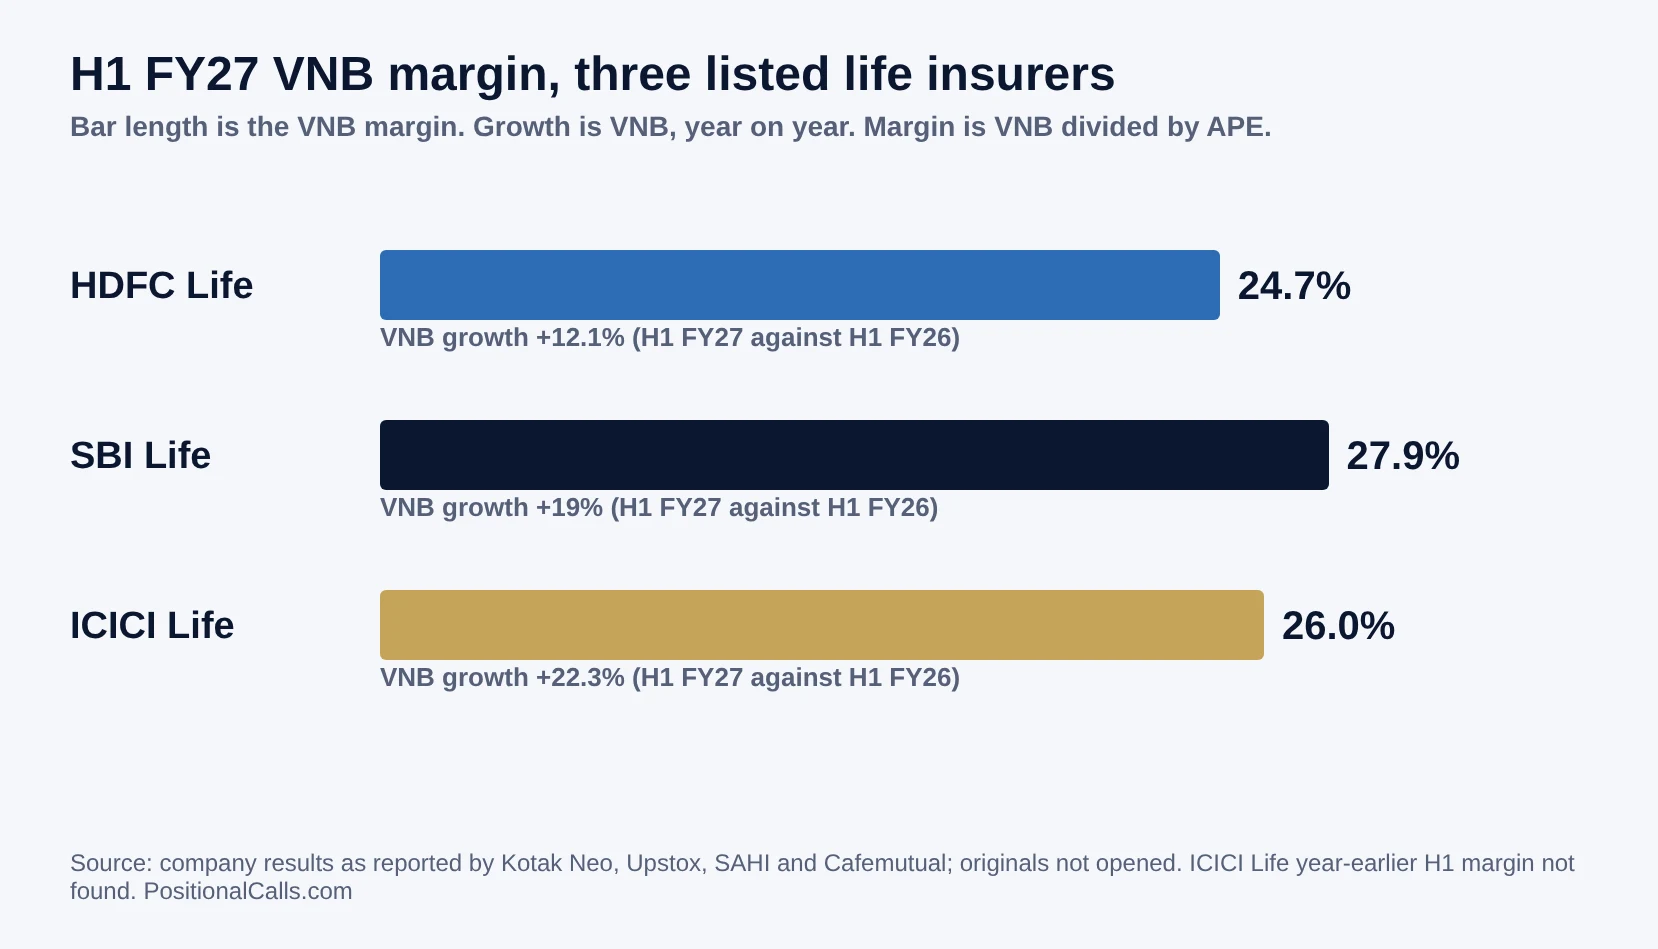
The best insurance stocks in India 2026 cannot be ranked on one number, because life insurers are read on VNB margin and general and health insurers on combined ratio. H1 FY27 VNB margins were HDFC Life 24.7%, SBI Life 27.9% and ICICI Life 26.0%; Star Health reported a 98.0% ratio.
Latest update (Sunday, 15 November 2026, 8:33 AM IST): Rebuilt on Q2 FY27 results for all five insurers and on IRDAI’s extension of its feedback deadline to 31 October. One earlier figure is corrected: HDFC Life’s embedded value, which the sources I opened put at Rs 66,461 crore. HDFC Life’s 24.5% Q2 margin from the earlier version is restored, because PL Capital reports it, up 39 basis points a year on year. ICICI Prudential Life is reported as ICICI Life Insurance, formerly ICICI Prudential Life.
Key takeaways
- No ranking: this page compares five insurers on stated criteria. It gives no rating, target or buy list.
- Life insurers: H1 FY27 VNB margins were HDFC Life 24.7%, SBI Life 27.9% and ICICI Life 26.0%, with VNB growth of 12.1%, about 19% and 22.3%.
- General and health: ICICI Lombard’s Q2 combined ratio was 107.0% as the headline figure; Star Health reported a 98.0% combined insurance service ratio and an underwriting profit of Rs 99 crore.
- IRDAI: the distribution draft is not final. Feedback closed on 31 October after more than 650 responses, and a Bloomberg-based report says another consultation is expected before final rules.
- Gaps: no live prices, no price-to-embedded-value data, no flow data, and no exchange filing opened in this rebuild.
In plain words: VNB margin shows how profitable newly sold life policies are expected to be. Combined ratio shows claims plus expenses as a share of premium; above 100% means an underwriting loss before investment income. The two cannot be compared with each other.
Data note: Life insurer and Star Health figures are from news and results summaries of company releases: Kotak Neo, Upstox, SAHI, Free Press Journal, Cafemutual, Compounding AI and UNI. ICICI Lombard figures and SBI Life’s Q1 inputs are carried from the 26 October version of this page, which cited an NSE filing for ICICI Lombard; its profit is cross-checked to SAHI. I opened no exchange filing in this rebuild, so confirm each figure against the company filing.
1. What are the best insurance stocks in India 2026?
There is no single list of the best insurance stocks in India 2026 that one number can produce. These five are the large listed insurers most readers track, and each is read on a different scorecard, so this page compares and does not rank.
HDFC Life, SBI Life and ICICI Life are life insurers. ICICI Lombard is a general insurer and Star Health is a health insurer. ICICI Life is the company formerly named ICICI Prudential Life; the Free Press Journal reports the new name and gives no date for the change. All five have reported Q2 FY27 (July to September 2026), but life insurers published half-year figures and some quarter-only numbers are missing, so the periods below differ.
| Insurer | Type | Period | Key figures | What it tells you |
|---|---|---|---|---|
| HDFC Life | Life | H1 FY27 (Apr-Sep 2026); Q2 reported 15 Oct | VNB Rs 2,037 crore (+12.1%); VNB margin 24.7% (24.5% a year earlier); APE Rs 8,245 crore (+11%); embedded value Rs 66,461 crore | Margin edged up; growth is the slowest of the three life insurers |
| SBI Life | Life | H1 FY27; reported by 27 Oct | VNB Rs 3,270 crore (+19%); VNB margin 27.9%; APE Rs 11,750 crore (+18%); solvency 1.97 | Highest margin of the three, with costs rising |
| ICICI Life | Life | Q2 FY27 and H1 FY27; board approval 13 Oct | Q2 VNB Rs 712 crore (+20.7%), margin 25.43%; H1 VNB Rs 1,283 crore (+22.3%), margin 26.0%; solvency 229.9% | Fastest VNB growth; Q2 margin missed some analyst estimates |
| ICICI Lombard | General | Q2 FY27; filed 14 Oct | Combined ratio 107.0% (headline); profit after tax Rs 946 crore (+15.5%); premium growth 3.0% against industry 7.0% | Underwriting loss before investment income |
| Star Health | Health | Q2 FY27; announced 29 Oct | Combined insurance service ratio 98.0% (100.9% a year earlier); underwriting profit Rs 99 crore; reported profit Rs 265 crore; GWP Rs 5,275 crore (+19%) | Underwriting profit for a fifth quarter, but reported profit fell from Q1 |
Cite this table: Company results as reported by Kotak Neo, Upstox, SAHI, Free Press Journal, UNI and the 26 October version of this page; originals not opened; periods and metrics differ by row.
Rows are not like for like. A life insurer’s VNB margin and a general insurer’s combined ratio measure different things, and the ICICI Lombard ratio differs by accounting basis, so the row shows the headline figure. The next sections set out each company’s numbers with the source and the caveat.
2. What changed in the best insurance stocks in India 2026 page since 26 October?
This rebuild replaces first-quarter figures with half-year or Q2 figures for the life insurers, adds Star Health’s Q2 result and the IRDAI deadline extension, and corrects two HDFC Life numbers that the sources I opened do not support.
What the best insurance stocks in India 2026 page corrected and dropped
| Item | 26 October version | This rebuild | Why |
|---|---|---|---|
| HDFC Life VNB margin | 24.5% for Q2 FY27 | 24.5% for Q2 FY27 (restored); 24.7% for H1 FY27 | PL Capital reports a Q2 margin of 24.5%, up 39 basis points; Kotak Neo gives H1 24.7%, up from 24.5% a year earlier. The Q2 figure rests on one brokerage note and I did not open the filing |
| HDFC Life embedded value | Rs 65,860 crore | Rs 66,461 crore | Kotak Neo and Cafemutual both give Rs 66,461 crore |
| HDFC Life solvency | 180% | Not shown | Neither source I opened gives a solvency ratio |
| SBI Life | Q1 FY27 margin 26.2% | H1 FY27 margin 27.9%; Q2-only figures derived | Half-year results are out |
| ICICI Prudential Life | Q1 FY27 margin 26.7% | Q2 margin 25.43%; H1 26.0% | Q2 results are out; company reported as ICICI Life Insurance |
| Star Health | Q1 FY27 ratio 97.7% | Q2 FY27 ratio 98.0% | Q2 results announced 29 October |
| IRDAI deadline | 25 October, no extension confirmed | Extended to 31 October | Reported 26 October with more than 650 responses |
| GST, penetration and a premium-fall claim | Included from a broker note and a presentation | Dropped | I could not re-check them; they are not carried over |
Cite this table: Comparison of the 26 October PositionalCalls version with sources opened in this rebuild; originals not opened.
The pattern is that the earlier page leaned on two single numbers that the later sources do not repeat. I removed those and kept only figures that at least one source I opened states, labelling anything I derived as my calculation.
3. Life insurers: HDFC Life, SBI Life and ICICI Life
On H1 FY27 numbers the three life insurers sit in a 24.7% to 27.9% VNB margin band. ICICI Life grew VNB fastest at 22.3%, SBI Life earned the highest margin, and HDFC Life grew the slowest, so the best insurance stocks in India 2026 question depends on whether you weigh margin or growth.
| H1 FY27 (Apr-Sep 2026) | HDFC Life | SBI Life | ICICI Life |
|---|---|---|---|
| VNB | Rs 2,037 crore (+12.1%) | Rs 3,270 crore (+19%) | Rs 1,283 crore (+22.3%) |
| APE | Rs 8,245 crore (+11%) | Rs 11,750 crore (+18%) | Rs 4,935 crore (+15.1%) |
| VNB margin | 24.7% (24.5% a year earlier) | 27.9% (27.8% a year earlier) | 26.0% |
| Profit after tax | Rs 1,119 crore (+12.7%) | Rs 1,270 crore (+17%) | Rs 760 crore (+26.5%) |
| Embedded value | Rs 66,461 crore | Rs 87,350 crore | Not found |
| Solvency | Not found | 1.97 (1.94 a year earlier) | 229.9% (213.2% a year earlier) |
| Check: VNB divided by APE (my calculation) | 24.7% | 27.8% | 26.0% |
Cite this table: H1 data as reported by Kotak Neo, Cafemutual, Compounding AI, Upstox, SAHI and Free Press Journal; originals not opened. The last row is my division of the reported VNB by APE.
The check row matters. Dividing reported VNB by APE gives 24.7% for HDFC Life, 27.8% for SBI Life and 26.0% for ICICI Life, which agree with the reported margins within rounding. That gives me confidence in the three margins even though I did not open the filings.
HDFC Life
- Growth picked up: Q2 VNB rose 14.8% and Q2 APE rose 13%, against 9% APE growth in Q1.
- Return: the rolling 12-month operating return on embedded value was 14.9%.
- Cost and persistency: the H1 expense ratio rose to 22.3% from 21.6%, and 13th-month persistency fell to 83% from 86%, while 61st-month persistency rose to 66% from 62%.
- Scale: assets under management were Rs 4.10 lakh crore, up 14%.
HDFC Life is the slowest grower of the three on VNB, and its higher expense ratio and lower 13th-month persistency are the two numbers a reader would want to see recover. PL Capital puts the Q2-only margin at 24.5%, up 39 basis points a year on year (single source, filing not opened); neither source I opened gave a solvency ratio.
SBI Life
- Margin: 27.9% for H1 FY27 against 27.8% a year earlier. Q1 was 26.2% on figures carried from the earlier page (VNB Rs 1,410 crore on APE Rs 5,380 crore).
- Costs: the operating expense ratio rose to 6.9% from 6.2% and the total cost ratio to 11.7% from 10.9%.
- Persistency: 13th-month persistency was 85.82% and 61st-month persistency 58.01%.
- Return: return on equity was 12.9%, up from 12.3%.
Subtracting Q1 from H1 implies a Q2 VNB of about Rs 1,860 crore on APE of about Rs 6,370 crore, a margin near 29.2% (my calculation). That chain mixes sources and rounded inputs, so treat it as indicative. It also implies Q2 APE growth well below Q1’s 36%, which the half-year APE growth of 18% supports. Management guidance for FY27 margin was 26% to 28%, per the earlier version of this page; H1 sits at the top of that range. Compounding AI reported that SBI Life did not disclose a margin in the filing summary it used, while Kotak Neo gave 27.9%, and my division gives 27.8%.
ICICI Life Insurance
- Q2: VNB Rs 712 crore (+20.7%), APE Rs 2,799 crore (+16.6%), margin 25.43%, profit Rs 374.22 crore (+24.8%).
- Versus estimates: Nomura said the 25.4% margin missed its 26.7% estimate, while SAHI put the street estimate at 25.79%; the reports differ.
- Mix: Bernstein and Goldman Sachs credited product mix, with protection, annuities and the partnership channel; Jefferies said a higher group funds mix held the margin below expectations and cut its FY27 to FY29 VNB estimates by 2%.
- Margin change: one report puts the year-earlier margin at 24%; JP Morgan said the margin rose about 100 bps. I could not reconcile the two.
Q2 VNB of Rs 712 crore plus Q1’s Rs 571 crore from the earlier page equals the reported H1 figure of Rs 1,283 crore, a useful consistency check (my calculation). The Q2 margin of 25.43% is below Q1’s 26.7%, so the half-year 26.0% hides a sequential fall.
4. General and health insurers: ICICI Lombard and Star Health
ICICI Lombard and Star Health are read on combined ratio. ICICI Lombard reported 107.0% as the headline figure, an underwriting loss, while Star Health reported a combined insurance service ratio of 98.0% and an underwriting profit of Rs 99 crore, but its reported profit fell from Q1.
| Item | ICICI Lombard Q2 FY27 | Star Health Q2 FY27 |
|---|---|---|
| Underwriting ratio | Combined ratio 107.0% (headline); 104.5% (other basis) | Combined insurance service ratio 98.0% (100.9% a year earlier) |
| Profit after tax | Rs 946 crore (+15.5%); Rs 1,031 crore on the other basis | Reported Rs 265 crore (+233%); normalised Rs 390 crore (+70%) |
| Premium growth | GDPI +3.0% against industry +7.0% | Gross written premium Rs 5,275 crore (+19%, 1/N) |
| Underwriting result | Loss before investment income | Profit Rs 99 crore, against a loss of Rs 40 crore a year earlier |
| Capital | Solvency 2.75x (minimum 1.50x) | Not found |
| Claims signal | Health loss ratio 85.3% against 77.3% a year earlier | Q2 claims ratio not found |
Cite this table: ICICI Lombard figures carried from the 26 October version, which cited the 14 October NSE filing; its Rs 946 crore profit and Rs 820 crore year-earlier figure also appear in SAHI. Star Health per UNI/PR Newswire, 29 October 2026; originals not opened.
The two bases for ICICI Lombard differ by 2.5 percentage points (107.0% minus 104.5%, my calculation), and the sources I opened do not say which accounting basis each pair uses, so I have not labelled them. This page uses the 107.0% headline figure.
PositionalCalls WhatsApp channel
Follow insurer results plainly
- Quarterly insurer results in plain words
- Explainers on VNB and combined ratio
- A message when this page is updated
Star Health’s reported profit of Rs 265 crore is about 52% below Q1’s Rs 550 crore (my calculation), while the combined ratio was 97.7% in Q1 on the earlier basis and 98.0% in Q2 on the new one. The two ratios are not on identical bases, and I found no source explaining the profit gap. The company’s normalised profit of Rs 390 crore uses an assumed 8% investment yield, so it is a company measure and not an accounting profit.
5. The IRDAI distribution reset and the best insurance stocks in India 2026
IRDAI’s 23 September 2026 consultation paper, “Recalibrating Economics of Insurance Distribution”, is still a draft. Feedback closed on 31 October after an extension, and final rules had not appeared in my searches as of 15 November 2026.
| Date | Event | Status |
|---|---|---|
| 23 Sep 2026 | IRDAI consultation paper proposes lower expense limits and new commission rules | Draft |
| 24 Sep 2026 | Listed insurer and distributor shares fall; PB Fintech reported down 36% in a day | Reported |
| 9 Oct 2026 | Inc42, citing Bloomberg, reports IRDAI is considering 1 January or 1 April 2027 for commission caps | Under consideration |
| 25 Oct 2026 | Original feedback deadline | Passed |
| 31 Oct 2026 | Extended deadline; more than 650 submissions reported on 26 October | Closed |
| Next | Inc42 reports IRDAI will review feedback and publish draft regulations for another consultation before final rules | Not yet seen |
Cite this table: Events as reported by Inc42, SAHI and YourStory headlines; IRDAI primary documents not opened; the Bloomberg interview is reported second-hand.
The draft’s main proposals, carried from the earlier page and reported rather than checked against the paper, are lower life insurer expense limits (15% of gross direct premium within two years and 12.5% within five), commission limits tied to segment, product, channel and effort, no volume-linked incentives for bank and NBFC staff, and clawback of commission for mis-selling. A separate paper reportedly proposes a five-year transition for insurer expense limits, with the first interim milestone in FY29.
The Insurance Brokers Association of India warned of a 60% to 70% revenue hit for brokers and asked for the deadline to move to the end of December, per Inc42. HDFC Life, SBI Life and ICICI Life depend heavily on bank-partner channels, so the bank-staff incentive proposal is the item to watch; the effect on each insurer cannot be sized from public numbers I found.
6. How life, general and health insurers make money
Insurers collect premiums first, pay claims later and invest the float in between. Life, general and health insurers are judged on different metrics, which is why the best insurance stocks in India 2026 cannot be sorted on a single column.
| Term | Meaning | Where it matters |
|---|---|---|
| VNB | Value of new business written in a period | Life insurers |
| APE | Annualised premium equivalent, the standard measure of new life business | Life insurers |
| VNB margin | VNB divided by APE | Life insurers |
| Embedded value | Value of the in-force book plus net assets | Life insurers; used with price for valuation |
| Persistency | Share of policies still paying after 13 or 61 months | Life insurers; signals quality of sales |
| Combined ratio | Claims plus expenses as a share of premium | General and health insurers |
| Solvency ratio | Available capital against the regulatory minimum (1.50x) | All insurers |
Cite this table: Definitions by PositionalCalls; no source needed beyond the company disclosures.
| Worked check (my calculation) | Arithmetic | Result |
|---|---|---|
| HDFC Life H1 FY27 margin | Rs 2,037 crore divided by Rs 8,245 crore | 24.7%, matches the reported margin |
| SBI Life H1 FY27 margin | Rs 3,270 crore divided by Rs 11,750 crore | 27.8%, against 27.9% reported |
| ICICI Life Q2 FY27 margin | Rs 712 crore divided by Rs 2,799 crore | 25.4%, matches the reported 25.43% |
| ICICI Life H1 FY27 margin | Rs 1,283 crore divided by Rs 4,935 crore | 26.0%, matches the reported margin |
| ICICI Lombard accounting gap | 107.0% minus 104.5% | 2.5 percentage points |
Cite this table: Division of reported figures by PositionalCalls; inputs as reported by the sources named above.
The worked checks are not a verification of the filings, only evidence that the reported numbers are internally consistent. Where a margin could not be divided, such as HDFC Life’s Q2, I did not state one.
7. How to compare the best insurance stocks in India 2026 on the same criteria
Use the same checks for every insurer, and read each from the company filing for the same period. The table below shows which check applies to which type of insurer, and where the evidence on this page is thin.
- Same period: compare quarter with quarter or half-year with half-year, and note the as-of date.
- Right metric: VNB margin and APE growth for life; combined ratio, premium growth against the industry and claims for general and health.
- Stated basis: n or 1/n for ICICI Lombard; normalised or reported profit for Star Health.
- Capital: solvency ratio against the regulatory minimum.
- Regulatory exposure: bank-channel dependence and product mix.
- Valuation inputs: a live price from NSE or BSE and the company embedded value disclosure; this page gives no valuation verdict.
| Factor | Life insurer | General insurer | Health insurer |
|---|---|---|---|
| Main profit metric | VNB margin | Combined ratio | Combined ratio |
| Policy term | Long term | Mostly one year | Mostly one year, renewable |
| Common swing factor | Product mix, persistency, rules | Catastrophe, motor and health claims | Claims inflation, retail mix |
| Evidence on this page | H1 FY27 for three insurers | One quarter, headline ratio | One quarter, normalised and reported profit |
| Missing here | Q2-only margin for one, valuation | Industry share, valuation | Claims ratio, valuation |
Cite this table: Framework by PositionalCalls; evidence column reflects the sources opened in this rebuild.
If you want valuation, the usual life insurer check is price to embedded value, and for general and health insurers price to earnings alongside the combined ratio. I did not collect live prices for this rebuild, so the page offers no multiple and no view on whether any of these stocks is cheap or expensive.
8. What are the risks and common mistakes with the best insurance stocks in India 2026?
The main risks are draft IRDAI rules, rising costs and weaker persistency, claims and accounting swings at general and health insurers, and a product mix that can shift margins either way within a quarter.
Common mistakes:
- Quoting a margin without its period, such as setting a Q2 margin beside an H1 one.
- Comparing a life insurer’s VNB margin with a general insurer’s combined ratio.
- Ignoring the accounting basis behind a ratio.
- Treating normalised profit as reported profit.
- Reading a draft regulation as a final rule.
9. How to invest in insurance stocks in India: what you need and what it costs
You need a demat and trading account with a SEBI-registered broker. Charges and tax depend on your broker and current rules, and shares of an insurer are different from an insurance policy.
- What you need: PAN, bank account and completed KYC.
- What it costs: brokerage, demat and transaction charges vary; check your broker’s current schedule.
- Tax angle: see capital gains tax on shares, and check current rules or ask a tax adviser.
- Not a policy: for cover, see term insurance plans, health insurance plans and super top-up health insurance.
- NRIs: holding rules are explained in NRI investment in the Indian stock market.
- Scam warning: fake allotment or KYC pages and OTP requests are common; never share an OTP.
PositionalCalls is not SEBI registered, so nothing here is a recommendation to buy or sell. Read the results filing first and check any listed company on NSE or BSE.
10. What to watch next for the best insurance stocks in India 2026
Five items would change this picture: the IRDAI draft regulations and any second consultation, Q3 FY27 results, persistency and expense ratios at the life insurers, claims at ICICI Lombard and Star Health, and valuation data once live prices are added.
| Watch item | A stronger reading | A weaker reading |
|---|---|---|
| IRDAI regulations | Final rules close to the draft limits with a long transition | Caps start on 1 January 2027 with little transition |
| Life insurer margins | H1 margins hold at or above current levels | Q3 margins fall on mix or cost |
| Persistency and expenses | 13th-month persistency recovers; expense ratios stop rising | Persistency keeps falling |
| General insurer claims | Combined ratio moves toward 100% | Loss ratios keep rising |
| Star Health profit | Reported profit recovers toward Q1’s level | Reported profit stays below normalised profit |
Cite this table: Watch list by PositionalCalls; these are conditions to check, not forecasts or probabilities.
This is a checklist, not a forecast. I assign no probability and no target to any item, and I found no confirmed Q3 FY27 result dates.
11. What most people miss, and how to check
- What stands out: the three life insurers sit in a narrow 24.7% to 27.9% margin band, so growth, costs and channel exposure may matter more than margin alone.
- Easy to miss: the accounting basis moves ICICI Lombard’s combined ratio by 2.5 points, and Star Health’s normalised profit is 47% above its reported profit (my calculation).
- What would change the picture: final IRDAI rules and Q3 FY27 results.
- Reader action: open each company’s results release on NSE or BSE and recompute the metric before relying on it.
Reasoning from the data above; not a forecast.
- Match the metric to the insurer: VNB margin for life, combined ratio for general and health.
- Match the period: a half-year margin is not a quarter margin.
- Divide the numbers yourself: VNB over APE takes a minute and catches typos.
- Check the basis: 1/n or n, normalised or reported.
- Read the regulation status: draft, second consultation or final.
For the cover side of insurance see my term insurance plans and health insurance plans guides.
Bottom line
The best insurance stocks in India 2026 cannot be ranked on one number. Life insurers held VNB margins of 24.7% to 27.9% in H1 FY27, ICICI Life grew VNB fastest, ICICI Lombard ran a 107.0% combined ratio and Star Health a 98.0% ratio. The biggest open item is IRDAI’s distribution draft. Check the same-period figures yourself.
Next read: capital gains tax on shares
Part of the Insurance series on PositionalCalls. Sector view: insurance sector outlook 2026.
PositionalCalls WhatsApp channel
Keep IRDAI changes in one place
- A dated note when IRDAI rules move
- Insurer results as they come
- Updates when new data is out
FAQs on the best insurance stocks in India 2026
What are the best insurance stocks in India 2026?
There is no single best. HDFC Life, SBI Life, ICICI Life, ICICI Lombard and Star Health are the large listed names compared here, each judged on VNB margin or combined ratio. The best insurance stocks in India 2026 depend on your criteria, so compare the company filings and not a ranking.
Which are the best life insurance stocks in India for the long term?
A long-term view depends on your goals and on data that changes every quarter. For life insurers, check VNB margin, APE growth, embedded value, persistency and solvency in each filing, and the final IRDAI rules. In H1 FY27 VNB margins were HDFC Life 24.7%, SBI Life 27.9% and ICICI Life 26.0%.
Life insurance vs general insurance stocks India: what is the difference?
Life insurers sell long-term policies and are read on VNB margin and embedded value. General and health insurers sell mostly one-year policies and are read on combined ratio, claims and premium growth. Catastrophe and claims swings matter more for general insurers, so the two groups need different scorecards.
How to invest in insurance stocks India?
Insurance stocks are bought through a demat and trading account with a SEBI-registered broker after KYC. Read the results filing first, check brokerage and tax charges with your broker, and remember these are listed company shares, not insurance policies. PositionalCalls is not SEBI registered and gives no buy or sell advice.
Who grew faster among the best insurance stocks in India 2026?
Among the life insurers covered, ICICI Life reported H1 FY27 VNB growth of 22.3%, SBI Life about 19% and HDFC Life 12.1%. SBI Life had the highest margin at 27.9%. Growth and margin are different measures, so this is a comparison of reported figures, not a ranking or a recommendation.
What is the IRDAI distribution consultation paper?
On 23 September 2026 IRDAI proposed lower expense limits and new commission rules in a paper called Recalibrating Economics of Insurance Distribution. Feedback closed on 31 October after an extension, with more than 650 responses reported. It is a draft, and I found no final regulations as of 15 November 2026.
Are insurance stocks cheap in 2026?
This page gives no valuation verdict, because valuation depends on live prices that I did not collect. Life insurers are usually checked on price to embedded value using the company disclosure, and general insurers on earnings and combined ratio. Check live prices on NSE or BSE before drawing any conclusion.
What are VNB margin and combined ratio?
VNB margin is value of new business divided by APE: HDFC Life’s H1 FY27 Rs 2,037 crore on Rs 8,245 crore gives about 24.7%. Combined ratio is claims plus expenses as a share of premium; above 100% means an underwriting loss before investment income, as with ICICI Lombard’s 107.0% in Q2 FY27.
How did Star Health and ICICI Lombard do in Q2 FY27?
ICICI Lombard reported a 107.0% combined ratio as the headline figure and profit after tax of Rs 946 crore. Star Health reported a 98.0% combined insurance service ratio, an underwriting profit of Rs 99 crore and reported profit of Rs 265 crore, against Rs 550 crore in Q1. Both bases differ, so compare with care.
Does this page say which insurance stock to buy?
No. This page names no stock to buy and gives no rating or target, so it is not a buy list of the best insurance stocks in India 2026. It reports company and regulatory data and says where data is missing, such as valuation and flows. Read the filings and consider a registered adviser before investing.
Sources
- Kotak Neo: SBI Life H1 FY27 results; 27 October 2026.
- Compounding AI: SBI Life Q2 FY27 results analysis; persistency, embedded value and solvency.
- Kotak Neo: HDFC Life H1 FY27 results; 16 October 2026.
- PL Capital: HDFC Life Q2 FY27 result update; Q2 VNB margin 24.5%.
- Cafemutual: HDFC Life July to September profit; Q2 VNB and APE growth.
- Upstox: ICICI Life Q2 FY27 VNB and analyst views; 14 October 2026.
- SAHI: ICICI Prudential Life Q2 net profit and H1 VNB; H1 figures.
- Free Press Journal: ICICI Life Insurance Q2 FY27 profit; name change, solvency and board date.
- SAHI: ICICI Lombard Q2 standalone net profit; Rs 946 crore against Rs 820 crore (headline only).
- UNI / PR Newswire: Star Health Q2 FY27; 29 October 2026.
- SAHI: IRDAI extends feedback deadline to 31 October; reported 26 October 2026.
- Inc42: IRDAI may introduce commission caps from January 2027; 9 October 2026, citing Bloomberg.
- ICICI Lombard press release and presentation, 14 October 2026 (NSE); cited in the 26 October version, not re-opened.
- Star Health Q1 FY27 earnings presentation, 29 July 2026 (NSE); Q1 figures carried from the earlier version.
- IRDAI press releases: consultation paper of 23 September 2026 (not opened).
- NSE India and BSE India for company results filings.
- Named, not linked: Khaitan & Co and Cyril Amarchand Mangaldas notes on the IRDAI paper, Moneylife and YourStory reports on the 24 September share falls, and brokerage notes quoted by Upstox. I opened none of them or any exchange filing in this rebuild.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive