
Sector Outlook · Insurance
This insurance sector outlook 2026 page tests premium growth, Q2 FY27 insurer results, the GST credit loss and the motor rulings against dated data, records where sources disagree and gives no stock picks.
Quick answer
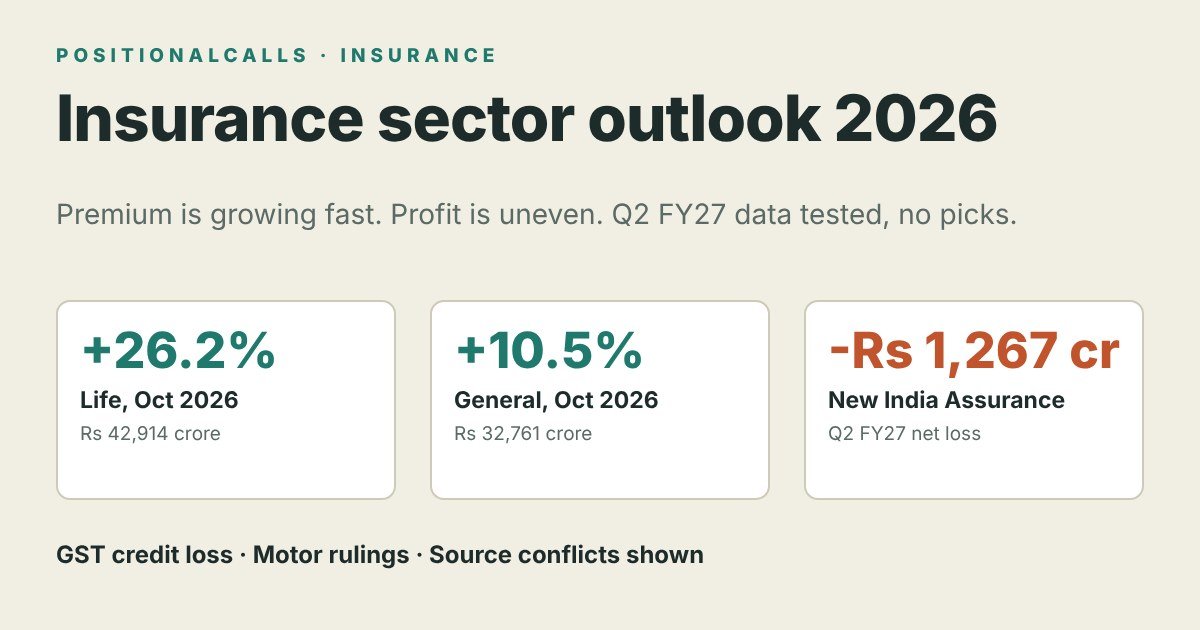
The insurance sector outlook 2026 is fast premium growth with uneven profit. Life insurers’ new business premium rose 26.2% and general insurers’ premium 10.5% in October 2026. But lost GST input credit, motor rulings and a disputed combined ratio show growth and profit are different things.
Key takeaways on the insurance sector outlook 2026
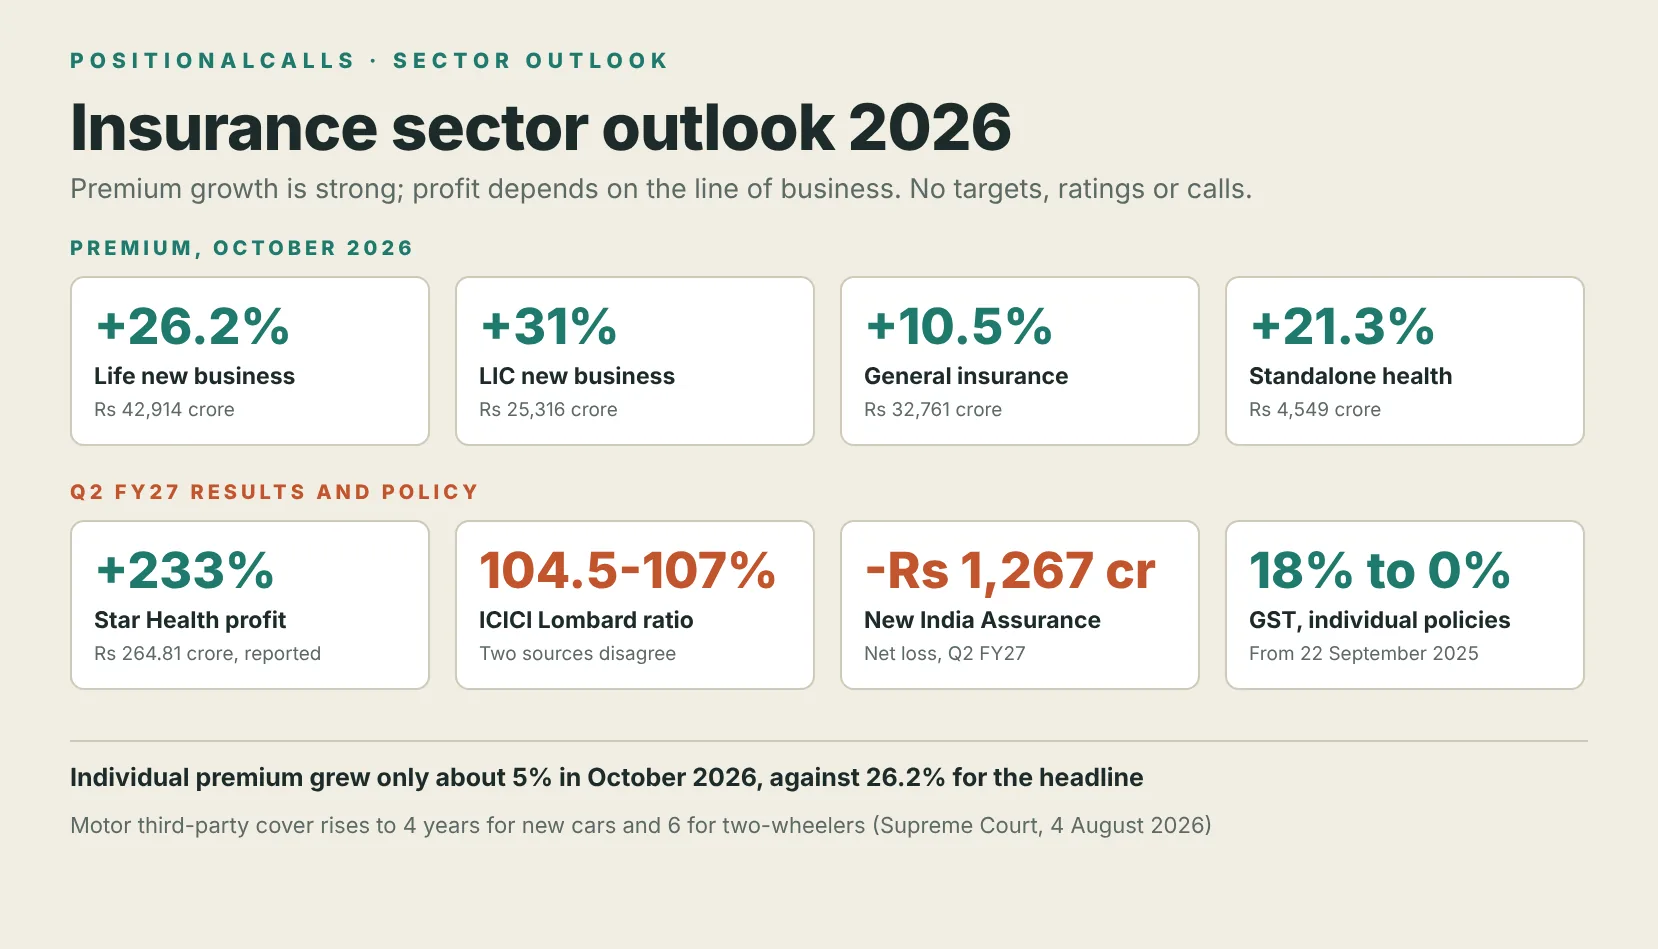
- Growth: life premium +26.2% and general premium +10.5% in October 2026, flattered by the September 2025 base.
- Quality: individual weighted premium grew only about 5%, and policy counts lag premium.
- Profit: Q2 FY27 profit rose at Star Health, ICICI Lombard and SBI Life; New India Assurance lost Rs 1,267 crore.
- Policy: GST exemption, a Council recommendation on group credit and two Supreme Court rulings shape costs.
- Doubt: five source conflicts are recorded, including ICICI Lombard’s combined ratio at 104.5% or 107%.
In plain words: people are buying more insurance, and insurers are collecting more premium. Whether insurers keep more of it as profit depends on tax credit, court awards and health claims, and the data do not yet agree on that.
Data note: as of Saturday, 21 November 2026, 10:00 AM IST. Premium figures are provisional Life Insurance Council and General Insurance Council data for October 2026, as relayed by news reports. Company figures are from Q2 FY27 releases and reports for the quarter ended 30 September 2026. I did not open exchange filings, IRDAI tables or the Supreme Court judgment text for every figure, and lines marked as my arithmetic are my own calculation.
Insurance sector outlook 2026: where does the sector stand in November 2026?
The insurance sector outlook 2026 shows premium growth that has accelerated, with profit that depends on the line of business. The table collects the latest dated figures this page uses. Every figure is as reported by the source named, and the period is shown so that a monthly number is not read as a yearly one.
| Measure | Latest figure | Period | Source named |
|---|---|---|---|
| Life new business premium | Rs 42,914 crore, up 26.2% | October 2026 | Life Insurance Council, via PSU Watch and Cafemutual |
| LIC new business premium | Rs 25,316 crore, up 31% | October 2026 | Life Insurance Council, via PSU Watch |
| Private life new business premium | Rs 17,598.82 crore, up 19.45% | October 2026 | Life Insurance Council, via India IPO |
| General insurance gross direct premium | Rs 32,761 crore, up 10.5% | October 2026 | General Insurance Council, via Kotak Neo |
| Standalone health premium | Rs 4,549 crore, up 21.29% | October 2026 | General Insurance Council, via Kotak Neo |
| General insurance premium growth | 9.13% | April to October FY27 | General Insurance Council, via StockGro |
Cite this table: Insurance sector snapshot, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, figures as reported by the sources named.
Two readings of this table are worth keeping apart. The first is volume: more premium is being written in both life and general insurance. The second is quality: a premium rupee collected is not a profit rupee earned. In life insurance the quality test is the value of new business and its margin. In general insurance it is the combined ratio, which adds claims and expenses as a share of premium. A ratio above 100% means underwriting lost money before investment income.
Forecasters expect the growth to last, but they differ on the pace and on what they measure. The table below sets them side by side, because mixing a real forecast with a nominal one is a common error in any insurance sector outlook 2026 article.
| Forecaster | What it says | Horizon | Measure |
|---|---|---|---|
| Swiss Re | Premium growth of 6.9% a year, the strongest major market | 2026 to 2030 | Real, annual average |
| Allianz Global Insurance Report 2026 | Fastest-growing major market, 10.7% a year | To 2036 | Premium income, annual average |
| Emkay Research | Retail annualised premium equivalent up 11-12%; private insurers 13-14%, LIC 7-8% | FY27 | Life, retail APE |
| Sector estimates, Insurance Business | Life premium growth of 8% to 11%, after 15.7% in FY26 | FY27 | Life premium |
| Insurance Business, FY26 actual | General insurance gross written premium up 9.3% | FY26 | General insurance |
Cite this table: Forecasts and actuals for Indian insurance, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, as reported; measures differ across rows.
The Swiss Re figure is in real terms, which strips out inflation, so it is not comparable with the nominal premium growth in the monthly data. Allianz also reports life insurance as nearly 74% of total premium income, which is why the life numbers in the next section carry most of the weight in the sector story.
What do the life insurance numbers show in the insurance sector outlook 2026?
Life insurers have posted double-digit new business growth through FY27, led by LIC in October and by private insurers in the first quarter. The monthly figures are volatile, so the table sets three periods next to each other.
| Period | Industry | LIC | Private insurers |
|---|---|---|---|
| Q1 FY27 (April to June 2026) | Rs 1.09 lakh crore, up 16.6% | Rs 65,548 crore, up 10.3% | Rs 43,522 crore, up 27.5% |
| April to May FY27 | Rs 62,581 crore, up 19.4% | Not split in the source | Not split in the source |
| October 2026 | Rs 42,914 crore, up 26.2% | Rs 25,315.52 crore, up 31.35% | Rs 17,598.82 crore, up 19.45% |
Cite this table: Life new business premium, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, Life Insurance Council data as reported by Kotak Neo, Angel One and India IPO.
From the October figures, my own arithmetic puts LIC at about 59% of the month’s new business premium and private insurers at about 41%. In the first quarter, one report put private insurers’ market share at nearly 40%, so the split has been steady. The faster private growth in the first quarter came with group single premium business, and the faster LIC growth in October rode a low base.
Is life insurance growth in the insurance sector outlook 2026 broad-based?
Not yet. In April and May FY27, life insurers added about Rs 10,000 crore of premium, and a large part came from group single premium business of Rs 37,537 crore. Premium rose 19.4% in that period, but policy count rose only 5%. The same pattern shows in October 2026: new business premium rose 26.2%, while individual weighted received premium rose about 5%. Group business is lumpy, tied to a few large contracts, and carries thinner margins than regular-premium protection.
The base effect matters as much. October 2025 followed the GST exemption, when LIC’s policy sales more than doubled and its individual premium jumped. A year later, that comparison makes October 2026 look weaker in individual business and stronger in group. One report on the October data described the 5% individual growth as likely reflecting a base effect after the September 2025 exemption.
Emkay’s FY27 view is that private insurers will lead, with retail APE growth of 13-14% against 7-8% for LIC. That is a forecast from one brokerage, shown here as that source’s estimate, not as a figure the page endorses. For the plan side of life insurance, see best term insurance plans in India and the stock-data page best life insurance stocks in India.
What do the general insurance numbers show in the insurance sector outlook 2026?
General insurance premium grew 10.5% in October 2026, but monthly growth has swung between 5.7% and 15.9% this year. Health and motor drive the growth, while fire and crop have dragged in several months.
| Segment | October 2026 premium | Year-on-year growth | Note |
|---|---|---|---|
| Industry total | Rs 32,761 crore (Rs 29,641 crore in October 2025) | +10.5% | Provisional, General Insurance Council |
| Multi-line general insurers | Rs 28,062 crore | +10.15% | HDFC ERGO and SBI General reported strong growth |
| Standalone health insurers | Rs 4,549 crore | +21.29% | About 13.9% of the total, my arithmetic |
| Remainder | About Rs 150 crore | Not stated | Third category, my arithmetic, not broken out in the sources |
Cite this table: General insurance premium, October 2026, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, General Insurance Council data as reported.
Earlier in 2026 the monthly path was uneven. Growth was 15.9% in June, when health, motor and personal accident expanded, and slowed to 5.7% in July as fire and crop premium fell. Emkay put second-quarter FY27 growth at about 7%, and ICICI Lombard’s management said industry premium grew 8.9% in the first half, excluding crop and mass health. Personal accident and health made up about 40.9% of general insurance premium in 2025, up from 35.7% in 2021, which is why health growth moves the whole total.
Why is profit the weak point of the insurance sector outlook 2026 in general insurance?
Because premium growth has outrun underwriting results. ICICI Lombard’s management cited an industry combined ratio of 116.8% in the first quarter of FY27, meaning the industry paid out far more than it earned in underwriting. S&P Global Ratings said in August 2026 that profitability pressure would persist, especially in non-life insurance, even as reforms attract capital. Motor own damage and retail health are growing, but competition in motor pricing keeps margins thin.
Health insurers are the exception worth watching. Star Health’s combined insurance service ratio improved to 98.0% in Q2 FY27 from 100.9%, and Niva Bupa’s profit rose 124%. Both numbers are in the results section below. For plan-level data, see best health insurance plans in India and best general insurance stocks in India.
How do GST, FDI and court rulings change the insurance sector outlook 2026?
Four rule changes shape the insurance sector outlook 2026: the GST exemption, the Council’s recommendation on group credit, 100% FDI and two Supreme Court rulings. Each has a date, so the table lists them in order.
| Date | Change | Effect on insurers | Status |
|---|---|---|---|
| 22 September 2025 | GST on individual life and health policies cut from 18% to nil; group policies still taxed at 18% | Lower customer cost; insurers lose input tax credit on commissions, rent and software | In force |
| 2025 (date not confirmed) | Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Bill, 2025, reported as enabling 100% FDI | More competition and foreign capital | Reported; I did not open the Act |
| June 2026 | Supreme Court recognises the economic value of homemakers’ unpaid work in accident compensation | Higher motor claim awards, possible pullback from motor third-party | Ruling, as reported by Kotak |
| 4 August 2026 | Supreme Court extends third-party cover to four years for new cars and six for new two-wheelers | More mandatory premium per new vehicle; higher long-term claims exposure | Directed, IRDAI to issue rules |
| 8 October 2026 | 57th GST Council recommends removing the blocked-credit rule on employee health and life cover | Employers could claim credit on group premium | Recommendation only as of 20 October 2026 |
Cite this table: Insurance rule changes, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, as reported by the sources named in the sources section.
What did the GST change do to the insurance sector outlook 2026?
For customers it removed an 18% tax on individual cover. For insurers it removed the credit they claimed on GST paid for commissions, rent and software, which Business Standard estimated at about Rs 15,000 crore for life insurers. Life insurers told the regulator through the Life Insurance Council that they would cut distributor commissions on new business to pass on the full benefit, so insurers and distributors share the loss. ICICI Lombard, Care Health and Aditya Birla Health also lowered retail health commissions, with some cuts of about 18%.
A year later, Business Today wrote in October 2026 that consumers were still waiting for the full benefit in premiums. The Council’s 8 October recommendation concerns employers, who could claim credit on group premiums if the law is amended. The sources I read describe it as employer-side credit, and none says that insurers regain credit on individual policies. As of 20 October 2026 it was only a recommendation.
What did the Supreme Court change for the insurance sector outlook 2026?
The 4 August 2026 judgment raised the minimum third-party term over the objection of IRDAI and the General Insurance Council, according to LiveLaw. Third-party cover for new cars goes from three to four years and for new two-wheelers from five to six. It adds premium at sale, but also adds claims exposure, and the Institute of Actuaries of India has warned that court awards inflation affects reserves for unsettled claims. ICICI Lombard raised reserves by Rs 1.65 billion in Q1 FY27 after a Supreme Court judgment, and New India Assurance booked an extra Rs 715 crore in Q2.
What did insurers report for Q2 FY27 in the insurance sector outlook 2026?
Life insurers reported steady value-of-new-business growth in Q2 FY27, while general and health insurers split between strong profit gains and one large loss. The first table covers life insurers, the second general and health insurers.
PositionalCalls WhatsApp channel
Follow sector pages in one place
- New sector outlooks as they are posted
- Results summaries without tips
- A message when a page is updated
| Insurer | Profit and premium | Value of new business and margin | Source named |
|---|---|---|---|
| SBI Life | Q2 profit Rs 549 crore, up 10%; H1 new business premium Rs 20,260 crore, up 10% | H1 VoNB Rs 3,270 crore, up 19%, margin 27.9%; solvency 1.97 | Multibagg, Investywise |
| HDFC Life | Q2 profit before tax Rs 540.5 crore, up 15.5%; Q2 APE up 13% | H1 VNB Rs 2,037 crore, up 12.1%; Q2 VNB growth 14.8% | Cafemutual, company commentary |
| ICICI Prudential Life | H1 profit Rs 760 crore, up 26.5%; seven-month new business premium Rs 14,258 crore, up 27% | October APE up 8.6%, retail APE down 3.2% | JM Financial news item |
| LIC | Q2 net profit Rs 12,076 crore, up 20% | Not stated in the source | PSU Watch headline |
Cite this table: Life insurer results, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, as reported; SBI Life crore figures are my conversion from billions.
SBI Life’s embedded value was Rs 873.5 billion, which is Rs 87,350 crore in my conversion, up 15%. HDFC Life’s was Rs 66,461 crore. Embedded value is the present value of future profits on in-force business plus net worth, and a company’s own actuaries calculate it, so compare it across insurers with care. For LIC’s own page, see LIC Q2 results FY27.
| Insurer | Profit | Combined ratio or underwriting | Other items |
|---|---|---|---|
| ICICI Lombard | Q2 profit Rs 946 crore, up about 15% from Rs 820 crore | 104.5% on the company call; 107% in one news report | H1 premium up 5.4% against industry 8.9% |
| Star Health | Q2 profit Rs 264.81 crore, up 233%; normalised Rs 390 crore, up 70% | Combined insurance service ratio 98.0%, from 100.9% | H1 underwriting profit Rs 210 crore against a loss of Rs 24 crore |
| Niva Bupa | Q2 profit up 124% | Claims ratio 63.09% | Retail market share 11% in H1 FY27, from 9.9% |
| New India Assurance | Net loss Rs 1,267 crore | Premium up 5.14% | Extra Rs 715 crore Motor TP provision after a Supreme Court verdict |
Cite this table: General and health insurer results, Q2 FY27, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, as reported by the sources named.
Three patterns stand out. Health-focused insurers improved fastest because claims ratios fell and retail premium grew. The private multi-line insurer’s profit rose on investment income more than on underwriting, since its combined ratio stayed above 100%. The public sector insurer’s loss came from a reserve charge, which shows how a court ruling can move a quarter’s result. For a plan-level view, see best family health insurance plans.
Where do sources disagree on the insurance sector outlook 2026?
Five conflicts appear in the Q2 FY27 data, and each affects how strong a result looks. The table shows both versions and the one this page uses.
| Item | Version A | Version B | How this page handles it |
|---|---|---|---|
| ICICI Lombard combined ratio, Q2 FY27 | 104.5% (company earnings call, as relayed by Multibagg) | 107%, up 190 basis points (Business Today) | Shows both; 104.5% matches the call, 107% is unexplained |
| Star Health Q2 profit | Rs 264.81 crore reported, up 233% | Rs 390 crore normalised, up 70% (company release) | Uses reported; shows normalised as the company’s own measure |
| Standalone health premium growth, October 2026 | 21.29% (General Insurance Council, via Kotak Neo) | About 21.7% from Rs 3,738.34 crore a year earlier, my arithmetic | Uses 21.29%; the base was probably revised |
| GST Council date for employer credit | Expected on 7 October 2026 (pre-meeting reports) | Held 8 October 2026 (Taxguru, Coverfox) | Uses 8 October |
| SBI Life Q2 profit and premium growth | Profit Rs 549 crore, up 10% (Multibagg) | Gross written premium up 13% (Investywise headline) | Reports both as different measures |
Cite this table: Source conflicts in insurance data, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, as recorded from the sources named.
Most of these are definition gaps, not mistakes. A reported figure includes one-off items, a normalised one removes them, and a monthly figure compares against a base that the council may have revised. The one I could not explain is the 107% ratio, because the same report gave its catastrophe loss as Rs 1.2 billion, close to the Rs 1.18 billion in the company call. I did not open the ICICI Lombard filing, so this page does not pick a winner beyond noting that the call figure is the company’s own.
What are the risks to the insurance sector outlook 2026?
Six risks could make the insurance sector outlook 2026 wrong, and two of them already show in reported numbers. Red marks risks visible in results, amber marks data effects, and blue marks risks that depend on future events.
The risks are not independent. If commission cuts are reversed to keep distributors, the lost credit returns as a cost. If third-party claims keep rising, motor pricing must rise, which can slow volume. A fall in group single premium would pull down headline life growth even if retail business holds. That is why this page treats a single month of premium growth as a signal to check, not a conclusion.
Bottom line
The insurance sector outlook 2026 is strong on volume and mixed on profit. Premium growth is real, but it is supported by group business and a GST base effect, and the profit evidence splits between health insurers and public sector motor exposure.
What should you watch next in the insurance sector outlook 2026?
Watch the monthly council data, the next results season and four rule items. The table gives each item and the figure to compare it against.
| Item to watch | Why it matters | Compare against |
|---|---|---|
| November life premium data, mid-December 2026 | Shows whether growth holds after the base effect fades | October: new business premium up 26.2%, individual up about 5% |
| November general insurance data | Tests whether health growth continues and fire and crop recover | October: premium up 10.5%, standalone health up 21.29% |
| Notification of the GST credit amendment | Decides whether employers can claim credit on group premium | Recommendation of 8 October 2026 |
| IRDAI rules for four-year and six-year third-party cover | Sets how the 4 August 2026 order is implemented | Court direction that IRDAI issue rules immediately |
| Q3 FY27 results in January 2027 | Shows whether the Q2 profit pattern repeats | Q2 combined ratios and VNB margins in this page |
| Distribution and expense-of-management norms | Could change commission and margin structure | Kotak’s note that calls would focus on them |
Cite this table: Insurance watch list, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, dates as reported; later dates may move.
The monthly releases come from the two councils in the second week of each month, so December’s release should carry November’s data. If your decision depends on a single month, the quarterly results are the better check, because they include profit and value of new business, which monthly premium data do not.
How should you read insurance data in the insurance sector outlook 2026?
Read premium first, then quality, then profit, and never treat one month as a trend. The steps below work for any insurer or council release.
- Check whether the figure is new business premium, total premium or annualised premium equivalent.
- Separate individual from group business, because group is lumpy.
- Check the base month, since September 2025 changed the comparison.
- For life insurers, read value of new business and its margin, not only premium.
- For general insurers, read the combined ratio and whether it is reported or adjusted.
What is the difference between the main insurance measures?
| Measure | What it counts | Used by | Common trap |
|---|---|---|---|
| New business premium | First-year and single premium collected | Life Insurance Council | Group single premium inflates it |
| Annualised premium equivalent | Regular premium plus a tenth of single premium | Life insurers | Mix of products differs by insurer |
| Value of new business margin | Present value of future profit as a share of APE | Life insurers | Assumptions are the insurer’s own |
| Gross direct premium | Premium written in India before reinsurance | General Insurance Council | Accounting changes can distort the base |
| Combined ratio | Claims plus expenses as a share of premium | General and health insurers | Reported against adjusted |
Cite this table: Insurance measures explained, PositionalCalls, Saturday, 21 November 2026, 10:00 AM IST, general definitions.
For a sector page, the useful question is whether premium growth is turning into profit. In life insurance, check whether margin held while premium grew. In general insurance, check whether the combined ratio fell. In both, check the date, since the insurance sector outlook 2026 is a moving picture and this page carries its own Updated line.
What pages sit beside the insurance sector outlook 2026?
The stock-data pages and plan pages give the company and product layer under this sector view.
- Sector hub: sector outlook India, twelve sector pages
- Related sector: NBFC sector outlook 2026, on lender credit growth, the repo rate and asset quality
- Insurance stock data: best insurance stocks in India, life insurance stocks and general insurance stocks
- Plans: health insurance plans, term insurance plans and super top-up health insurance
- Family and age cover: health insurance for parents and senior citizen health insurance
- Insurance category: all insurance posts
This page is the sector view. It does not rank insurers or plans. The stock-data pages show company figures, and the plan pages compare policies, so use them for those jobs.
Sources for the insurance sector outlook 2026 page
Every figure comes from the sources below, read on 21 November 2026. I did not open the Life Insurance Council or General Insurance Council tables, insurer filings, IRDAI data or the Supreme Court judgment text for each figure, so use the links to reach the primary source.
- Kotak Neo: General insurance premium growth, October 2026
- PSU Watch: Life insurers post 26% growth in new business premiums in October
- India IPO: Insurance sector performance in October 2026
- Kotak Neo: Life insurance new business premium, Q1 FY27
- Angel One: Life insurance premiums, April to May FY27
- Swiss Re: India insurance market outlook, 19 January 2026
- Business Today: Allianz Global Insurance Report 2026, 3 June 2026
- ANI via Times of Oman: Emkay life insurance forecast, 8 September 2026
- Insurance Business: India insurance growth to cool in FY27, 5 May 2026
- Business Standard: S&P on insurance profitability, 6 August 2026
- Business Standard: Life insurers cut agents’ commission after GST exemption
- Taxguru: 57th GST Council meeting, 8 October 2026
- The Tax Corp: Input tax credit on health and life insurance after the proposed amendment
- LiveLaw: Supreme Court directs longer third-party insurance, 4 August 2026
- IANS via NewKerala: Motor third-party insurance growth slows, Kotak
- Investywise: SBI Life Q2 FY27 earnings call
- Cafemutual: HDFC Life Jul-Sep profit
- JM Financial: ICICI Life seven-month new business premium
- UNI/PR Newswire: Star Health Q2 FY27 results
- PSU Connect: New India Assurance Q2 FY27 results
- Compounding AI: ICICI Lombard Q2 FY27 earnings call
- Business Today: ICICI Lombard Q2 FY27 reaction
- Kotak Neo: Niva Bupa Q2 FY27 results
Where a source is a news report on council data, the report is named, not the council. If any figure differs from the primary release, the primary release governs.
Disclaimer: PositionalCalls is not a SEBI-registered research analyst or investment adviser. This page is general information and gives no target, rating or buy or sell call. Figures may have changed since the date shown.
PositionalCalls WhatsApp channel
Keep sector updates together
- Quarterly result summaries
- Budget and policy changes
- Links to new sector pages
Insurance sector outlook 2026: frequently asked questions
What is the insurance sector outlook 2026 for India?
Premium growth is strong and profit is uneven. Life insurers’ new business premium rose 26.2% in October 2026 and general insurers’ premium rose 10.5%, yet insurers lost input tax credit after the GST exemption, and motor rulings raised claims costs. This page tests that view against dated data, shows source conflicts and makes no stock call.
How fast did life insurers grow in October 2026?
Life insurers’ new business premium rose 26.2% to Rs 42,914 crore in October 2026, per Life Insurance Council data as reported. LIC grew 31.35% to Rs 25,315.52 crore and private insurers grew 19.45% to Rs 17,598.82 crore. Individual weighted received premium grew only about 5%, so the headline leans on a low base and group business.
How fast did general insurance premium grow in October 2026?
Gross direct premium of general insurers rose 10.5% to Rs 32,761 crore in October 2026, per provisional General Insurance Council data. Standalone health insurers grew faster, up 21.29% to Rs 4,549 crore. April to October FY27 growth was 9.13%. Growth had been uneven earlier, with 15.9% in June and 5.7% in July.
How did the GST exemption change the insurance sector outlook 2026?
Individual life and health premiums became GST-exempt on 22 September 2025, which lowered customer cost and lifted demand. Insurers lost input tax credit on expenses such as commissions and rent, estimated at about Rs 15,000 crore for life insurers, and cut distributor commissions to offset it. Group policies still carry 18% GST, which the Council’s October 2026 recommendation targets.
What did the Supreme Court change for motor insurers?
On 4 August 2026 the Court raised mandatory third-party cover for new cars from three to four years and for new two-wheelers from five to six years. A June 2026 ruling on homemakers’ unpaid work also raised compensation awards. New India Assurance booked an extra Rs 715 crore Motor TP provision after a Supreme Court verdict, per its Q2 FY27 release.
Which risks shape the insurance sector outlook 2026?
Five risks matter most: lost input tax credit, rising court-awarded motor claims, reliance on group single premium for growth, health claims inflation, and a base effect from the September 2025 GST change. Regulatory moves on distribution norms are a sixth item to watch. Each risk is shown with its source in the risks section of this page.
Do Q2 FY27 results show profit growth for insurers?
Mostly yes, but not for all. Star Health’s profit rose 233% to Rs 264.81 crore, ICICI Lombard’s rose about 15% to Rs 946 crore and SBI Life’s rose about 10% to Rs 549 crore. New India Assurance reported a net loss of Rs 1,267 crore. The page lists each result with its period and source.
Why do sources disagree on insurer ratios and profits?
They use different definitions. ICICI Lombard’s combined ratio is 104.5% on the company’s call and 107% in one news report. Star Health reports Rs 264.81 crore profit and Rs 390 crore normalised profit. The insurance sector outlook 2026 conflicts table lists each pair, says which version this page uses and why.
Does this insurance sector outlook 2026 page recommend stocks?
No. PositionalCalls is not a SEBI-registered research analyst or investment adviser. This insurance sector outlook 2026 page reports company and industry figures with sources, labels its own arithmetic and records where sources disagree. It gives no target, rating or buy or sell call. Open the filings and the stock-data pages before you decide anything.
How often is the insurance sector outlook 2026 page updated?
After each monthly premium release, after each results season and when a rule changes. Life insurers report monthly through the Life Insurance Council and general insurers through the General Insurance Council, usually in the second week. Check the Updated line and the data note first, since figures here carry the date of their source.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive