Earnings · Power · NHPC
NHPC reported profit up 52% on one measure and 65% on another. This page shows which profit is which, what the Rs 231 crore Teesta IV provision and doubled finance costs did, and how the shares reacted.
Quick answer
NHPC Q2 results FY27 were approved by the board on Wednesday, 4 November 2026: consolidated profit attributable to owners was Rs 1,549 crore, up 51.7%, and standalone profit was Rs 1,525 crore, up 65%. A third figure, Rs 1,657.57 crore (+36%), is total consolidated profit. Standalone profit includes a Rs 231 crore Teesta IV provision.
Latest update (Friday, 6 November 2026, 10:00 AM IST): NHPC’s board approved the results on Wednesday, 4 November 2026, and the earnings call was on Thursday, 5 November. On 5 November the stock touched Rs 83.49 against a previous close of Rs 78.45 and closed near Rs 80.32, per MarketsMojo. I found no brokerage notes and no interim dividend notice. I will add the NSE close check and the filing’s tax lines on Friday, 6 November.
Key takeaways
- Three profits: Rs 1,549.09 crore (+51.7%, attributable), Rs 1,657.57 crore (+36%, total consolidated) and Rs 1,525.49 crore (+64.8%, standalone) all describe Q2 FY27; each has a different year-ago base.
- Revenue: Consolidated revenue was Rs 4,482.55 crore (+33.2%) and standalone Rs 4,124.77 crore (+51%); Subansiri Lower and Parbati-II supplied about 30% of standalone revenue, provisionally.
- Margins: Consolidated PBDIT was Rs 2,875.77 crore (+41.9%) at a 64.15% margin against 60.23%.
- Costs: Standalone finance costs doubled to Rs 552.32 crore and depreciation rose to Rs 588.06 crore; debt-equity rose to 1.18 from 1.04.
- One-off: A Rs 231.30 crore provision on Teesta IV survey costs sits inside standalone expenses, which appears to be the case because income less expenses equals reported pre-tax profit exactly (my inference).
- Share price: The stock closed near Rs 80.32 (+2.4%) on 5 November after touching Rs 83.49, per one page; another shows Rs 80.60 (+2.69%) at 3:31 PM.
In plain words: NHPC is a government-owned hydropower company that sells electricity at tariffs set by the regulator, CERC. “Standalone” means NHPC alone; “consolidated” adds subsidiaries and joint ventures. PBDIT is operating profit before depreciation, interest and tax. Revenue from new plants is booked provisionally until CERC approves the tariff.
Data note: as of Friday, 6 November 2026, 10:00 AM IST. Figures come from press and data-platform summaries of the 4 November filing (PSU Watch, Indian Masterminds, Whalesbook, Sahi, Sarkaritel, MarketsMojo and Trendlyne); I did not open the filing or the investor presentation. Consolidated profit appears as Rs 1,549 crore, Rs 1,550 crore and Rs 1,657.57 crore, and revenue as Rs 4,482 crore or total income of Rs 4,669.58 crore; each is shown where it applies. Derived numbers are marked “my calculation”.
NHPC Q2 results FY27: key numbers at a glance
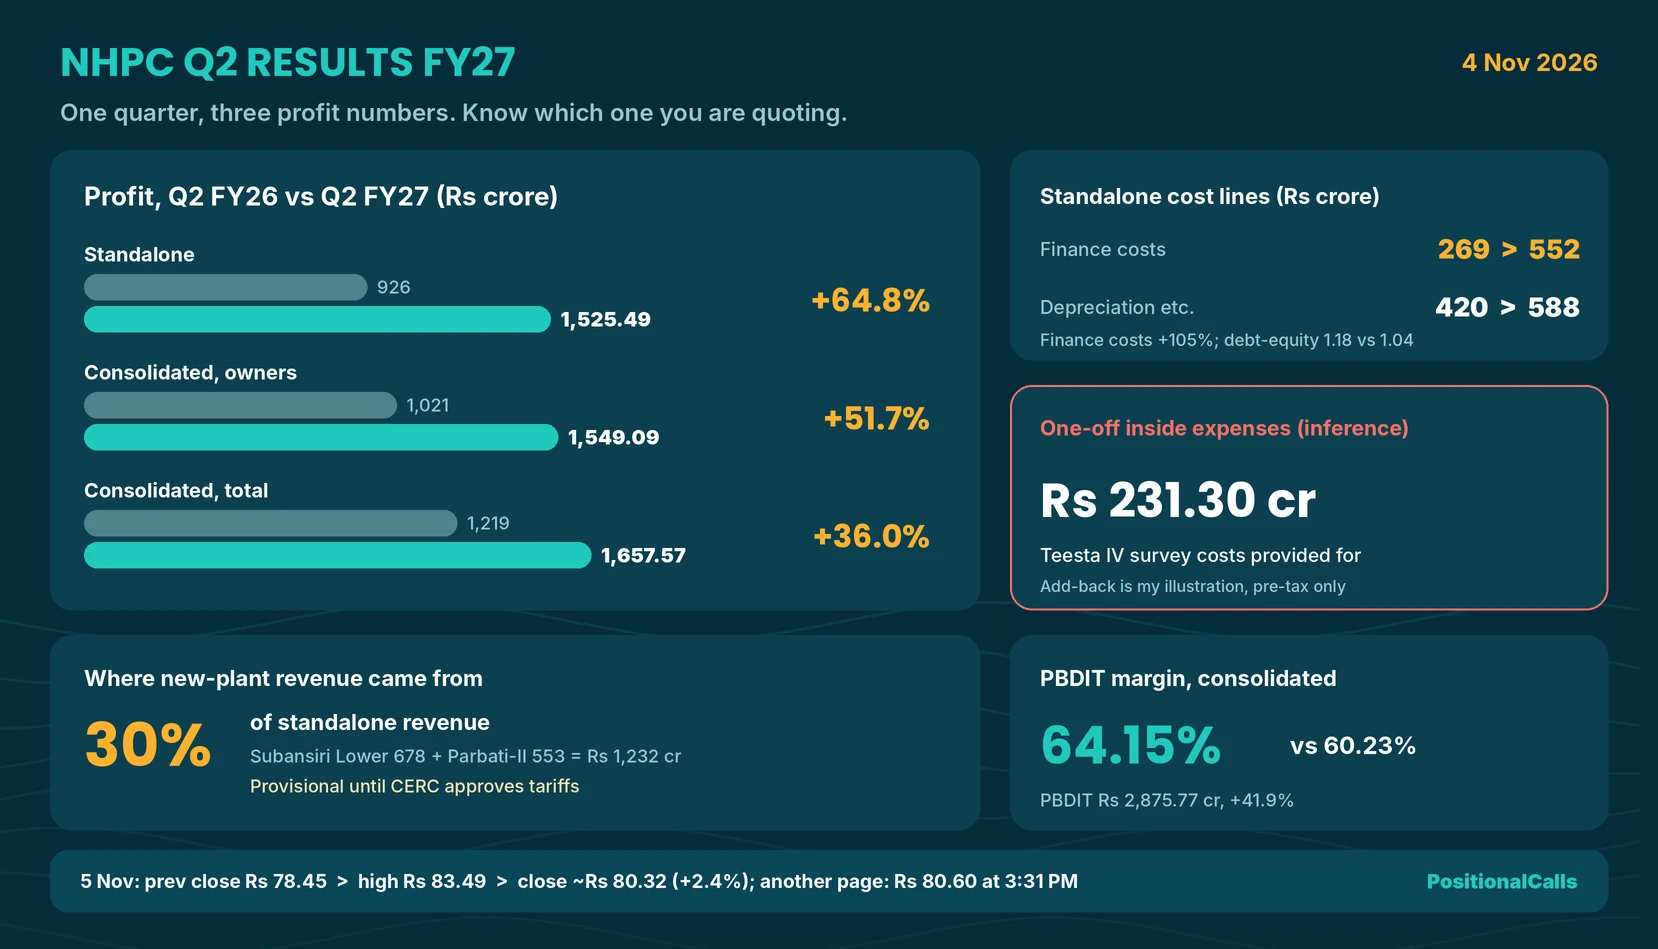
NHPC Q2 results FY27 show consolidated profit to owners of Rs 1,549.09 crore (+51.7%), consolidated revenue of Rs 4,482.55 crore (+33.2%), standalone profit of Rs 1,525.49 crore (+64.8%) and PBDIT of Rs 2,875.77 crore.
| Rs crore | Q2 FY27 | Q2 FY26 | Change | Basis and note |
|---|---|---|---|---|
| Consolidated revenue from operations | 4,482.55 | about 3,365 | +33.2% | Sahi; MarketsMojo |
| Consolidated total income | 4,669.58 | 3,629.98 | +28.6% | PSU Watch |
| Consolidated PBDIT | 2,875.77 | about 2,027 | +41.9% | Margin 64.15% against 60.23% |
| Consolidated profit to owners | 1,549.09 | about 1,021 | +51.7% | MarketsMojo; Sarkaritel; Sahi rounds to 1,550 |
| Total consolidated profit | 1,657.57 | 1,219.28 | +35.9% | PSU Watch; includes minority share |
| Standalone revenue from operations | 4,124.77 | 2,732.11 | +51.0% | Whalesbook; Indian Masterminds |
| Standalone profit after tax | 1,525.49 | 925.52 | +64.8% | Q1 FY27: 1,113.41 |
Cite this table: PositionalCalls, “NHPC Q2 Results FY27 Key Numbers Table, as of 5 November 2026”.
NHPC Q2 results FY27 cover the quarter ended 30 September 2026. Standalone half-year profit was Rs 2,639 crore, up 32% from Rs 1,997 crore, and it ties to Q1 plus Q2 (1,113.41 + 1,525.49, my calculation). Half-year generation was a record 21,469 million units, up 27%, per Sarkaritel. Confirm every figure on the BSE or NSE page and see the Q2 results calendar for other companies.
When were the NHPC Q2 results FY27 announced?
NHPC’s board approved the Q2 FY27 results on Wednesday, 4 November 2026, and the company held an earnings call on Thursday, 5 November 2026, the day of the first trading reaction.
The results are unaudited with an unmodified limited-review conclusion from the joint statutory auditors, per Indian Masterminds. I have not opened the board notice, so confirm the filing time on the exchange page; the legal deadline for Q2 filings was 14 November 2026.
Why do NHPC Q2 results FY27 show three different profit figures?
The three figures are three different measures: Rs 1,549 crore is consolidated profit attributable to owners (base Rs 1,021 crore), Rs 1,657.57 crore is total consolidated profit including minorities (base Rs 1,219.28 crore), and Rs 1,525 crore is standalone profit (base Rs 925.52 crore).
| Profit measure | Q2 FY27 (Rs crore) | Q2 FY26 (Rs crore) | Growth | Where you see it |
|---|---|---|---|---|
| Standalone profit after tax | 1,525.49 | 925.52 | +64.8% | Whalesbook; Sarkaritel (+65%) |
| Consolidated, attributable to owners | 1,549.09 | about 1,021 | +51.7% | MarketsMojo; Power Peak (+51.7%) |
| Consolidated, total (incl. minorities) | 1,657.57 | 1,219.28 | +35.9% | PSU Watch; Indian Masterminds (+36%) |
| Minority share (difference, my calculation) | 108.48 | 198.28 | – | Not shown on its own in reports |
Cite this table: PositionalCalls, “NHPC Three Profit Figures Table, as of 5 November 2026”.
The gap between the two consolidated figures looks like the share of minority holders, which fell from about Rs 198 crore to about Rs 108 crore (my inference; I did not see the statement). Use profit attributable to owners for per-share work: MarketsMojo reports EPS of Rs 1.54, which is the strongest quarterly EPS it records for NHPC. The 65% standalone growth compares a quarter helped by new plants against a base that was lower, so do not quote it as the group’s growth. Sahi says consolidated profit beat a consensus estimate of Rs 1,220 crore by more than 27%, which I could not verify.
Inside the NHPC Q2 standalone profit: income, expenses and tax
In the NHPC Q2 results FY27, standalone total income of Rs 4,328.50 crore less expenses of Rs 2,641.32 crore gives profit before tax of Rs 1,687.18 crore (+54.6%), and tax of about Rs 162 crore, a low 9.6% share, leaves Rs 1,525.49 crore (my calculation).
| Standalone, Rs crore | Q2 FY27 | Q2 FY26 (derived) | Change | Note |
|---|---|---|---|---|
| Revenue from operations | 4,124.77 | 2,732.11 | +51.0% | Subansiri Lower and Parbati-II provisional |
| Other income (total income less revenue) | 203.73 | 262.33 | -22.3% | My calculation |
| Total income | 4,328.50 | 2,994.44 | +44.6% | Indian Masterminds |
| Total expenses | 2,641.32 | 1,902.83 | +38.81% | Includes Teesta IV provision (inference) |
| Profit before tax | 1,687.18 | 1,091.60 | +54.56% | Ties: 4,328.50 less 2,641.32 |
| Implied tax (PBT less PAT) | 161.69 | 166.08 | 9.6% against 15.2% of PBT | My calculation |
| Profit after tax | 1,525.49 | 925.52 | +64.8% | Reported |
Cite this table: PositionalCalls, “NHPC Standalone Profit Bridge Table, as of 5 November 2026”.
Because income less expenses equals the reported profit before tax to the paisa, there is no separate exceptional line, so the Rs 231.30 crore Teesta IV provision appears to sit inside the Rs 2,641.32 crore of expenses; this is my inference, not a reported fact. The implied tax share fell from about 15% to about 10%, which lifts profit after tax growth to 64.8% against pre-tax growth of 54.6%; the reports do not explain the lower share, so check the tax note in the filing.
NHPC finance costs doubled: the cost lines and the NHPC Teesta IV provision
In the NHPC Q2 results FY27, standalone finance costs rose 105% to Rs 552.32 crore and depreciation rose to Rs 588.06 crore as new plants started, while the Rs 231.30 crore Teesta IV provision is a one-off; adding it back gives pre-tax profit near Rs 1,918 crore (+76%) as my illustration.
| Standalone cost line, Rs crore | Q2 FY27 | Q2 FY26 | Change | Comment |
|---|---|---|---|---|
| Finance costs | 552.32 | 269.34 | +105.1% | Indian Masterminds |
| Depreciation, amortisation, impairment | 588.06 | 419.81 | +40.1% | Indian Masterminds |
| All other expenses (derived) | 1,500.94 | 1,213.68 | +23.7% | Total less finance and depreciation |
| Of which Teesta IV provision | 231.30 | – | – | Survey and investigation costs written off |
| Other expenses excluding the provision | 1,269.64 | 1,213.68 | +4.6% | Illustration, assumes provision is in this line |
| Debt-equity ratio | 1.18 | 1.04 | – | Standalone, 30 September 2026 |
Cite this table: PositionalCalls, “NHPC Cost Lines Table, as of 5 November 2026”.
Finance costs doubled because interest on a new project stops being capitalised once units are commissioned and starts hitting the profit and loss account; that is the usual accounting pattern, though the reports do not say it for NHPC. Teesta IV is a project where the company wrote off survey and investigation spending previously held as capital work in progress because implementation is uncertain. The add-back is an illustration before tax effects, not a restated result, and it works only if the provision sits inside expenses. Interest costs for the six months were Rs 1,161.93 crore on the consolidated basis (+31.4%), per MarketsMojo.
PositionalCalls WhatsApp channel
PSU and power results on WhatsApp
- Same-day results notes with the profit basis named
- Provisions and one-offs separated from the core number
- Price moves the day they appear
How much of the NHPC Q2 results FY27 revenue came from Subansiri Lower and Parbati-II?
In the NHPC Subansiri Lower revenue line, Subansiri Lower and Parbati-II together contributed Rs 1,231.64 crore, about 30% of standalone revenue, but both are provisional until CERC approves their tariffs.
| Plant | Q2 FY27 sales (Rs crore) | Capacity | Note |
|---|---|---|---|
| Subansiri Lower | 678.17 | 1,250 MW commissioned of 2,000 MW | Fifth 250 MW unit began commercial operation 23 October 2026 |
| Parbati-II | 553.47 | 800 MW | Provisional sales |
| Together | 1,231.64 | – | 29.9% of standalone revenue (my calculation) |
Cite this table: PositionalCalls, “NHPC Plant Revenue Table, as of 5 November 2026”.
Because the tariff is not yet approved, the revenue can be adjusted later, which would flow into future profit. Subansiri Lower reached 1,000 MW in the first half after the fourth unit and 1,250 MW after the fifth, so the October unit adds to Q3 but not Q2. Sarkaritel also credits Teesta-V resuming commercial generation and better output at Parbati-II for the revenue rise, though it does not tie these to the 65% profit growth. For an investor the practical point is that provisional billing can be trued up either way once CERC issues its order, so the final tariff matters as much as the capacity.
NHPC balance sheet, EPS and dividend after the Q2 results
Standalone debt-equity rose to 1.18 from 1.04, consolidated interest costs for the half year were Rs 1,161.93 crore (+31.4%), EPS for the quarter was Rs 1.54 and the last final dividend was Rs 0.21 per share, paid in September 2026.
| Item | Latest | Comparison | Source |
|---|---|---|---|
| Standalone debt-equity ratio | 1.18 | 1.04 a year earlier | Indian Masterminds |
| Consolidated interest, six months | Rs 1,161.93 cr | +31.4% year on year | MarketsMojo |
| Quarterly EPS (consolidated) | Rs 1.54 | Highest quarterly EPS it records | MarketsMojo |
| Share count implied by EPS (my calculation) | about 1,006 crore shares | Profit 1,549.09 / 1.54 | Derived; approximate |
| Final dividend for FY26 | Rs 0.21 per share | Paid September 2026 | Whalesbook |
| Dividend as share of the 5 Nov close (my calculation) | 0.26% | 0.21 / 80.32 | Derived; last final dividend only |
Cite this table: PositionalCalls, “NHPC Balance Sheet and Dividend Table, as of 5 November 2026”.
The rise in debt-equity is consistent with a company funding new capacity such as Subansiri Lower, while the dividend figure is the last final payout I could find, not a forecast of the next one. I found no interim dividend announcement with the Q2 results, and a board announcement or exchange filing is the only confirmation. Higher interest is the other side of the profit story: revenue from new plants has to stay ahead of financing costs.
Did NHPC profit grow from Q1 FY27?
The NHPC Q2 standalone profit rose 37.0% from Q1’s Rs 1,113.41 crore to Rs 1,525.49 crore, and Q1 plus Q2 equals the reported half-year profit of Rs 2,639 crore (my calculation).
| Standalone profit, Rs crore | Q1 FY27 | Q2 FY27 | Change | Half-year |
|---|---|---|---|---|
| FY27 | 1,113.41 | 1,525.49 | +37.0% | 2,639 (+32%) |
| FY26 (derived) | 1,071.48 | 925.52 | -13.6% | 1,997 |
Cite this table: PositionalCalls, “NHPC Q1 Versus Q2 Table, as of 5 November 2026”.
Hydro output is typically higher in the monsoon quarter and the new plants added revenue; the reports do not split how much of the 37% each explains, and the Teesta IV provision held Q2 profit down. Hydro results are seasonal, so compare Q2 with Q2 and Q1 with Q1, as the half-year growth of 32% suggests, rather than reading 37% as a trend.
The NHPC share price after Q2 results touched Rs 83.49 on 5 November against a previous close of Rs 78.45 and closed near Rs 80.32 (+2.4%), still about 7.5% below the 52-week high of Rs 86.86, per one page.
| Price point | Price (Rs) | Move | Source and caveat |
|---|---|---|---|
| 4 November close | 78.45 | – | MarketsMojo; Trendlyne implies about 78.49 |
| 5 November intraday high | 83.49 | +6.4% (my calculation) | MarketsMojo day range 78.84 to 83.49 |
| 5 November close | 80.32 | +2.38% | MarketsMojo |
| 5 November, 3:31 PM NSE | 80.60 | +2.69% | Trendlyne; volume 55.7 million shares |
| 52-week range | 68.66 to 86.86 | Close is -7.5% below the high, 17.0% above the low | MarketsMojo (my calculation) |
Cite this table: PositionalCalls, “NHPC Share Price Reaction Table, as of 5 November 2026”.
The stock traded between Rs 78.84 and Rs 83.49 and gave back about half of the high’s gain by the close, so the day’s range is wider than the closing move. MarketsMojo also shows the shares up 1.47% so far in the calendar year against a fall of 7.61% in the Sensex, and market capitalisation near Rs 80,794 crore in my estimate from the EPS-implied share count (approximate). I treat the closing prices as reported, since they differ by 28 paise across pages. If you act on price, read our capital gains tax on shares guide first.
What do analysts say about NHPC after the Q2 results?
After the NHPC Q2 results FY27, I found no brokerage target or rating notes published after the NHPC Q2 results FY27; the only third-party grade I found is MarketsMojo’s quantitative Strong Sell, which is a data-platform score, not a brokerage view.
| Item | As reported | Caveat |
|---|---|---|
| Consensus profit estimate | Rs 1,220 crore (Sahi) | Basis not stated; single source |
| Beat versus that estimate | About 27% (my calculation) | Compares consolidated Rs 1,550 crore |
| MarketsMojo grade | Strong Sell, score 27.0 | Quantitative score; financial-trend score improved from -3 to +14 |
| Brokerage targets | None found | I did not invent any |
Cite this table: PositionalCalls, “NHPC Third-Party Views Table (as reported), as of 5 November 2026”.
A quantitative grade and a consensus estimate are not recommendations from me, and I do not endorse them. Check the PSU brokerages’ own notes before relying on any target. This page gives no price target, rating or buy or sell view of its own. If you want broker coverage of NHPC, look for notes dated after 4 November 2026 and check whether they use consolidated or standalone profit, because the two differ by more than Rs 100 crore this quarter.
What to watch in NHPC Q3 FY27
After the NHPC Q2 results FY27, watch CERC tariff approvals for Subansiri Lower and Parbati-II, the full-quarter effect of the fifth Subansiri unit, finance costs, the tax share and any further provision on Teesta IV.
| What to read | Mark from Q2 | Question to ask |
|---|---|---|
| CERC tariff approval | Rs 1,231.64 cr provisional | Is revenue adjusted up or down? |
| Subansiri Lower capacity | 1,250 MW of 2,000 MW | Does the fifth unit lift revenue in Q3? |
| Finance costs | Rs 552.32 cr standalone | Do they stay near this level? |
| Tax share of PBT | About 10% implied | Does it normalise toward 15%? |
| Teesta IV | Rs 231.30 cr provision | Is there any further write-off? |
| Debt-equity | 1.18 | Does it rise again with capex? |
Cite this table: PositionalCalls, “NHPC Q3 FY27 Watch Table, as of 5 November 2026”.
What most people miss
Analyst’s note
- What stands out: new capacity lifted revenue and the PBDIT margin to 64.15%, even after a Rs 231 crore provision and a doubling of finance costs.
- Easy to miss: the three profit numbers measure different things, and part of the post-tax growth came from a low implied tax share.
- What would change the view: a CERC tariff order that cuts provisional revenue, further Teesta IV write-offs or finance costs rising faster than revenue.
- Caution: the add-back and tax shares are my arithmetic from reported figures, and no price target or buy or sell view is given.
- Reader action: pick one profit measure, state its base, then check the tax and provision notes in the filing.
Bottom line
NHPC Q2 results FY27 show consolidated profit to owners of Rs 1,549 crore (+52%) and standalone profit of Rs 1,525 crore (+65%), on revenue lifted by new plants, after a Rs 231 crore Teesta IV provision and doubled finance costs. Name the profit measure you quote, note that about 30% of standalone revenue is provisional, and confirm the lines in the filing.
Next read: the Q2 results calendar.
Part of the Earnings series.
PositionalCalls WhatsApp channel
Never miss a results-day update
- Same-day decoders for the biggest companies reporting
- One-offs separated from the underlying number
- Corrections posted openly when a figure changes
FAQs on NHPC Q2 results FY27
When were the NHPC Q2 results FY27 announced?
NHPC’s board approved the Q2 FY27 results on Wednesday, 4 November 2026 for the quarter ended 30 September 2026, with an earnings call on 5 November. Confirm the filing time on the exchange page.
What was the NHPC Q2 net profit FY27?
Consolidated profit attributable to owners was Rs 1,549 crore, up 51.7% from about Rs 1,021 crore. Total consolidated profit including minorities was Rs 1,657.57 crore (+36%), and standalone profit was Rs 1,525.49 crore (+64.8%).
Why do reports show different NHPC profit figures?
They measure different things: owners’ profit, total consolidated profit including minorities, and standalone profit, each against its own year-ago base. The differences are in the table on this page.
What was NHPC’s revenue in Q2 FY27?
Consolidated revenue from operations was Rs 4,482.55 crore (+33.2%) and total income Rs 4,669.58 crore (+28.6%). Standalone revenue was Rs 4,124.77 crore, up about 51%.
What is the Teesta IV provision in NHPC’s Q2 results?
NHPC provided Rs 231.30 crore for survey and investigation costs on the Teesta IV project that were held as capital work in progress, because implementation is uncertain. It appears to sit inside standalone expenses.
Why did NHPC’s finance costs double?
Standalone finance costs rose 105% to Rs 552.32 crore. Reports do not give the reason; new capacity such as Subansiri Lower commissioned during the year is the likely cause, as interest on completed units is expensed. This is my inference.
How much revenue came from Subansiri Lower and Parbati-II?
Together Rs 1,231.64 crore, about 30% of standalone revenue: Rs 678.17 crore from Subansiri Lower and Rs 553.47 crore from Parbati-II. Both are provisional subject to CERC tariff approval.
Did NHPC beat estimates, and was a dividend declared?
Sahi says consolidated profit beat a Rs 1,220 crore consensus by over 27%, which I could not verify. A final dividend of Rs 0.21 per share for FY26 was paid in September 2026; I found no interim dividend with Q2.
The stock touched Rs 83.49 on 5 November against a previous close of Rs 78.45 and closed near Rs 80.32 (+2.4%); another page shows Rs 80.60 at 3:31 PM. This is not a price target.
Does this page give an NHPC Q2 results FY27 buy or sell call?
No. This is research and education, not advice. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Use the numbers to frame questions and speak to a registered adviser before investing.
Sources
- PSU Watch, November 2026 (consolidated and standalone figures)
- Indian Masterminds, November 2026 (standalone costs, plants, debt-equity)
- Whalesbook, November 2026 (standalone, Teesta IV, dividend)
- Sahi, November 2026 (consolidated, EBITDA, estimate)
- Sarkaritel, November 2026 (H1 profit, generation)
- Power Peak Digest (consolidated profit Rs 1,549 crore)
- MarketsMojo, 5 November 2026 (price, PBDIT, EPS)
- Trendlyne, 5 November 2026 (earnings call, NSE price at 3:31 PM)
- BSE and NSE announcement pages: where the filing appears (I did not open it).
PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. PositionalCalls is an independent Indian stock market research and education site founded by Shubham Chaudhary. This page is education and results analysis, not a recommendation to buy, sell or hold any security. How I researched this: I read press and data-platform summaries of the filing, tied standalone income, expenses and pre-tax profit to each other, tied half-year profit to Q1 plus Q2, reconciled the three profit measures, recomputed every derived number and listed conflicts openly. I have not opened the filing.
Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive