
Learning · Tax tool
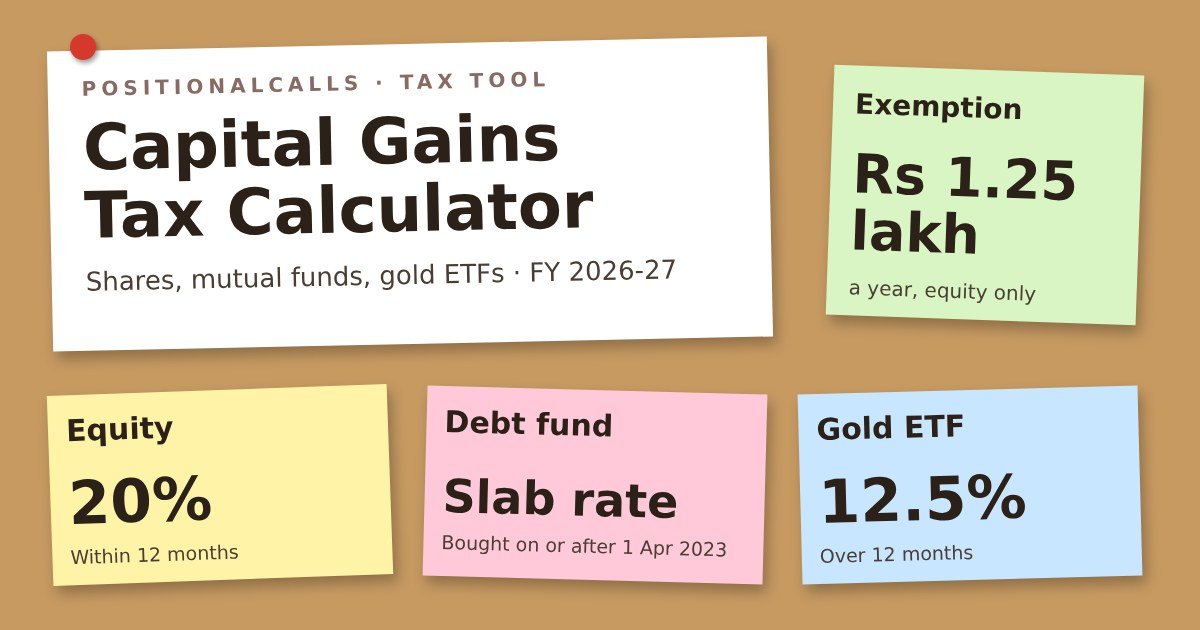
This capital gains tax calculator estimates the tax on selling listed shares, equity mutual funds, debt funds or gold ETFs in FY 2026-27, applying the 12-month and 24-month holding periods, the 20% and 12.5% rates, the Rs 1.25 lakh yearly exemption, slab-rate cases and 4% cess, with the rules and worked examples set out beneath it.
Quick answer
Enter your gain, months held and asset type in the calculator below. For FY 2026-27, listed equity is taxed at 20% within 12 months and 12.5% above Rs 1.25 lakh after that. Debt funds bought on or after 1 April 2023 are taxed at your slab rate.
Capital gains tax calculator: key takeaways
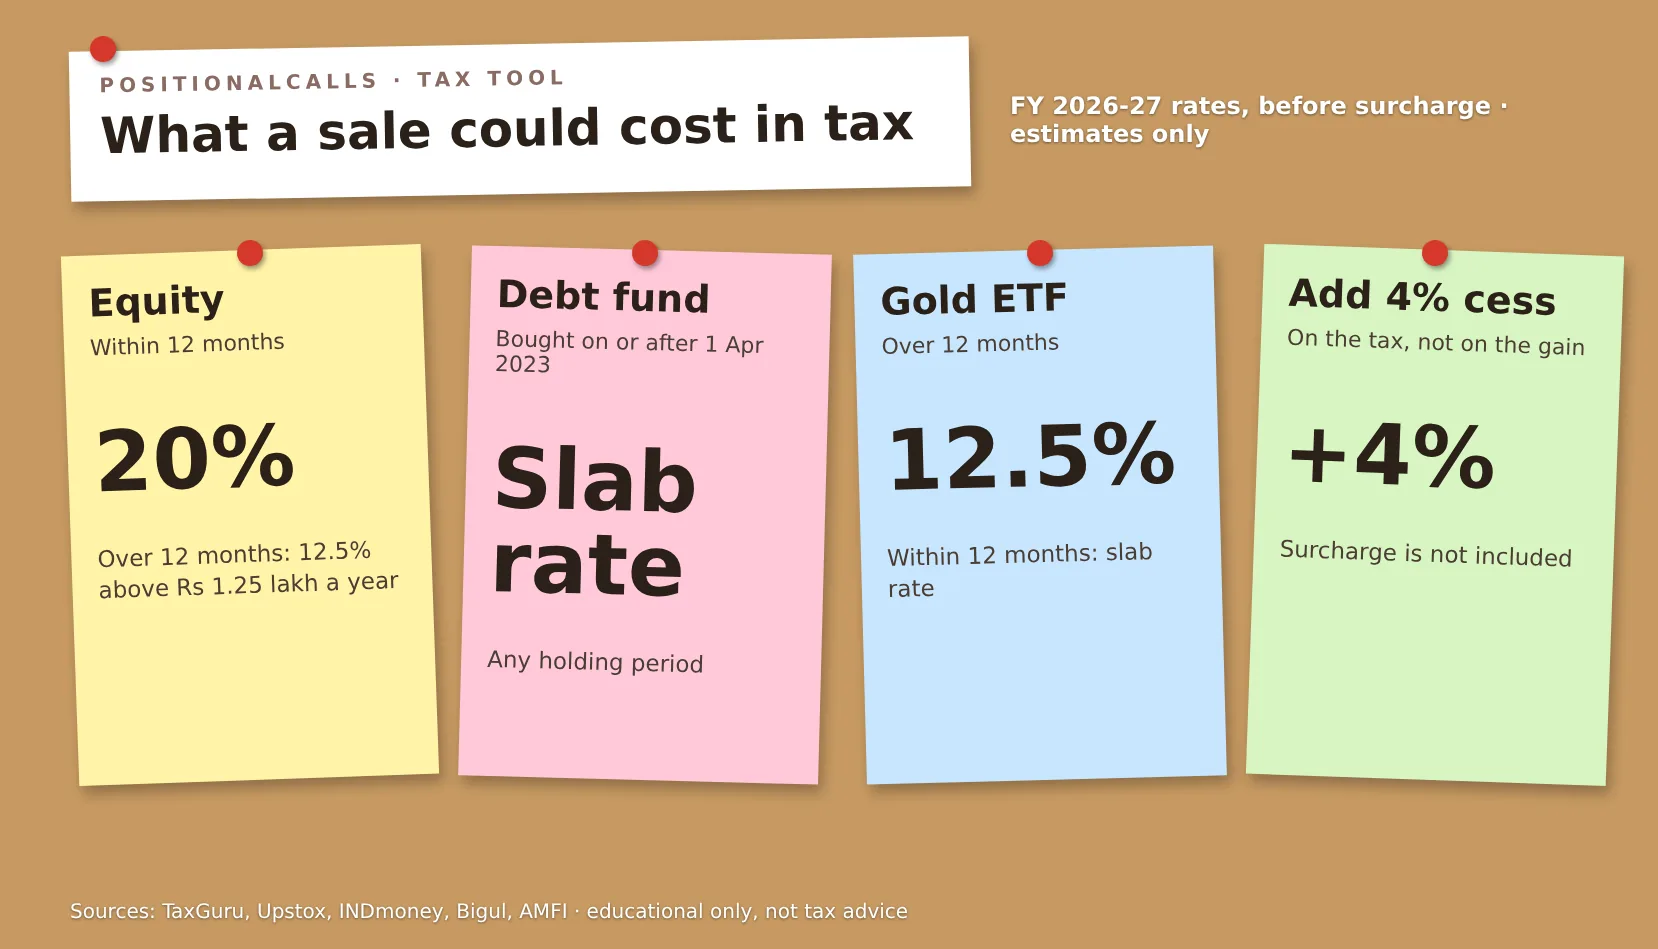
- Equity: 20% on gains from holdings of 12 months or less; 12.5% on gains above Rs 1.25 lakh a year after that.
- Debt funds: slab rate for units bought on or after 1 April 2023; 12.5% after 24 months for older units.
- Gold ETFs: 12.5% after 12 months, slab rate before.
- The exemption is shared across all your equity share and equity fund gains in the year.
- Scope: an estimate for education, not tax advice or a recommendation.
In plain words: when you sell an investment for more than you paid, the profit is a capital gain. The tax rate depends on what you sold and for how long you held it. This page asks for those facts and does the arithmetic, so that you can see roughly how much tax a sale would carry before you make it.
Data note: as of Wednesday, 18 November 2026, 3:00 PM IST. Rates and holding periods come from tax guides by TaxGuru, Sahi, INDmoney, Upstox, ClearTax, Taxmann, AMFI and others named in the sources, which say rates are unchanged for FY 2026-27. I did not open the Income-tax Act or CBDT notifications. The calculator is a simple model of those rates and has been checked against the six worked examples on this page.
Use the capital gains tax calculator for FY 2026-27
Choose the asset, enter the gain and the months you held it, and the tool shows the rate, the exemption, the tax and the cess. Nothing you type is sent anywhere; the sum runs in your browser. If you are unsure which asset type applies, the section on rates below explains each.
Exactly 12 months counts as short-term for equity and gold ETFs.
Used only for equity shares and equity funds, to apply what is left of the Rs 1.25 lakh exemption.
How do I read the result?
The first line says whether the gain is short-term or long-term, and the second shows the rate used. For equity, the exemption line shows how much of the Rs 1.25 lakh yearly limit was applied to this sale. The taxable gain is the gain after the exemption, tax before cess is the taxable gain times the rate, and cess is 4% of that tax. The last line shows total tax as a share of the gain.
What should I enter as the gain?
The gain is the sale value minus the purchase cost, with the costs your broker or fund house allows. Use the figure from your capital gains statement where you have one. If the sale is a loss, this is not the right tool, because losses are set off against gains under rules that this page does not model.
Which rates does the capital gains tax calculator apply?
The calculator applies the rates in force for FY 2026-27, which the sources I read describe as unchanged since July 2024. Equity-oriented funds with over 65% in equity follow the same rules as shares, per Bigul. The table lists what the calculator does for each asset.
| Asset | Holding period | Gain type | Rate in the calculator |
|---|---|---|---|
| Listed equity shares, equity-oriented funds | 12 months or less | STCG | 20% |
| Listed equity shares, equity-oriented funds | More than 12 months | LTCG | 12.5% above Rs 1.25 lakh a year |
| Debt fund bought on or after 1 April 2023 | Any period | Short-term | Your slab rate |
| Debt fund bought before 1 April 2023 | More than 24 months | LTCG | 12.5%, no exemption |
| Debt fund bought before 1 April 2023 | 24 months or less | STCG | Your slab rate |
| Listed gold ETF | More than 12 months | LTCG | 12.5%, no exemption |
| Listed gold ETF | 12 months or less | STCG | Your slab rate |
Cite this table: PositionalCalls, “Capital gains tax calculator rate table, FY 2026-27”; Bigul, Upstox, INDmoney, One Percent Club, TaxGuru.
Why is equity treated differently from debt funds?
Because the law does. Equity shares and equity funds have their own flat rates and a yearly exemption, while debt funds bought on or after 1 April 2023 are deemed short-term whatever the holding period. AMFI’s tax corner says gains on specified mutual funds acquired on or after that date are deemed short-term capital gains, and defines a specified fund as one with not more than 35% in domestic equity.
What does the calculator assume about the exemption?
It applies the Rs 1.25 lakh exemption only to long-term equity gains and subtracts the amount you say you have already used. INDmoney says the exemption is per investor per year and covers all equity funds and equity shares combined. The calculator does not apply it to debt funds or gold ETFs, whose long-term gains carry no exemption in the sources I read.
What do six worked examples of the capital gains tax calculator show?
The six examples below match the calculator, and the arithmetic is simple enough to check by hand. Each shows tax before cess and with 4% cess. Enter the same inputs above to see the same result.
| Case | Inputs | Taxable gain | Tax before cess | Total with 4% cess |
|---|---|---|---|---|
| 1. Equity shares, short-term | Gain Rs 1,50,000, 8 months | Rs 1,50,000 | Rs 30,000 | Rs 31,200 |
| 2. Equity fund, long-term | Gain Rs 4,00,000, 18 months, no other gains | Rs 2,75,000 | Rs 34,375 | Rs 35,750 |
| 3. Same, Rs 50,000 exemption already used | Gain Rs 4,00,000, 18 months | Rs 3,25,000 | Rs 40,625 | Rs 42,250 |
| 4. Debt fund bought after 1 April 2023 | Gain Rs 2,00,000, 30% slab | Rs 2,00,000 | Rs 60,000 | Rs 62,400 |
| 5. Gold ETF, long-term | Gain Rs 1,00,000, 15 months | Rs 1,00,000 | Rs 12,500 | Rs 13,000 |
| 6. Older debt fund, long-term | Gain Rs 3,00,000, 30 months | Rs 3,00,000 | Rs 37,500 | Rs 39,000 |
Cite this table: PositionalCalls, “Capital gains tax calculator worked examples”; arithmetic by PositionalCalls on rates from TaxGuru, Sahi, Upstox and INDmoney.
How is case 2 worked out?
The gain is Rs 4,00,000 and the holding is more than 12 months, so it is long-term. The first Rs 1,25,000 is exempt, which leaves Rs 2,75,000. At 12.5% that is Rs 34,375 before cess. Cess of 4% adds Rs 1,375, so the total is Rs 35,750. This follows the same method that Sahi and TaxGuru use in their examples, which use a Rs 3 lakh gain and give Rs 21,875 before cess.
Why does case 3 cost more than case 2?
Because Rs 50,000 of the yearly exemption was used up by earlier gains, only Rs 75,000 is left for this sale. The taxable gain rises from Rs 2,75,000 to Rs 3,25,000, which adds Rs 6,250 of tax before cess. The exemption is a single yearly pool, which is why the calculator asks about gains you have already booked.
Why is case 4 taxed so heavily compared with case 2?
The slab rate for a high earner is above the flat equity rates, and the debt fund gain gets no exemption. At a 30% slab, a Rs 2,00,000 debt fund gain carries Rs 60,000 of tax before cess, while an equity fund gain of the same size held over 12 months would be taxed at 12.5% after the exemption. This is arithmetic about how the rules differ, not a view on which fund to hold.
How does holding period change the result in the capital gains tax calculator?
Holding period decides short-term or long-term status, and only two periods remain: 12 months and 24 months. Taxmann says listed securities and units of equity-oriented funds take the 12-month period and everything else takes 24 months. The table shows the effect of one extra month on a Rs 2,00,000 equity gain.
| Months held | Gain type | Rate | Tax on Rs 2,00,000 gain, before cess |
|---|---|---|---|
| 11 | Short-term | 20% | Rs 40,000 |
| 12 | Short-term | 20% | Rs 40,000 |
| 13 | Long-term | 12.5% after Rs 1.25 lakh exemption | Rs 9,375 |
Cite this table: PositionalCalls, “Holding period effect on equity gain”; arithmetic by PositionalCalls (200000 − 125000 = 75000; 75000 × 12.5% = 9375).
Why can one month change the tax so much?
Because the rule is a cliff, not a slope. At 12 months a Rs 2,00,000 equity gain carries Rs 40,000 of tax. At 13 months, with no exemption used, only Rs 75,000 is taxable at 12.5%, which is Rs 9,375, my calculation. That gap is why the calculator asks for months held. It is also why this page stays out of timing decisions: it shows the sum, not what to do.
How is the holding period counted for shares and fund units?
It runs from the date of purchase or allotment to the date of sale, and each purchase lot has its own dates. If you bought the same share or fund on several dates, use the lot you are selling. Your broker or fund house statement lists the lots.
What changed in capital gains rates, and are the rates in the calculator current?
The rates in the calculator date from Budget 2024, effective 23 July 2024, and the sources I read say they are unchanged for FY 2026-27. Incorpx records that the Union Budget 2024 raised equity STCG from 15% to 20%, equity LTCG from 10% to 12.5% and the LTCG exemption from Rs 1 lakh to Rs 1.25 lakh.
PositionalCalls WhatsApp channel
Get tax explainers on WhatsApp
- Capital gains rules, dated
- Plain-English tax pages, no tips
- Links to updated tax guides
| Item | Before 23 July 2024 | From 23 July 2024 | Source |
|---|---|---|---|
| Equity STCG | 15% | 20% | Incorpx, Sahi |
| Equity LTCG rate | 10% | 12.5% | Incorpx, Sahi |
| LTCG exemption | Rs 1 lakh | Rs 1.25 lakh | Incorpx, Sahi |
| Long-term period for non-equity assets | 36 months | 24 months | TaxGuru, Quicko |
| Indexation | Available on some assets | Removed | TaxGuru |
Cite this table: PositionalCalls, “Capital gains rate changes”; Incorpx, Sahi, TaxGuru, Quicko.
Did Budget 2026 change the rates?
One Percent Club says Budget 2026, presented in February 2026, made no changes to mutual fund capital gains rates, and TaxGuru says rates on equity, debt, PMS and AIF investments stay unchanged for FY 2026-27. Sahi’s Budget 2026 page reaches the same view for the LTCG and STCG rates. I could not find a date for the next Union Budget in the sources I read, so I give none.
What does the Income-tax Act, 2025 change for the sums?
TaxGuru describes equity LTCG under the Income-tax Act, 2025 as applicable for Tax Year 2026-27, with the same 12.5% rate and Rs 1.25 lakh exemption. Names of years and section numbers may differ from older guides, but the rates used in this tool are the same. If your return uses new forms or terms, match the figures rather than the labels.
Why does the page keep a record of the old rates?
Because many older articles and broker pages still quote 15% and 10%, and the exemption of Rs 1 lakh. If a source shows those numbers, it predates July 2024. Checking the date of a guide before using its rate is the quickest way to avoid an error, and it is the reason the sources in this page are named with their dates where I could see them.
How do you use the capital gains tax calculator when you sell several lots?
Run the calculator once for each group of lots with the same gain type, then add the results, remembering that the exemption is shared. The table shows an illustration with three lots of an equity fund sold on 15 January 2027. The dates and gains are examples, not a record of any fund.
| Lot | Bought | Gain | Months held on 15 Jan 2027 | Gain type |
|---|---|---|---|---|
| A | 1 Jan 2025 | Rs 1,20,000 | About 24.5 | Long-term |
| B | 1 Jun 2025 | Rs 90,000 | About 19.5 | Long-term |
| C | 1 Mar 2026 | Rs 40,000 | About 10.5 | Short-term |
Cite this table: PositionalCalls, “Selling several lots, illustration”; dates and gains are examples, arithmetic by PositionalCalls.
Lots A and B give a long-term gain of Rs 2,10,000. After the Rs 1,25,000 exemption, Rs 85,000 is taxable at 12.5%, which is Rs 10,625. Lot C is short-term at 20%, which is Rs 8,000. The tax before cess is Rs 18,625, and with 4% cess the total is Rs 19,370, my calculation. In the tool, enter lots A and B together as one long-term sale of Rs 2,10,000 and lot C as a separate short-term sale.
Why should long-term lots be combined first?
Because the exemption is a single pool. If you entered lot A and lot B separately with no used amount, each would claim the full Rs 1,25,000 and the tax would be understated. Enter the second sale with the first sale’s gain in the field for gains already booked, and the pool will be applied once. The same idea applies to gains from shares sold earlier in the year.
What is a sensible order of steps for a sale?
- List the lots you plan to sell and their purchase dates.
- Classify each lot as short-term or long-term from the months held.
- Add up the long-term equity gains and apply the Rs 1.25 lakh pool once, after any gains already booked.
- Compute the short-term gains at the flat rate or the slab rate that applies.
- Add 4% cess and compare the total with the proceeds you expect.
When does a holding become long-term in dates?
Equity and gold ETF holdings become long-term when held for more than 12 months. A unit bought on 10 January 2026 reaches exactly 12 months on 10 January 2027, which is still short-term, so a sale on 11 January 2027 or later is long-term. Your broker or fund house statement shows the exact purchase date.
What does the capital gains tax calculator leave out?
The calculator is a single-sale estimate, so it leaves out items that change a full tax computation. The table lists them and where to look.
| Item left out | Why it matters | Where to check |
|---|---|---|
| Surcharge | Applies at higher income levels and raises the tax | Income Tax Department guidance, a tax professional |
| Capital losses and carry-forward | Losses reduce gains under set-off rules | Your capital gains statement and tax return |
| Other income and rebates | TaxGuru says the new-regime rebate does not cover special-rate capital gains | A full tax computation |
| Hybrid and international funds | Rules depend on structure; one conflict is flagged on the mutual fund page | Fund house tax reckoner |
| F&O, intraday, property, unlisted shares | Different rules apply | A tax professional |
| Transaction costs and STT | Reduce proceeds; STT on equity fund sale is 0.001% per Taxscan | Contract note |
Cite this table: PositionalCalls, “Capital gains tax calculator limits”; TaxGuru, Taxscan, Income Tax Department.
Does the calculator handle losses?
No. It takes a gain and returns tax. If you have losses in the same year, the net position can differ from the sum of separate estimates, so use the calculator only as a first look and settle the net figure on your return.
Why is surcharge not included?
Surcharge depends on your total income, which the calculator does not ask for. Including it would require your full income and regime, and a wrong guess would be worse than leaving it out. The note under every result says that surcharge is excluded.
How do shares, equity funds, debt funds and gold ETFs compare in the capital gains tax calculator?
The same Rs 1,00,000 gain produces very different tax depending on the asset and the holding period. The table compares them using a 30% slab rate for slab-rate cases and tax before cess.
| Asset and holding | Rate | Tax on Rs 1,00,000 gain, before cess |
|---|---|---|
| Equity shares or equity fund, 8 months | 20% | Rs 20,000 |
| Equity shares or equity fund, 18 months, no exemption left | 12.5% | Rs 12,500 |
| Debt fund bought after 1 April 2023, any period | 30% slab | Rs 30,000 |
| Older debt fund, 30 months | 12.5% | Rs 12,500 |
| Gold ETF, 15 months | 12.5% | Rs 12,500 |
| Gold ETF, 8 months | 30% slab | Rs 30,000 |
Cite this table: PositionalCalls, “Same gain, different assets”; arithmetic by PositionalCalls at a 30% slab rate and tax before cess.
What does this comparison show?
It shows that the type of asset and the holding period drive the result more than the size of the gain. The table is not a ranking of investments, because gains, risk and costs differ. It only shows how the same rupee of gain is treated.
Where can I read the rules behind the sums?
The share rules are on the capital gains tax on shares page, and the fund rules, hybrid funds and SIPs are on the mutual fund taxation in India page. Words such as STCG, LTCG and STT are explained on the stock market terms in India page.
Where do sources disagree on the rates in the capital gains tax calculator?
Sources agree on equity and gold ETFs and differ on edge cases. The table lists the differences and how the calculator treats each.
| Item | View A | View B | What the calculator does |
|---|---|---|---|
| Equity STCG holding period | 12 months or less (TaxGuru, Sahi) | Under 12 months (One Percent Club) | Treats exactly 12 months as short-term |
| Long-term period for non-equity funds | 24 months for older debt funds (INDmoney) | Often 12 months for listed assets (TaxGuru) | Uses 24 months for older debt funds and 12 months for gold ETFs |
| Hybrid funds with 35% to 65% equity | Slab short-term, 12.5% after 24 months (INDmoney) | Specified fund definition redefined from 1 April 2026 (TaxGuru) | Not included |
Cite this table: PositionalCalls, “Capital gains tax calculator source conflicts”; sources as named.
What should I check before I rely on the estimate?
- The purchase date of the lot you are selling, which sets the holding period.
- Whether the fund is equity-oriented, and whether a debt fund was bought before or after 1 April 2023.
- How much of the Rs 1.25 lakh exemption you have already used this year.
- Your slab rate, if the case is slab-rate.
- Surcharge, losses and other income, which this page leaves out.
What is this page not for?
It does not tell you what to buy or sell, when to sell or whether to sell, and it does not file a return. PositionalCalls is not a SEBI-registered research analyst or investment adviser, and I am not a chartered accountant. The tool applies published rates to numbers you supply so you can see the arithmetic.
PositionalCalls WhatsApp channel
Tax updates in one channel
- Budget and rule changes
- Explainers without tips
- Links to new tax pages
Capital gains tax calculator: frequently asked questions
How does a capital gains tax calculator work for shares?
A capital gains tax calculator takes your gain, the holding period and the asset type, picks the rate, applies any exemption and adds cess. For listed shares held 12 months or less the rate is 20%. After 12 months it is 12.5% on gains above Rs 1.25 lakh a year, per TaxGuru and Sahi.
What rate does the capital gains tax calculator use for equity mutual funds?
It uses the same rates as shares for equity-oriented funds, those with more than 65% in equity: 20% on gains from units sold within 12 months and 12.5% on gains above Rs 1.25 lakh for longer holdings, per Bigul and ClearTax. Debt funds bought on or after 1 April 2023 use the slab rate.
Does this capital gains tax calculator include surcharge?
No. It adds 4% Health and Education Cess but not surcharge, which applies at higher income levels. It also ignores capital losses, brought-forward losses and other income. Treat the result as a single-sale estimate and check your full computation before you file.
What is the Rs 1.25 lakh exemption in the capital gains tax calculator?
It is the yearly amount of long-term gain on listed equity shares and equity-oriented funds that is exempt, per TaxGuru and INDmoney. It is shared across all such gains in the year, so the calculator asks how much of it you have already used before applying it to this sale.
How is a debt fund taxed in the capital gains tax calculator?
Debt funds bought on or after 1 April 2023 are taxed at your slab rate whatever the holding period, per Upstox and Bigul. Older debt units held more than 24 months are taxed at 12.5% without indexation, per INDmoney. The calculator asks for the purchase period and your slab rate.
Are gold ETF gains in the capital gains tax calculator taxed differently?
Yes. One Percent Club and Upstox say listed gold ETFs qualify for long-term gains at 12.5% after 12 months, with short-term gains at your slab rate. The Rs 1.25 lakh exemption applies to equity shares and equity funds, so the calculator does not apply it to gold ETFs.
Why does the capital gains tax calculator ask for months held?
Because the holding period decides the rate. Equity and gold ETF holdings are long-term after more than 12 months, and older debt fund holdings after more than 24 months, per Taxmann and INDmoney. Exactly 12 months counts as short-term for equity.
Does the calculator work for F&O, intraday or property?
No. It covers delivery-based listed equity shares, equity-oriented mutual funds, debt funds and listed gold ETFs only. Intraday trades, futures and options, property, unlisted shares and foreign assets follow other rules that need a separate calculation and, usually, professional help.
Is this capital gains tax calculator investment or tax advice?
No. PositionalCalls is not a SEBI-registered research analyst or investment adviser and I am not a chartered accountant. The calculator applies published FY 2026-27 rates to the numbers you enter, publishes no buy, sell, rating or target calls and does not file your return.
How often is the capital gains tax calculator updated?
It is revised when rates, holding periods or the Income-tax Act provisions change, such as after a Union Budget. The sources I read say rates are unchanged for FY 2026-27, with the last change on 23 July 2024. Check the date at the top.
Sources for the capital gains tax calculator
- Bigul: capital gains tax, broker.
- INDmoney: mutual fund taxation, broker.
- INDmoney: capital gains tax, broker.
- TaxGuru: LTCG on equity, tax.
- TaxGuru: equity STCG and, tax.
- TaxGuru: how investment products, tax.
- TaxGuru: capital gains changes, tax.
- Sahi: LTCG tax on, broker.
- Outlook Money: tax reckoner 2026-27, press.
- Upstox: taxation in mutual, broker.
- ClearTax: how different mutual, tax.
- Taxmann: mutual fund taxation, tax.
- Taxmann: mutual fund taxation,, tax.
- AMFI: tax corner, industry.
- Incorpx: income tax on, tax.
- One Percent Club: mutual fund tax, tax.
- Arthgyaan: mutual fund taxation, tax.
- Quicko: income tax on, tax.
- Taxscan: mutual fund taxation, tax.
- Not opened: the Income-tax Act, 2025, CBDT notifications and fund house tax reckoners; the rates are from the tax guides above.
PositionalCalls.com is an independent research site founded by Shubham Chaudhary. PositionalCalls.com is not a SEBI-registered research analyst or investment adviser. Investments in securities markets are subject to market risks. Read all related documents carefully before investing. Returns are never guaranteed. This page is educational and publishes no subscribe, avoid, buy, sell, rating or target calls. Sources: published tax guides as named; no Income-tax Act text or CBDT notification opened; no investment view given. I am not a chartered accountant.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive