
Sector outlook · Consumption
Looking for the consumption sector outlook 2026? The February page called it stable to positive, with five positive drivers: urban strength, rural recovery, premium mix, easing costs and festive demand. This rebuild tests each claim against the September-quarter results, a monsoon that ended 13% below normal, four months of rising inflation and an October rate rise. It lays out what to watch, not what to buy.
Quick answer
The consumption sector outlook 2026 is mixed on current data. Company volumes grew 5% to 7% at HUL and Dabur, but market volume fell 2% in April to June, the monsoon ended 13% below normal, and CPI rose to 6.09% in October with the repo rate at 5.50%. This page names no stock.
Latest update (Saturday, 14 November 2026, 7:31 PM IST): Rebuilt on Q2 FY27 results and fresh demand data, replacing the February page that said the outlook was stable to positive. That page’s claims of stable inflation, easing input costs and gradual rural recovery are not supported by the data I found: CPI rose from 4.45% in July to 6.09% in October, and Britannia reported palm oil up 17% and milk up 16%. Filings were not opened, and valuation and institutional flow data were not found.
Key takeaways
- No stock is named: there is no rating, ranking, target or buy list. The February sections on valuation, institutional positioning and capital flows had no data and are not carried over.
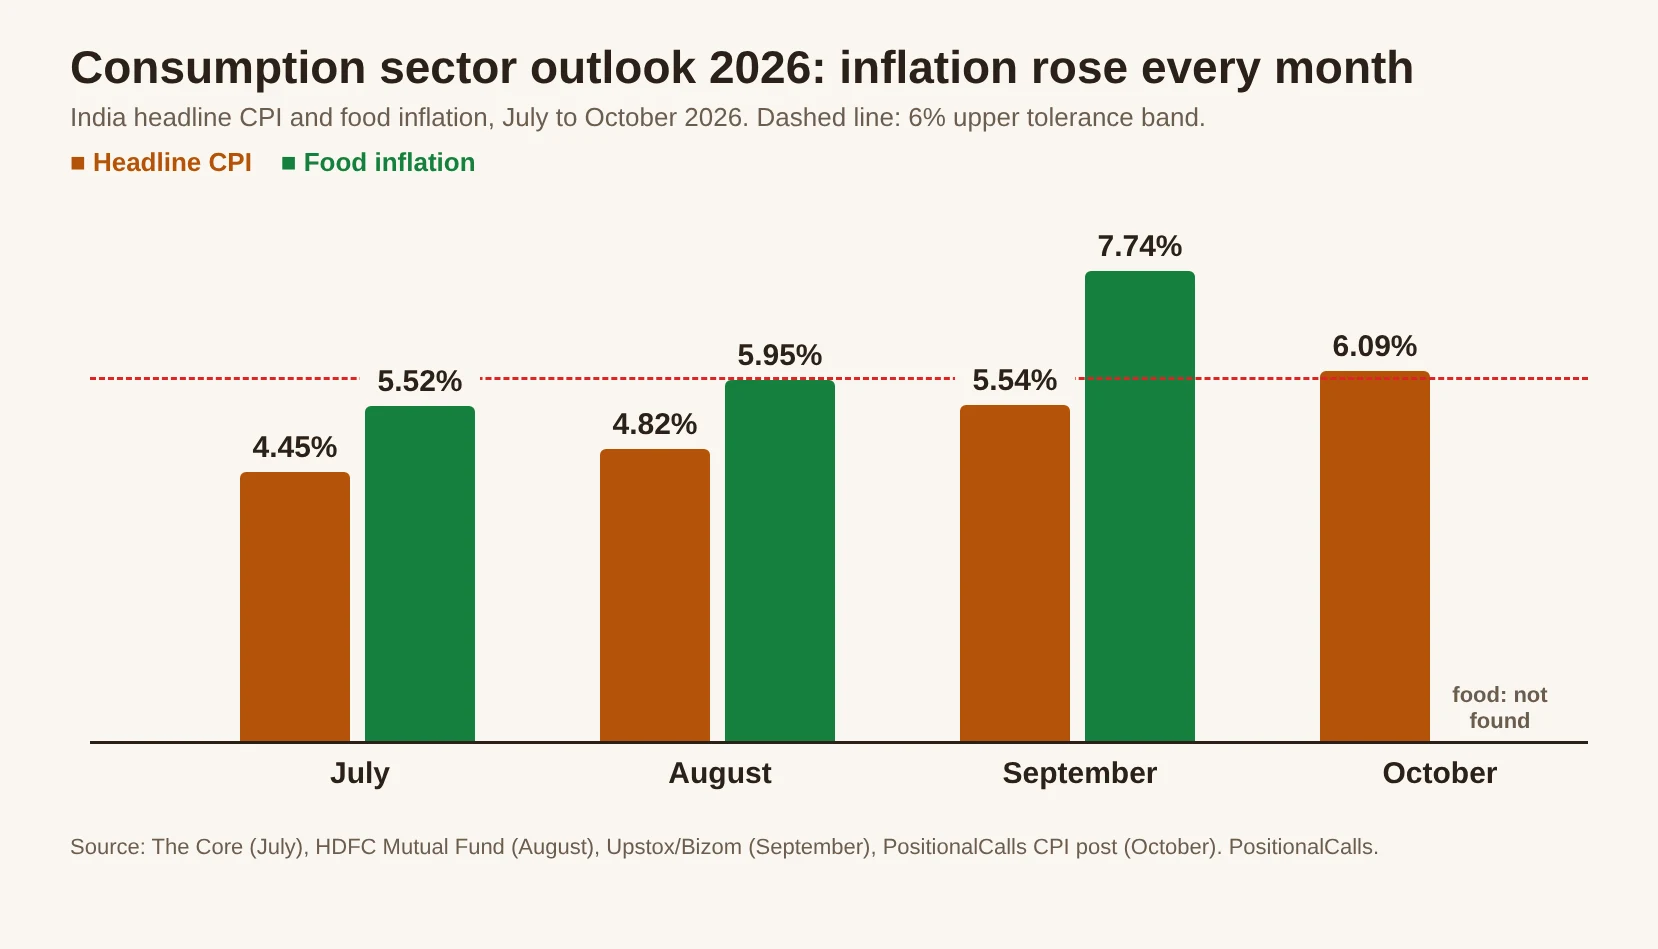
- Inflation is rising, not stable: headline CPI went from 4.45% in July to 4.82% in August, 5.54% in September and 6.09% in October, and food inflation reached 7.74% in September.
- Rural demand is a test, not a recovery: the monsoon ended about 13% below normal, kharif acreage was 1.4% lower, and NielsenIQ measured rural FMCG volume down 5% in April to June.
- Volume and price are split: market volume fell 2% while value rose 0.8% in April to June; HUL reported volume up 5% in that quarter, so large companies did better than the market.
- Costs rose: palm oil was up 21%, sugar 18% and onions 108% year on year in September, and the rupee was about 7.5% weaker, per Bizom data.
- Gaps: no Diwali 2026 sales total, no gold price series, no valuation, no institutional flow data and no filings opened, so this page cannot say the sector is cheap or expensive.
In plain words: companies sold more rupees of goods, but part of that came from higher prices, farm income may be weaker after a poor monsoon, and inflation is rising. This page shows what each piece of data says and what would change the picture.
Data note: Company results are for the quarter ended 30 September 2026, from press reports and my own result posts. Market data is from NielsenIQ (via Outlook Business), Bizom (via Upstox), the HDFC Mutual Fund monsoon note, ICRA, RAI and CAIT as reported. I did not open filings or original reports. Derived numbers are my calculation.
1. What changed in the consumption sector outlook 2026 since February?
The consumption sector outlook 2026 changed from stable to mixed: inflation has risen for four months, the monsoon ended 13% below normal, input costs rose, and Q2 FY27 profit growth split from minus 20.1% at ITC to plus 36.3% at Nestlé.
The February version of this page was headlined “5 Positive Drivers” and said the sector was in a stable-to-positive demand environment, with stable urban consumption, gradual rural recovery, premium mix lifting margins, festive demand giving revenue visibility, and easing input costs. It carried a “Snapshot FY26” table with no figures. Nine months later, the September-quarter results and several data releases are out, so each claim can be tested. For company-level numbers, see my consumption sector earnings Q2 FY27 page, which holds the result tables, and this page does not repeat them.
What the consumption sector outlook 2026 page tests
- Demand: volume against price, rural against urban, and festive retail (sections 3 to 5).
- Costs and margins: input cost changes and company margins (section 6).
- Macro: inflation, the rate rise and the rupee (section 7).
- Segments and watch items: FMCG, paint, jewellery, apparel and new-age retail, with the data that would change the picture (sections 8 and 9).
I removed the valuation and institutional-positioning sections because I have no price, multiple or flow data. The “core institutional allocation” wording was a description, not a finding, and I cannot support it.
2. Old claims against the data in the consumption sector outlook 2026
Of eight claims on the February consumption sector outlook 2026 page, the data I found contradicts two (stable inflation, easing input costs), mixes two (urban demand, rural recovery), and leaves four untested or only partly tested.
| February claim | What I found | Verdict |
|---|---|---|
| Urban consumption stable | NielsenIQ urban FMCG volume +0.1% in April to June; RBI’s September survey: 90% of urban households spent more on essentials, about one third on non-essentials | Flat volume; mixed |
| Rural demand gradually recovering | NielsenIQ rural FMCG volume -5% in April to June; monsoon 13% below normal; but September tractor registrations +14% and two-wheelers +30% (single source) | Mixed; untested for H2 |
| Premiumisation lifting margins | Dabur premium brands growing about 4x regular brands; HUL EBITDA margin fell to 22.6% from 24.0% | Mixed |
| Input costs have eased | Palm oil +21%, sugar +18%, onions +108%, freight +15% year on year in September; Britannia palm oil +17%, milk +16% | Contradicted |
| Inflation stable | CPI 4.45% in July, 4.82% August, 5.54% September, 6.09% October | Contradicted |
| Festive demand gives visibility | RAI expects double-digit festive growth but calls it a “measured recovery”; no Diwali 2026 sales total found | Untested |
| Valuations elevated in premium segments | No price or multiple data used | Untested |
| Rate hikes are a risk | The repo rate rose 25 basis points to 5.50% on 7 October | Risk has occurred |
Cite this table: Claims per the February PositionalCalls page; evidence per NielsenIQ via Outlook Business, Upstox (Bizom, RBI survey), HDFC Mutual Fund, my CPI post and Q2 FY27 company reports; filings not opened.
The pattern is that the February page described conditions that looked benign when inflation was low and rain was forecast. Since then inflation rose and the monsoon failed to deliver, so the consumption sector outlook 2026 rests on how companies and households absorb higher prices. No stock view follows from this table.
3. Volume and price in the consumption sector outlook 2026
Market FMCG volume fell 2% in April to June while value rose 0.8%, and distributor data shows value up 8.6% in July to September, so price is carrying growth more than volume, while large companies such as HUL did better than the market.
| Measure | Reading | Period | Source |
|---|---|---|---|
| FMCG volume | -2% (rural -5%, urban +0.1%) | April to June 2026 | NielsenIQ via Outlook Business |
| FMCG value | +0.8% (rural -2.9%, urban +3.0%) | April to June 2026 | NielsenIQ via Outlook Business |
| FMCG price | +2.8% | April to June 2026 | NielsenIQ via Outlook Business |
| Categories with falling volume | 68% (33% down more than 5%); 8% grew | April to June 2026 | NielsenIQ via Outlook Business |
| Rupee sales (distributor data) | +8.6%, fastest in six quarters | July to September 2026 | Bizom via Upstox |
| HUL volume | +5% on revenue +10% | April to June 2026 | Upstox |
| HUL underlying volume growth | 7% on underlying sales growth 15% | July to September 2026 | My HUL post |
| Dabur India underlying volume growth | 5.5% | July to September 2026 | Kotak Neo |
Cite this table: Market data per NielsenIQ (via Outlook Business, 29 September 2026) and Bizom (via Upstox, updated 6 November 2026); company data per my result posts; filings and original reports not opened; periods differ.
Three points follow. First, the market and the large companies are different things: NielsenIQ’s April to June volume fell 2% while HUL, per Upstox, reported volume up 5% in the same quarter, and NielsenIQ’s own comment is that large manufacturers are more resilient. Second, Upstox notes that price has contributed more than volume to growth for five quarters in a row. Third, NielsenIQ’s July to September figures were not available to me, so the latest measured market volume is a quarter older than the company results. Outlook Business labelled the April to June quarter “Q2 FY26” in its summary, which conflicts with its body; I use the dates in the body.
| Channel (April to June 2026) | Value | Volume |
|---|---|---|
| Traditional trade | -4.2% | -6.0% |
| Modern trade | +15.5% | +17.5% |
| E-commerce | +57.7% | +34.8% |
Cite this table: Channel growth per NielsenIQ via Outlook Business; NielsenIQ separately states that e-commerce is 7% of FMCG sales nationally; these are single-source figures.
The channel split shows where the volume went: out of traditional shops and into modern trade and e-commerce. That matters for small and mid-sized brands, which depend on traditional trade. I found no company-level channel split to say who gained. See my HUL Q2 results FY27, Dabur Q2 results FY27 and Britannia Q2 results FY27 pages for what each reported.
4. Rural demand and the monsoon in the consumption sector outlook 2026
The monsoon ended about 13% below normal and kharif acreage was 1.4% lower, so rural demand in the second half of FY27 is a test, with ICRA expecting agriculture growth of 1.3% against 3.3% a year earlier, though irrigation, stocks and cash transfers act as buffers.
| Rural indicator | Reading | Source |
|---|---|---|
| Monsoon rainfall against long period average | About 13% below at 30 September (8% above in 2025); South and East/Northeast about 20% or more below | HDFC Mutual Fund, updated 6 October 2026 |
| Kharif acreage | -1.4%; rice -3.7%, pulses +1.5%, coarse cereals +0.6%, oilseeds flat | HDFC Mutual Fund |
| Reservoir storage | 71% of live capacity; South 52% | HDFC Mutual Fund |
| Agriculture GVA growth FY27 | ICRA: 1.3%, against 3.3% in FY26 | ICRA, 1 September 2026 |
| Real rural wages | ICRA flags declining real wages and weak sentiment as a risk for H2 FY27 | ICRA |
| Rural against urban inflation (August) | 5.2% against 4.3% | HDFC Mutual Fund |
| Buffers | Irrigated area about 60% of net sown area; foodgrain stocks 870 lakh tonnes, nearly three times the buffer norm; PM-KISAN Rs 6,000 a year | HDFC Mutual Fund |
| September registrations | Tractors +14%, two-wheelers +30% year on year | HDFC Mutual Fund |
Cite this table: Rural data per HDFC Mutual Fund and ICRA as reported; I did not open the original IMD or Ministry data; the registration figures are a single source.
The old page said rural consumption was gradually recovering on better farm incomes and stable inflation. The data is split. Registrations rose in September, which is a point for rural purchasing power, but NielsenIQ measured rural FMCG volume down 5% in April to June, rural inflation is above urban, and ICRA expects real rural wages to weigh on demand in the second half. The rural recovery claim is therefore untested, not confirmed. The monsoon effect works with a lag, through rabi sowing and farm income, so the Q3 and Q4 results will show more than Q2 did.
Rural demand data the consumption sector outlook 2026 still lacks
- Rabi sowing and post-monsoon rainfall, which ICRA says will decide the South and North.
- NielsenIQ July to September rural volume, which I did not find.
- Rural wage growth in nominal terms.
- A company-level rural share for HUL, Dabur or Britannia.
5. Urban demand and the festive season in the consumption sector outlook 2026
Urban demand looks resilient in value but selective in spending: retail grew 8% in July, 90% of urban households spent more on essentials, only about a third spent more on non-essentials, and no Diwali 2026 sales total had been found.
| Urban indicator | Reading | Source |
|---|---|---|
| Retail sales growth, July 2026 | +8% year on year; store-level demand +7.1% | RAI via The Core, 10 September 2026 |
| RAI festive view | Double-digit festive growth expected, described as a “measured recovery rather than complete confidence” | RAI via The Core |
| Last year’s festive trade | Rs 6.05 lakh crore, +25% on 2024 | CAIT via The Core |
| Share of annual apparel sales in festive and wedding season | About 35% | CRISIL via The Core |
| Household spending (RBI September survey) | 90% of urban households spending more on essentials; about one third on non-essentials | Upstox |
| Retailers absorbing costs (CMAI survey) | About 54% absorbing higher costs through lower margins; about 35% raised prices | The Core |
| FMCG demand projection, August to November | Equirus Capital: +9% to +11% | The Core, citing a July tracker |
| Company reading | Trent standalone revenue +19% in Q1 FY27; Titan total income +25% in Q2; Nykaa revenue +28%; Lenskart +35.7% | The Core; my result posts |
Cite this table: Urban data per RAI, CAIT, CRISIL, CMAI, Equirus and the RBI survey as reported by The Core and Upstox; I did not open the original reports; projections are third-party views, not mine.
PositionalCalls WhatsApp channel
Track inflation and demand data plainly
- Sector data without tips
- Monthly inflation and rate checks
- A message when this page is updated
The festive total for 2026 is the missing figure. CAIT put last year’s festive trade at Rs 6.05 lakh crore, and a similar figure for this year would test the “festive visibility” claim, but I did not find one. The cautious reading, which the RAI’s own wording supports, is that urban spending is being steered to essentials and to value, while premium and new-age retail such as Titan, Nykaa and Lenskart grew strongly in the September quarter. Those growth rates came from different bases and one-offs, so I do not read them as a trend; see the Titan Q2 results FY27, Nykaa Q2 results FY27 and Lenskart Q2 results FY27 pages.
6. Costs, margins and pricing in the consumption sector outlook 2026
Costs rose, not eased: in September palm oil was up 21%, sugar 18%, onions 108% and freight 15% year on year, the rupee was 7.5% weaker, and margins fell at HUL, Page and Berger in Q2.
| Input, September 2026 against a year earlier | Change | Source |
|---|---|---|
| Onions | +108% | Bizom via Upstox |
| Ginger | +63% | Bizom via Upstox |
| Garlic | +55% | Bizom via Upstox |
| Palm oil | +21% | Bizom via Upstox |
| Sugar | +18% | Bizom via Upstox |
| Freight | +15% | Bizom via Upstox |
| Food prices overall | +7.7% | Bizom via Upstox |
| Rupee against the US dollar | About 7.5% weaker | Bizom via Upstox |
Cite this table: Input cost changes per Bizom as reported by Upstox; company-specific input costs (Britannia: palm oil +17%, milk +16%, laminate +18%, flour -4%) per Multibagg.
| Company Q2 FY27 | Margin reading | Pricing signal |
|---|---|---|
| HUL | EBITDA margin 22.6% against 24.0% | Underlying sales growth 15% on volume 7% |
| Page Industries | 20.8% against about 21.65% | Revenue per piece up about 5.7% (my calculation) |
| Berger Paints | About 11.6% against 12.4% (derived) | Price increases from November; raw materials not easing |
| Britannia | About 17.0%, against 15.3% in Q1 | Cites commodity covers; terms not given |
| Nykaa | 8.7% against about 6.8% (derived) | GMV +30% |
Cite this table: Margins per my result posts and Multibagg; definitions differ and several are my derivations; see the consumption earnings page for details; filings not opened.
Companies that raise prices protect margin if volume holds. Berger said prices would rise from November, and the market is already price-led, since NielsenIQ’s price growth of 2.8% came with a 2% fall in volume. A second round of price rises therefore tests the volume. The CMAI retailer survey, in which 54% were absorbing costs, suggests the same strain in retail.
7. Inflation, rates and the rupee in the consumption sector outlook 2026
Headline CPI rose from 4.45% in July to 6.09% in October, the repo rate rose 25 basis points to 5.50% on 7 October, and ICRA expects another 25 basis point rise in December, so rates and prices weigh on the consumption sector outlook 2026.
| Month (2026) | Headline CPI | Food inflation | Source |
|---|---|---|---|
| July | 4.45% | 5.52% | The Core |
| August | 4.82% | 5.95% | HDFC Mutual Fund |
| September | 5.54% | 7.74% | Upstox (Bizom) |
| October | 6.09% | Not found | My CPI post |
Cite this table: Inflation per the sources shown; the October CPI figure per my post, which cites MoSPI; ICRA says October breached the upper end of the 2% to 6% band.
The old page said inflation was stable and listed rate rises as a risk. Both have changed: inflation rose each month from July, and the repo rate rose to 5.50% on 7 October, per an aggregator page I did not confirm against the RBI statement. ICRA’s November comment, which I did not open in full, foresees another 25 basis point rise in December; that is one firm’s view, not a decision. Bank credit grew 17.94% in mid-October per RBI data via The Week, so credit has not yet slowed. Rate rises matter most for credit-linked purchases such as jewellery, appliances and vehicles; for those, see the auto sector outlook 2026 and banking sector outlook 2026. For the October reading see my India CPI inflation October 2026 post.
8. Segments in the consumption sector outlook 2026
Segments differ: staples had volume growth but margin pressure, paint had price rises planned, jewellery had a duty gain, and new-age retail grew off small bases, so no one reading covers the consumption sector outlook 2026.
| Segment | What Q2 FY27 showed | What the data cannot yet say |
|---|---|---|
| Staples (food, home, personal care) | HUL volume 7%, Dabur India volume 5.5%, Britannia revenue +16.6%; HUL margin down; ITC profit -20.1% standalone | Whether volume holds after price rises; July to September market volume |
| Paint | Berger revenue +13.2%, profit +5.2%, margin down; prices rising from November | Whether volume holds; Asian Paints growth not found |
| Jewellery | Titan jewellery +24%; Rs 536 crore duty gain was about 23% of pre-tax profit | Gold price effect; volume; festive total |
| Apparel and innerwear | Page revenue +11.5%, volume +5.5%, profit +4.0%; Trent +19% in Q1 | Footfall and festive sales; Trent and Bata Q2 not covered |
| New-age retail | Nykaa profit +207% and Lenskart +124.7%, off small bases | Sustainability of growth and margins |
| Premium and mass split | Dabur premium about 4x regular brands | Whether mass products slow in a weak rural year |
Cite this table: Segment readings per my result posts and Kotak Neo; filings not opened; see the earnings page for the full tables.
See Page Industries Q2 results FY27, Berger Paints Q2 results FY27 and ITC Q2 results FY27 for company data. I have not compared companies on valuation or recommended any of them.
9. What to watch next in the consumption sector outlook 2026
The consumption sector outlook 2026 turns on four observable things: rabi sowing and rural volume, the December inflation and rate readings, whether price rises hold volume, and the Q3 FY27 results, which I expect in January to February 2027 though I have not found dates.
| Watch item | What would be a stronger reading | What would be a weaker reading |
|---|---|---|
| Rural volume (NielsenIQ, company commentary) | Rural volume turns positive after a weak monsoon | Rural volume stays negative and tractor and two-wheeler data fade |
| Inflation and rates | CPI falls back toward 6% and no further hike | CPI keeps rising and the repo rate rises again in December |
| Price and volume | Berger and others raise prices and volumes hold | Volume falls as prices rise, as the market did in April to June |
| Input costs | Palm oil, sugar and onion prices ease | They stay above last year and the rupee weakens further |
| Festive total and Q3 results | Revenue growth with stable margins | Revenue growth with falling margins |
| One-offs | Profit growth without gains such as Titan’s duty credit | Profit growth that depends on one-off gains |
Cite this table: Watch list by PositionalCalls; these are conditions to check, not forecasts or probabilities.
This is a checklist, not a forecast. I assign no probability and no target to any item. If you track the sector, record the dates of the NielsenIQ and Bizom releases, because they lead company results by about a month.
10. What are the risks in the consumption sector outlook 2026?
The main risks are a rural demand slowdown after a weak monsoon, inflation above 6%, a second rate rise, price rises that cut volume, and one-off gains that overstate profit.
11. What most people miss in the consumption sector outlook 2026, and how to check
- What stands out: inflation rose in each of four months while the February page called it stable, and the monsoon ended 13% below normal.
- Easy to miss: company volumes beat the market. HUL volume +5% against market volume -2% in April to June, so a staples firm’s result is not the sector’s result.
- What would change the picture: rabi sowing, December inflation, the next rate decision, and whether volume holds after price rises.
- Caution: this page does not say which consumption stock to buy, and it has no valuation or flow data.
- Separate market from company: compare NielsenIQ market volume with company volume for the same quarter.
- Check the basis: volume or value, standalone or consolidated.
- Read the monsoon with a lag: look at rabi sowing and rural volume in the next two quarters.
- Track inflation: read the CPI release and the repo decision together.
- Strip one-offs: check gains and charges in each result.
- Check input costs: palm oil, sugar, milk and freight.
- Check valuation separately: use current prices from the exchange; this page does not.
- Plan the tax: see my dividend tax in India guide and capital gains tax on shares guide.
For other sectors see my banking sector outlook 2026, auto sector outlook 2026, pharma sector outlook 2026 and IT sector outlook 2026. For the company numbers behind this page, see my consumption sector earnings Q2 FY27 page.
Bottom line
The consumption sector outlook 2026 is mixed. Revenue grew at all twelve companies in Q2 FY27, but market volume was falling, inflation rose to 6.09%, the monsoon ended 13% below normal, input costs rose and the repo rate went to 5.50%. The February claims of stable inflation and easing costs are not supported. Watch rural volume, December inflation and the Q3 results, and read the filings.
Next read: see the data on the consumption sector earnings Q2 FY27 page.
Part of the Sector Outlook series on PositionalCalls.
PositionalCalls WhatsApp channel
Keep the consumption outlook in one place
- Rural and urban demand updates
- Input cost and rate watch
- Updates when new data is out
FAQs on the consumption sector outlook 2026
What is the consumption sector outlook 2026?
The consumption sector outlook 2026 is mixed on the data I found. Company volumes rose at HUL and Dabur, but market volume fell 2% in April to June, inflation reached 6.09% in October, the monsoon ended 13% below normal and the repo rate rose to 5.50%. The February claim of a stable-to-positive outlook is not supported as a whole.
Did the monsoon hurt the consumption sector outlook 2026?
Possibly, with a lag. Rainfall ended about 13% below normal, kharif acreage fell 1.4%, and ICRA expects agriculture growth of 1.3% against 3.3% a year earlier. Buffers include irrigation, foodgrain stocks and PM-KISAN, and September tractor and two-wheeler registrations rose. The effect on rural volume will show in the next two quarters.
Is rural demand recovering in the consumption sector outlook 2026?
The data is split. NielsenIQ measured rural FMCG volume down 5% in April to June, and ICRA flags weak real rural wages for the second half. But tractor registrations rose about 14% and two-wheelers about 30% in September, per one source. I treat the recovery claim as untested, not confirmed.
Has inflation changed the consumption sector outlook 2026?
Yes. Headline CPI rose from 4.45% in July to 4.82% in August, 5.54% in September and 6.09% in October, and food inflation reached 7.74% in September. The February page called inflation stable. Rising prices push companies to raise prices, and volume then has to hold. I do not forecast the next reading.
What did input costs do in September 2026?
Per Bizom data, palm oil rose 21%, sugar 18%, onions 108% and freight 15% year on year, and the rupee was about 7.5% weaker. Britannia separately reported palm oil up 17% and milk up 16%. Only flour fell, by 4%. The February claim that costs had eased is contradicted by these figures.
Is FMCG volume growing in the consumption sector outlook 2026?
The market is not. NielsenIQ reported FMCG volume down 2% and value up 0.8% in April to June, with 68% of categories falling in volume. Large companies did better: HUL reported volume up 5% in that quarter. I did not find NielsenIQ’s July to September figures, so the latest market reading is older than the results.
Did the repo rate change affect the consumption sector outlook 2026?
The repo rate rose 25 basis points to 5.50% on 7 October, per an aggregator page I did not confirm against the RBI statement. ICRA foresees another 25 basis points in December, which is one firm’s view. Rate rises matter most for credit-linked purchases such as jewellery and appliances. I found no sales data showing an effect yet.
What should I watch next in the consumption sector outlook 2026?
Watch rabi sowing and rural volume, the December inflation and rate readings, whether price rises such as Berger’s from November hold volume, and the Q3 FY27 results, which I expect in January to February 2027 though I found no dates. These are checks, not forecasts, and I assign no probabilities to them.
Does this page say which consumption stocks to buy?
No. This page names no stock to buy and gives no rating or target. It reports data and where the data is missing, such as valuation, institutional flows, gold prices and a Diwali 2026 sales total. Company-level facts are in my earnings and result pages. Read the filings and consider a registered adviser before investing.
How is the consumption sector outlook 2026 page different from the earnings page?
This page looks forward and tests the old outlook claims against demand, rural, inflation and cost data. The consumption sector earnings page holds the Q2 FY27 company tables, one-offs and dividends for twelve companies. Use the earnings page for results, and this one for the conditions that may shape the next two quarters.
Sources
- Outlook Business: FMCG slowdown is splitting India’s consumer basket; NielsenIQ April to June 2026 data, 29 September 2026.
- NielsenIQ: India FMCG Quarterly Snapshot Q2 2026; e-commerce share only; the full report was not opened.
- Upstox: FMCG sales are rising but your shopping bag doesn’t feel heavy; Bizom data, input costs, RBI survey, updated 6 November 2026.
- HDFC Mutual Fund: Monsoon 2026 ends below normal, rural India has more buffers; rainfall, kharif, reservoirs, buffers, updated 6 October 2026.
- ICRA: deficient rainfall, inflation risks and weak crop output; rural demand outlook, 1 September 2026; a November comment listed on the page was not opened in full.
- The Core: India festive season retail 2026; RAI, CAIT, CRISIL, CMAI and Equirus data, 10 September 2026.
- Kotak Neo: Dabur Q2 FY27 results; volume and premium data.
- Multibagg: Britannia Q2 margin and input costs; company input costs.
- PositionalCalls: Consumption sector earnings Q2 FY27 (company tables).
- PositionalCalls: India CPI inflation October 2026 (October CPI).
- PositionalCalls: HUL Q2 FY27 results (company data).
- Ministry of Statistics and Programme Implementation: official CPI and consumption data.
- Reserve Bank of India: official repo rate and policy statements.
- Named, not linked: an aggregator page for the 7 October repo rate rise; RAI and CAIT data as reported by The Core; Equirus Capital’s July tracker. I opened none of the original reports or any BSE or NSE filing for this page.

Shubham Chaudhary is the founder of PositionalCalls, an independent Indian stock market research website. He writes company fundamentals, quarterly results analysis, IPO analysis and sector research for NSE and BSE listed companies, with a focus on banking stocks, insurance and long-term value investing. Every article is built from primary sources such as RBI, SEBI, NSE and BSE filings and company annual reports, and states its risks plainly in simple language for retail investors.
Coverage areas Our research standards- Numbers checked against NSE, BSE and SEBI filings
- Risks and limits stated in every article
- No paid promotions or broker tie-ups
- Articles updated when new filings arrive